
What Akamai Technologies Stock's Anthropic AI Deal Means For Shareholders
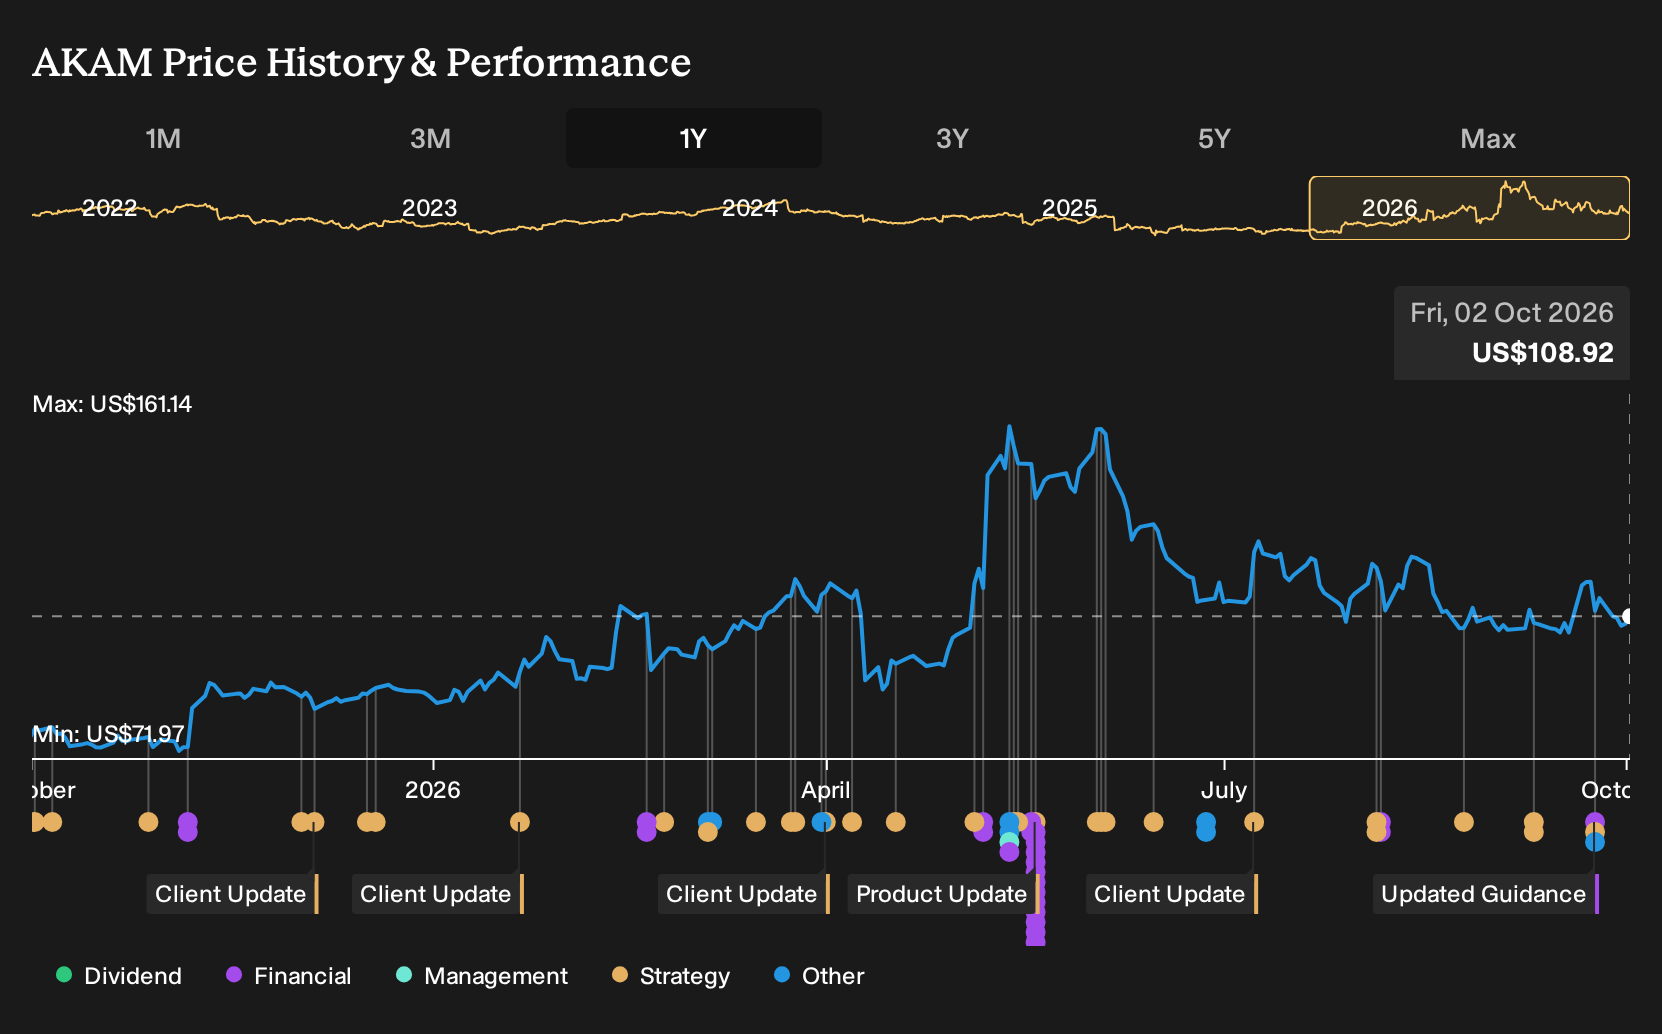
- In September 2026, Akamai Technologies disclosed 2027 earnings guidance of approximately $150 million to $300 million and announced a significantly expanded relationship with Anthropic that includes an $11.6b contractual commitment over seven years, with the option to increase the deal value to about $20b.
- The Anthropic agreement gives Akamai Technologies long-term visibility on AI infrastructure demand and highlights how large, CPU-intensive workloads may shape the business mix and capital needs over the coming years.
- We will now assess how Akamai Technologies' Anthropic AI infrastructure commitment might reshape the investment narrative around compute growth and risk.
Scan how Akamai Technologies fits into the AI infrastructure race by comparing it with a curated set of 90 AI infrastructure stocks powering similar large scale compute commitments.
Akamai Technologies Investment Narrative Recap
To own Akamai Technologies, you need to believe the shift from its maturing content delivery unit toward security and compute can support a healthier mix of recurring, infrastructure style revenue. The 2027 earnings guidance of about $150 million to $300 million anchors expectations and signals management is balancing growth investments with profitability targets.
The near term catalyst now sits in how effectively Akamai converts signed AI and cloud deals into active workloads without putting too much pressure on operating margin. The biggest risk remains execution on heavy CapEx and customer concentration. Large deployments that scale slower than expected could weigh on returns from this build out.
The Anthropic agreement is the clearest operational lens on that trade off. A contractual commitment of $11.6b over seven years, with a path to about $20b, ties Akamai Technologies directly to one of the more demanding AI CPU customers and tests the resilience of its distributed infrastructure and software stack.
For you as a shareholder, that contract can act as both catalyst and stress test. It sharpens visibility on AI oriented compute demand while amplifying exposure to a single client and to CapEx and capacity planning decisions. Execution on deployment timelines, reliability and economics around this Anthropic build will likely shape how investors view the broader AI infrastructure opportunity at Akamai.
Akamai Technologies' current earnings sit at $411.0 million, with analyst consensus pointing to $736.0 million by 2029 and projected revenues of $7.2 billion in the same year. That outlook assumes revenue expands at 18.7% a year and implies an earnings increase of about $325.0 million from today.
Uncover how Akamai Technologies' fair value indicates a 46% potential upside to its current price before the discount closes.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Akamai Technologies' heavy GPU and colocation spending as a key upside catalyst, not just a margin risk. Before this Anthropic news, the bullish camp was already modeling about $6.3b in 2029 revenue and $961.0m in earnings. That is far above consensus. Use that spread to test where your own expectations sit and how this fresh guidance and contract might shift those views.
Explore 3 other Akamai Technologies fair value estimates, including one that suggests as much as 46% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Akamai Technologies research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Akamai Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Akamai Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Akamai Technologies?
Once you have a view on Akamai Technologies, it can help to widen the lens and compare it with other businesses that fit different risk and return profiles. The Simply Wall St Screener makes that easier by letting you filter for traits that match your own approach instead of relying on headlines.
- If you want potential upside with a lower focus on downside swings, start by scanning a set of 31 resilient stocks with low risk scores that have passed a tight risk filter.
- For investors who care about balance sheet strength before anything else, review a curated list of solid balance sheet and fundamentals (26 results) that can handle tougher conditions.
- If you are hunting for under followed stories with solid fundamentals, work through a hand picked 19 high quality undiscovered gems that many portfolios may not hold yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com