
Will Hold Rating Cut Change First Industrial Realty Trust Stock Narrative
- First Industrial Realty Trust, a U.S. industrial REIT focused on logistics properties, was recently downgraded to a HOLD rating by Argus following its ongoing efforts to balance development, asset sales and portfolio management.
- The downgrade highlights how dependent First Industrial Realty Trust is on converting its development pipeline and entitled land into leased space at targeted cash yields, while keeping occupancy and tenant quality within guidance.
- We will now assess how First Industrial Realty Trust's investment narrative could be influenced by Argus shifting its rating to HOLD.
Compare how First Industrial Realty Trust stacks up against other logistics focused landlords by scanning the list of solid balance sheet and fundamentals (26 results) for potential alternatives in the same space.
First Industrial Realty Trust Investment Narrative Recap
To own First Industrial Realty Trust, you need to be comfortable with a logistics focused REIT that leans heavily on embedded rent increases, new developments and disciplined asset recycling. The short term hinge point is execution on lease up. Management is targeting occupancy around 94% to 95% in 2026, so filling space at healthy rents is central to the story.
The biggest near term risk sits on the same axis. If occupancy does not move from roughly 93.5% toward 95.5% as guided, revenue and funds from operations could undershoot expectations. The Argus shift to a HOLD rating does not change those operational swing factors; it mainly reframes how external analysts are choosing to weigh them.
With no new company announcements tied directly to the Argus report, the most relevant backdrop is the recent operational data already disclosed. Management has highlighted strong rent mark to market in 2026, with cash rent steps on new and renewal leases running at 39% year to date and guidance of 35% to 40% on commencements. That embedded uplift is a key offset to any softness in occupancy.
Those rent spreads matter because they support funds from operations even if incremental development returns tighten due to higher land costs, including pressure from data center buyers bidding up key sites. For you as a shareholder or prospective investor, the practical question is whether First Industrial Realty Trust can keep converting its development pipeline at roughly 7% cash yields while managing activism driven costs and debt coverage so those leasing gains translate cleanly into long term cash flow.
First Industrial Realty Trust's current analyst narrative points to US$928.9 million in revenue and US$291.8 million in earnings by 2029, built on an assumed 6.9% yearly revenue growth rate and a move from US$364.2 million of earnings today to that lower 2029 consensus figure. This implies an earnings decline of about US$72.4 million over the period.
Uncover why First Industrial Realty Trust's fair value indicates a 22% potential upside to its current price that may not last much longer.
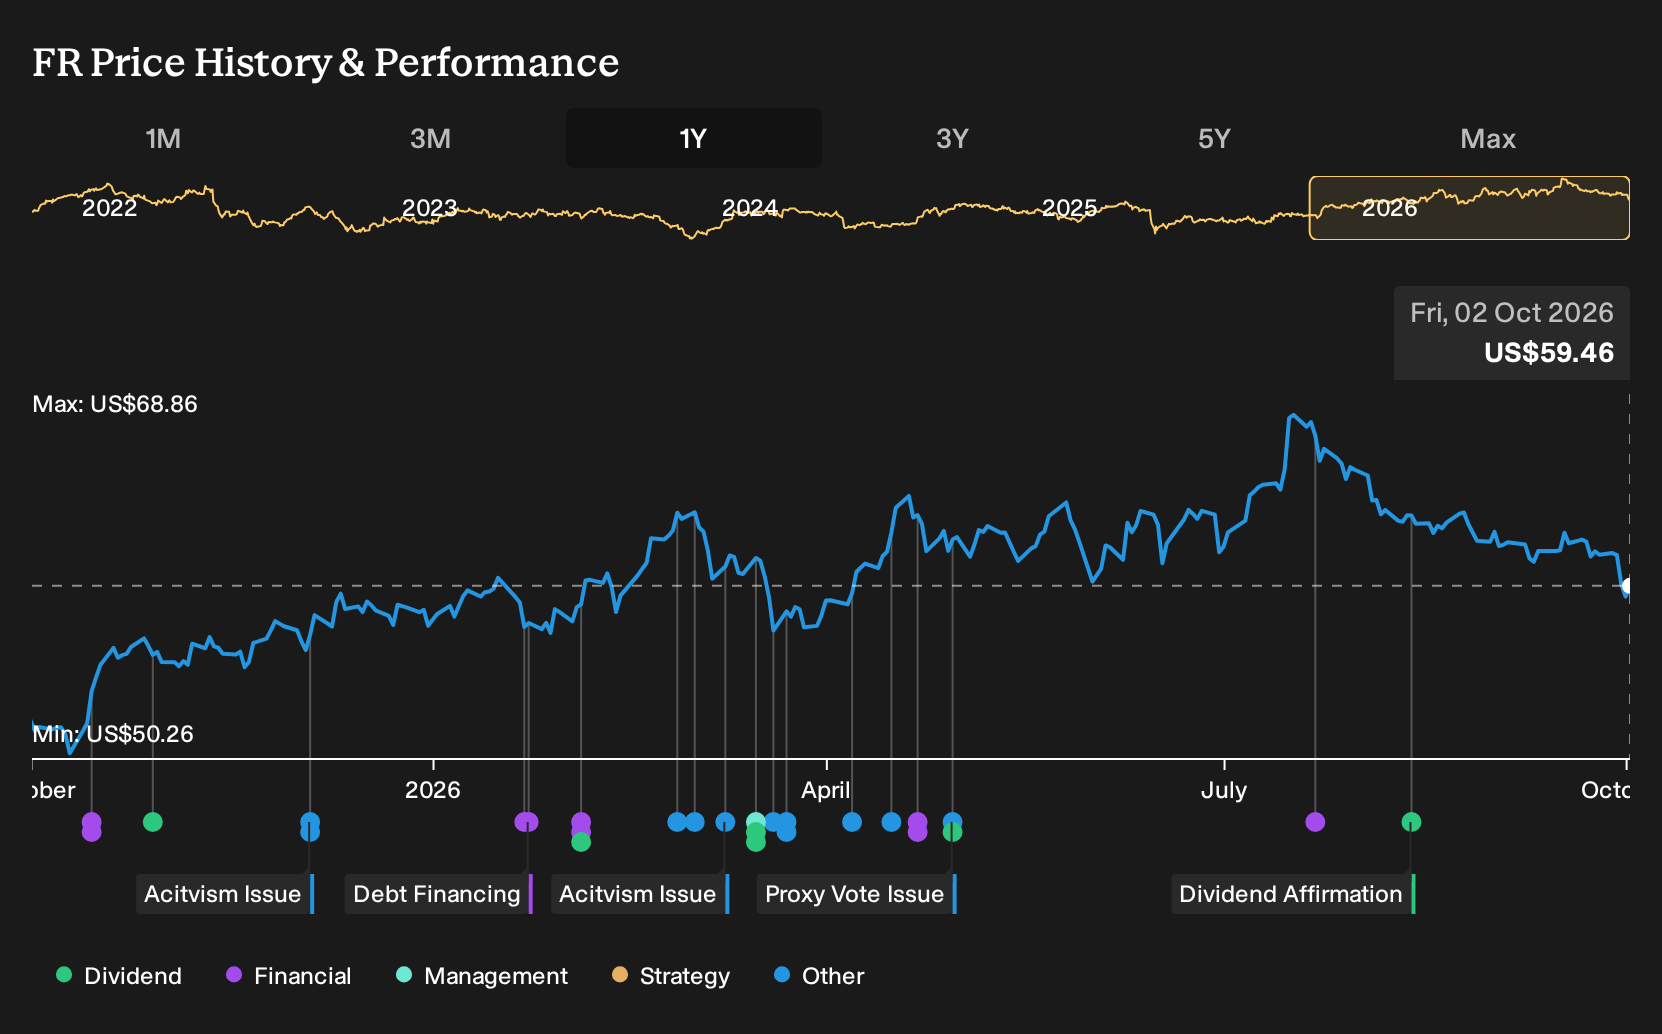
Exploring Other Perspectives
Fair value views on First Industrial Realty Trust from three Simply Wall St Community members run from US$47.88 to US$72.25, a wide span for the same ticker. Those assessments sit alongside real world risks around occupancy, activism costs and land pricing. Use that contrast to pressure test your own expectations and explore more community viewpoints.
Explore 2 other First Industrial Realty Trust fair value estimates, including one that suggests as much as 19% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your First Industrial Realty Trust research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for First Industrial Realty Trust. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate First Industrial Realty Trust's overall financial health at a glance.
Looking for more investment ideas beyond First Industrial Realty Trust?
If the First Industrial Realty Trust story has sharpened your thinking, use that same checklist to hunt for other stocks that better match your risk, income and balance sheet preferences across the market.
- For investors who want potential mispricing on their side, scan through a curated set of companies trading on attractive fundamentals with 31 high quality undervalued stocks that might suit a value driven approach.
- If capital protection and balance sheet strength come first for you, focus your research on businesses with healthier leverage and liquidity profiles using the 31 resilient stocks with low risk scores to filter the field quickly.
- For readers hunting for overlooked opportunities, widen the search to quality companies that receive less attention from the crowd by working through the 19 high quality undiscovered gems and see which ones fit your own thesis.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com