
Free Carbon Allowances Might Change The Case For Investing In Elkem Stock (OB:ELK)
- Elkem ASA received 1.3 million additional free emission allowances for 2021 to 2025 under the EU ETS, aligning its Norwegian silicon operations with allocation levels for comparable EU producers and reducing a prior regulatory cost gap.
- The clarification that Elkem’s Norwegian plants will receive EU-comparable allowances for 2026 to 2030 directly affects future carbon cost visibility, which feeds into planning for energy intensive products such as ferrosilicon and Microsilica.
- We will look at how Elkem’s investment narrative is affected by this clearer EU ETS allowance treatment and the related carbon cost outlook.
Scan list of solid balance sheet and fundamentals (208 results) for other industrials where emissions policy, capex decisions and balance sheet strength could set up the next breakouts alongside Elkem.
Elkem Investment Narrative Recap
To own Elkem, you need to believe in a materials producer that is trying to keep complex assets reliable while dealing with weak end markets and thin margins. The big short term swing factor is still demand and pricing for silicon and ferrosilicon, especially in Europe and China, where past softness has pressured earnings.
The main operational risk remains further volume or price pressure just as interest costs already strain earnings coverage. The clarified EU ETS allowances reduce one cost uncertainty but do not change that demand is the key catalyst, and that any prolonged slump in construction and auto exposure could keep profitability under pressure.
The NOK 260 million furnace renewal at Elkem Rana is the announcement that most directly ties to this story. It matters because the plant already produces around 80,000 tonnes of ferrosilicon and 15,000 tonnes of Microsilica each year, so keeping that capacity safe and stable is central to the Silicon Products division.
With one furnace replaced and the other running as normal during installation, Elkem is trying to secure uptime while tightening dust and process emissions and allowing more biocarbon use. For investors watching catalysts, execution risk around this project, together with how quickly markets absorb these products, will be important to track.
Elkem's current analyst narrative points to NOK 19.2b in revenue and NOK 2.7b in earnings by 2029. That profile relies on the provided assumption of 6.1% yearly revenue growth and an earnings increase of about NOK 2.4b from NOK 278.0m today.
Uncover why Elkem's fair value indicates an 8% potential upside to its current price that could narrow quickly.
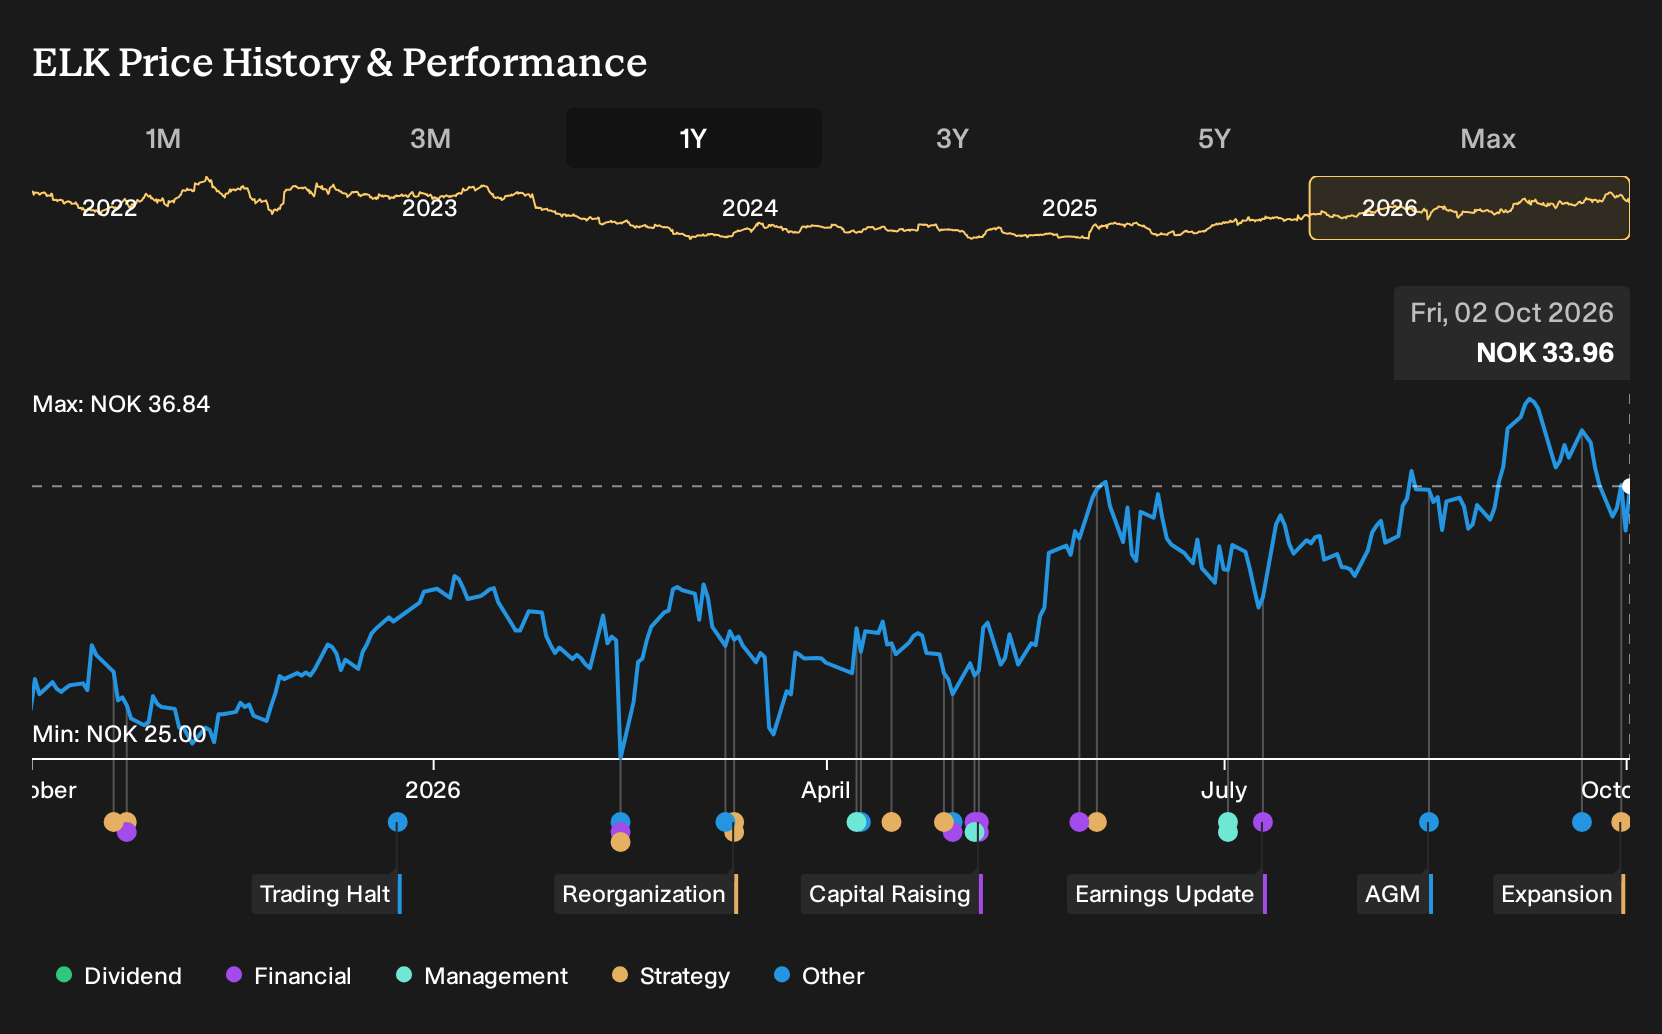
Exploring Other Perspectives
One alternate view on Elkem treats the EU ETS clarification as a possible earnings accelerator. The most optimistic analysts were already pencilling in NOK 22.1b of revenue and NOK 3.3b in earnings by 2029, which is well above the consensus NOK 19.2b and NOK 2.7b. Opinions clearly span a wide range, so it can be useful to test several narratives yourself as this furnace decision and allowance update filter into fresh models.
Explore 3 other Elkem fair value estimates, including one that suggests as much as 195% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Elkem research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Elkem. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Elkem's overall financial health at a glance.
Looking For More Ideas Beyond Elkem?
If you want to stress test your view on Elkem and broaden your watchlist at the same time, the Simply Wall St screener can help you surface other stocks with traits that fit your style, whether you care most about value, resilience, or future potential.
- If your focus is on quality that might be mispriced, scan a curated set of 196 high quality undervalued stocks that combine solid fundamentals with pricing that could appeal to value driven investors.
- If your priority is capital preservation and smoother ride potential, filter for 228 resilient stocks with low risk scores that score well on balance sheet strength and risk metrics.
- If you prefer companies that the market may not be paying close attention to yet, search through 615 high quality undiscovered gems that pair healthy financial profiles with lower visibility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com