
Korean Energy Stocks With Pricing Power as Inflation Pressures Build
Inflation in Korea is flickering back toward 3%, oil prices remain elevated, and rate cuts may stay on hold, which creates a tricky mix for anyone holding local energy or commodity producers. Pricing power can shift quickly when costs and demand move at the same time. This article walks through three stocks from a focused screener that appear positioned for these pressures and explains how the current backdrop affects each one.
The three stocks covered below are only a small sample, as the full screen surfaced 19 more Korean energy and upstream commodity producers with equally detailed stories that are not included here. To identify and analyze the highest conviction ideas for your own portfolio, head straight to the Korean energy and upstream commodity producers screener.
SK Innovation (KOSE:A096770)
SK Innovation is the purest link in this screener between Korea’s refining heavyweights and the inflation story, because its fuel, petrochemical, and lubricant operations sit right where higher oil prices, cost pressure, and pricing power meet for both domestic and global energy markets.
SK Innovation generates most of its revenue from Energy and Chemicals at about ₩160,687,350 million, with smaller contributions from E&S of roughly ₩16,567,367 million and Batteries and Materials of around ₩13,018,986 million, and the group carries a market value near ₩26,114.5 billion.
"The merger of SK On (EV/ESS batteries) and SK Enmove (EV fluids, lubricants, immersion cooling) is expected to create significant business and financial synergies, positioning SK Innovation as a key beneficiary of the global push toward electrification, with EBITDA anticipated to rise by ₩200 billion by 2030, supporting sustained revenue and margin growth."
What really matters now is how one unresolved pressure on future demand and pricing shapes where those margins ultimately settle.
Those future margins hinge on more than one moving part, and the full narrative for SK Innovation shows how SK Innovation’s battery pivot and refining cycle could be decoupling faster than headline numbers suggest.

Korea Petrochemical Ind (KOSE:A006650)
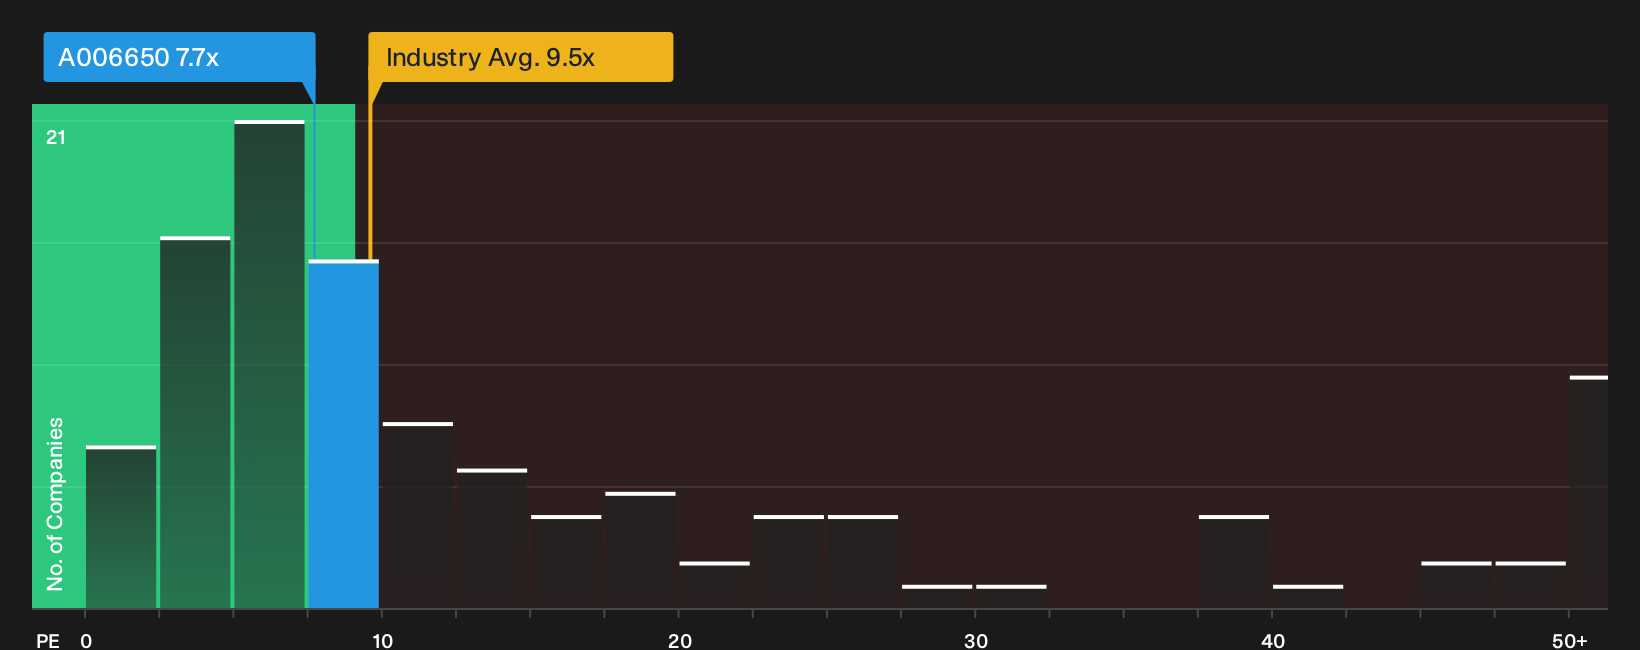
Korea Petrochemical Ind is a pure-play petrochemical producer in the screen’s energy and basic materials bucket, with about ₩2.82b from petrochemical products, roughly ₩748b from the utility segment and smaller salt and industrial gas lines, and a market value near ₩565.1b.
Korea Petrochemical Ind gives you direct exposure to petrochemical pricing at a time when cost-push inflation is feeding through industrial supply chains and oil remains expensive. Earnings screens show low P/E and improving profitability, although recent results reveal how sensitive margins are to feedstock swings if one unseen pressure shifts direction again.
If that unseen pressure worries you, run Korea Petrochemical Ind through the 4 key rewards and 1 important warning sign to see what the market might be mispricing.
POSCO Holdings (KOSE:A005490)
POSCO Holdings plugs this screener straight into basic materials, with integrated steel, trading, construction and green materials all feeding industrial demand. This matters when cost push inflation lifts input prices and stronger players look to pass those costs through.
POSCO Holdings runs an integrated steel and materials platform around its Korean base, with most revenue tied to the Steel segment at about ₩59,912,489 million and the Eco Friendly Infrastructure Trade arm near ₩44,664,483 million. Materials of Secondary Battery contribute roughly ₩3,675,548 million and the group carries a market value close to ₩23,518.1b.
"Expansion into battery materials and lithium, combined with plant ramp-ups, positions POSCO to participate in electric vehicle and renewable energy market trends."
What really moves the needle now is how one unresolved pressure on input costs and steel pricing shapes where POSCO Holdings’ margins land.
That margin question is where things get interesting, and the full narrative for POSCO Holdings maps how POSCO Holdings’ lithium and battery push could be quietly reshaping the risk reward profile.

Seeking Fresh Alternatives Before They Fly
Fresh ideas move first. By the time every chart shows a breakout, early momentum has often gone. Scan curated picks that are under the radar for now and consider them before they become widely noticed.
- Track where institutional money could head next by reviewing carefully filtered 228 resilient stocks with low risk scores that aim to hold up when volatility starts biting.
- Spot potential income workhorses early by scanning a curated set of 170 dividend fortresses before yields drop and the crowd catches on.
- Explore the infrastructure backbone of the AI wave by focusing on hand picked 90 AI infrastructure stocks while the story is still building.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com