
AI Chip Demand Might Change The Case For Investing In ASML (ENXTAM:ASML)
- ASML Holding recently reported strong demand for its extreme ultraviolet lithography platforms, with order books for current and next-generation tools supported by AI chip manufacturing needs and broader semiconductor complexity.
- The monopoly position in EUV systems, combined with customer plans to use High-NA equipment for future chip production, reinforces how crucial ASML’s tools have become for both advanced logic and high-bandwidth memory roadmaps.
- We will examine how ASML Holding’s investment narrative is shaped by this sustained EUV demand connected to AI chip manufacturing.
Scan beyond ASML Holding and identify other chip suppliers participating in the same AI-driven complexity trend with our hand picked 90 AI infrastructure stocks in one place.
ASML Holding Investment Narrative Recap
Owning ASML Holding comes down to believing that chip complexity keeps pushing customers toward its EUV and future High NA tools and that this demand underpins capacity expansion. The recent confirmation of very full EUV order books supports that thesis in the near term and ties directly to the key catalyst, execution on EUV and High NA rollout.
The biggest near term risk still looks operational and geopolitical rather than demand related. Any disruption from tariffs, export controls or delays in moving High NA from R&D into volume production could affect bookings timing and revenue visibility. The latest news does not materially change those risk factors.
The clearest operational takeaway from the latest update is ASML Holding flagging strong EUV demand linked to AI accelerators, along with a roadmap toward meaningful High NA revenue from 2027 capacity. That directly connects to the main catalyst investors watch: how effectively the company converts its monopoly in EUV into a broader High NA production base.
Execution on that High NA transition is not trivial. Customers need mature tools, proven uptime and predictable service. All of these requirements lean on ASML’s installed base management and upgrade capabilities. Any slippage in this ramp or fresh geopolitical restrictions, especially around China, would sit uncomfortably beside the elevated expectations already embedded in the stock.
ASML Holding Analyst Expectations In Context
ASML Holding's narrative projects €65.7b revenue and €25.3b earnings by 2029. This corresponds to 23.0% yearly revenue growth and an earnings increase of about 2.4x from €10.6b today.
Uncover why ASML Holding's fair value indicates a 23% potential upside to its current price, a discount that could close more quickly than many investors expect.
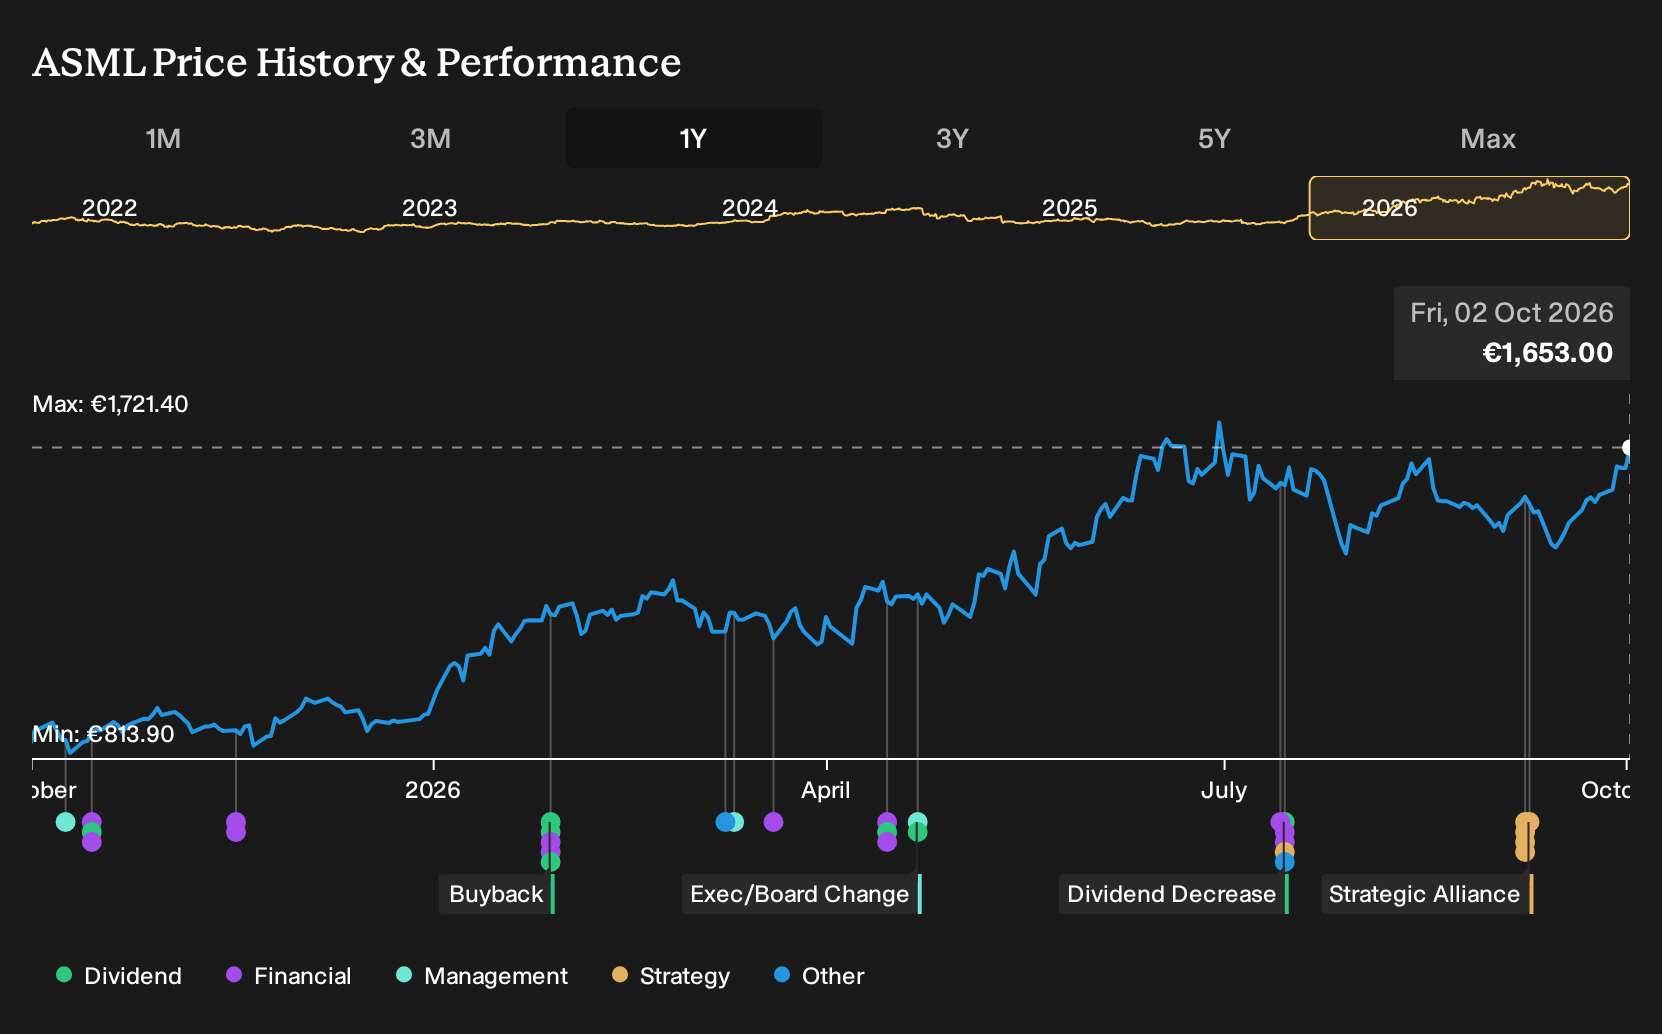
Exploring Other Perspectives
One alternate view on ASML Holding focuses on overcapacity risk. The most cautious analysts were modeling 11.1% annual revenue growth to about €48.4b and earnings of €19.5b by 2029, well below the consensus path. Your takeaway is that opinions already span a wide range, and this fresh AI driven demand update may pull those narratives in new directions.
Explore 25 other ASML Holding fair value estimates, including one that suggests as much as 48% downside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ASML Holding research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ASML Holding. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ASML Holding's overall financial health at a glance.
Looking For More Investment Ideas Beyond ASML Holding?
If ASML Holding has sharpened your focus on where complexity and capital are flowing in chips, it can help to widen the lens and compare it with other businesses that match different risk and return profiles using the Simply Wall St Screener.
- For investors who care most about valuation support, start with a curated group of potentially mispriced opportunities by reviewing 196 high quality undervalued stocks that already clear quality and fundamentals checks.
- If capital preservation is higher on your list, filter for companies where balance sheets and risk scores do more of the heavy lifting through our 228 resilient stocks with low risk scores.
- When you want ideas the market may be overlooking, broaden your watchlist with a 615 high quality undiscovered gems that combines solid fundamentals with lower current visibility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com