
Nvidia Rally Shines A Light On AI Datacenter Hardware Stocks
Nvidia hitting fresh highs, Micron sharing upbeat news, a cooler read on rate hikes and a lift across growth stocks all tell the same story: money is hunting for companies tied to AI infrastructure and datacenter hardware. If you care about where that enthusiasm might flow next, this is one to read. The article reveals three stocks exposed to this news and explains why investors are watching them now.
The stocks highlighted below are just a sample of what investors are watching as AI infrastructure spending pulls more attention toward datacenter hardware suppliers, and the full screen surfaced 98 more large, established companies with equally detailed stories that are not covered here. To see the broader opportunity set and quickly identify, compare and analyze potential high conviction ideas, head straight into the AI Datacenter Hardware and Infrastructure Suppliers screener.
Chroma ATE (TWSE:2360)
Chroma ATE sits close to the AI datacenter build out, since its electronic and power test platforms help validate the chips, power systems and servers that underpin high performance computing. That makes any shift in AI and memory sentiment especially important to this stock.
Chroma ATE designs test instruments and automated systems used to verify semiconductors, power electronics and server gear for AI datacenters, with the Measuring Instruments Business contributing about NT$65.9b and Automatic Equipment around NT$1.5b in revenue, and the group valued near NT$927.7b today.
"Chroma ATE is experiencing substantial order growth in Testing Instruments and Automated Test Systems (ATS), driven by accelerating demand for AI server, data center power applications, and high-performance computing chips. This aligns with the rapid expansion of AI, IoT, and 5G adoption, supporting continued top-line (revenue) growth into 2026 and beyond."
The real swing factor is what happens to profitability if a single pressure point on its high margin testing mix starts to move.
If that profit lever is what really matters, the full narrative for Chroma ATE shows how Chroma ATE’s testing mix, capital intensity and AI exposure could be quietly reshaping risk and upside.

BE Semiconductor Industries (ENXTAM:BESI)
BE Semiconductor Industries sits in the flow of AI datacenter spending, since its assembly tools help package the GPUs, accelerators and high bandwidth memory that power modern servers.
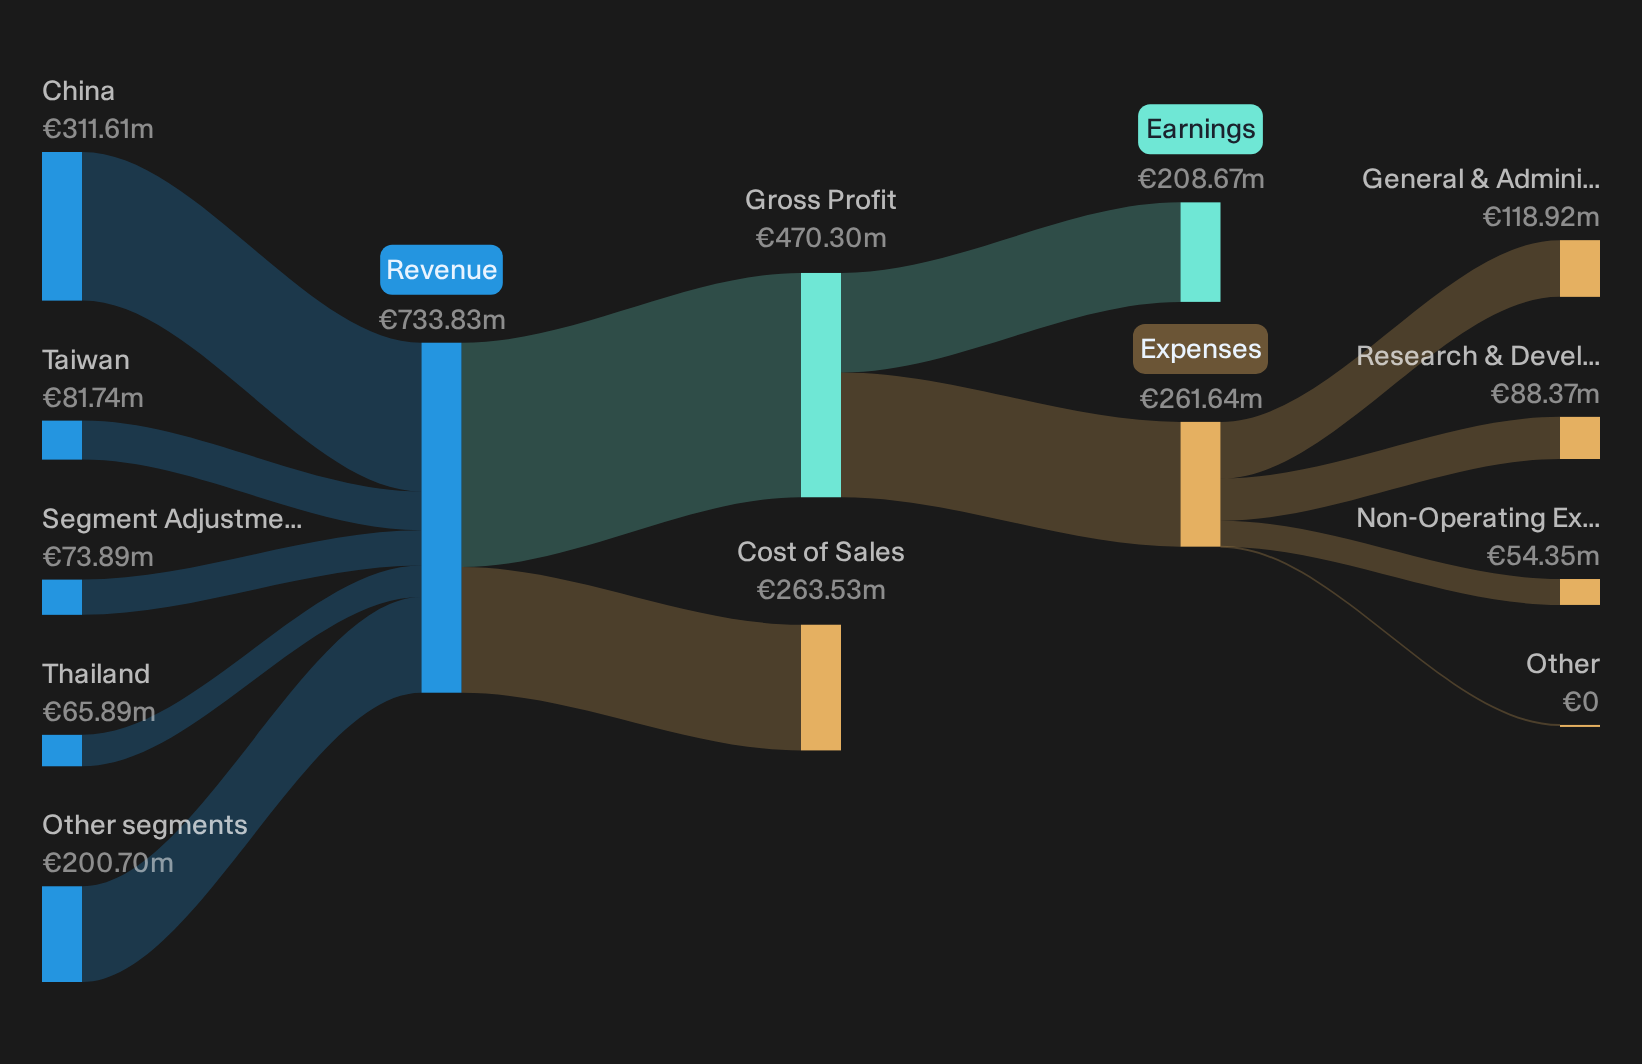
BE Semiconductor Industries generates about €733.83 million from semiconductor equipment and services, supplying die attach, packaging and plating gear that underpins chip production for AI hardware, and the stock is valued around €16.55b today.
For investors following Nvidia’s latest surge, Micron’s upbeat memory signals and a friendlier read on interest rates, BE Semiconductor Industries is one of the behind the scenes suppliers that can feel AI capital spending almost directly on its order book.
"Surging demand for AI packaging and hybrid bonding technologies is positioning BESI to outperform industry expectations and capture significant market share across diversified customers."
What matters most now is how a single shift in future customer appetite for the most complex packaging tools filters through to margins and earnings power.
That margin question is exactly what the full narrative for BE Semiconductor Industries unpacks, showing where BE Semiconductor Industries could keep accelerating and where hidden risks might quietly cap the upside.
ASE Technology Holding (TWSE:3711)
ASE Technology Holding is one of the key behind the scenes players in AI datacenter hardware, packaging and testing GPUs, accelerators and server chips that companies like Nvidia and Micron rely on to get silicon ready for deployment.
ASE Technology Holding runs a broad semiconductor services platform that packages, tests and builds electronics for servers, communications and other devices, with Packaging generating about NT$360.1b, EMS around NT$293.4b, Testing roughly NT$84.6b and a market value near NT$3.1t.
"Investments in leading-edge technologies (3D IC, chiplet, system-in-package, silicon photonics) and aggressive capacity expansion, especially in advanced packaging/test and fully automated lines, position ASE as a key player to meet next-generation requirements, enabling higher-margin mix and long-term operating margin expansion."
What matters is how one pressure point on that high end AI focused packaging capacity ultimately feeds through to pricing power and profitability.
If that pressure point on ASE Technology Holding’s high end capacity is what you are weighing, the full narrative for ASE Technology Holding outlines where AI demand could be accelerating or quietly stalling.

Seeking Alternatives Before Momentum Flies
Fresh opportunities move fast. Breakout themes can gain momentum, prices can start moving sharply, and the cleanest entry points may be taken by others first. Scan these ideas before the edge drops and consider your options promptly.
- Target reliable cash flows and capital discipline by running a focused search through the list of solid balance sheet and fundamentals (208 results) while the strongest balance sheets may still be less widely followed.
- Explore potential pricing power and earnings durability with the 170 dividend fortresses before more yield-focused investors review the same high payout, cash rich businesses.
- Track early trendsetters in automation and efficiency using the curated 90 robotics and automation stocks while the next wave of demand is still taking shape.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com