
British American Tobacco (LSE:BATS) Reaffirms 2026 Outlook, Is It A Bargain?
British American Tobacco (LSE:BATS) reaffirmed its 2026 outlook on 29 September, guiding towards the lower end of 3% to 5% revenue growth at constant currency. That headline anchors the current investment debate.
Recent price action has been softer, with the share price down 14.3% over the past 90 days and 5.3% over the last week. This contrasts with British American Tobacco’s 5 year total shareholder return of 126.6%, which points to a much stronger longer term record.
Look beyond British American Tobacco’s latest guidance and the pressure from UK vape taxes by comparing it with 9 high quality undervalued stocks that also combine cash generation with balance sheet strength.
Bullish investors see British American Tobacco’s share price slide as a chance to buy strong cash flows at a discount, while sceptics worry the lower-end guidance and vape taxes signal a value trap. Which case does the valuation appear to support next?
Most Popular Narrative: 23% Undervalued
On the most followed view, British American Tobacco’s fair value sits at £51.5 against a last close of £39.60. This points to a sizeable valuation gap that investors now have to weigh against softer guidance and regulatory overhangs.
Strong uptake and premiumization of reduced-risk new category products (Modern Oral, Heated, and Vapour), combined with successful innovation rollouts (Velo Plus, glo Hilo, Vuse Ultra), are driving higher contribution margins and gross margins, setting the stage for structural net margin and earnings expansion as these products scale.
See why 193 investors see British American Tobacco as 23% undervalued.
Result: Fair Value of £51.5 (UNDERVALUED)
Still, the risk looms that tougher regulation and higher excise taxes, together with ongoing lawsuits, could compress British American Tobacco’s profitability story more quickly than analysts expect.
Find out about the key risks to this British American Tobacco narrative.
Another View: What British American Tobacco’s P/E Ratio Signals
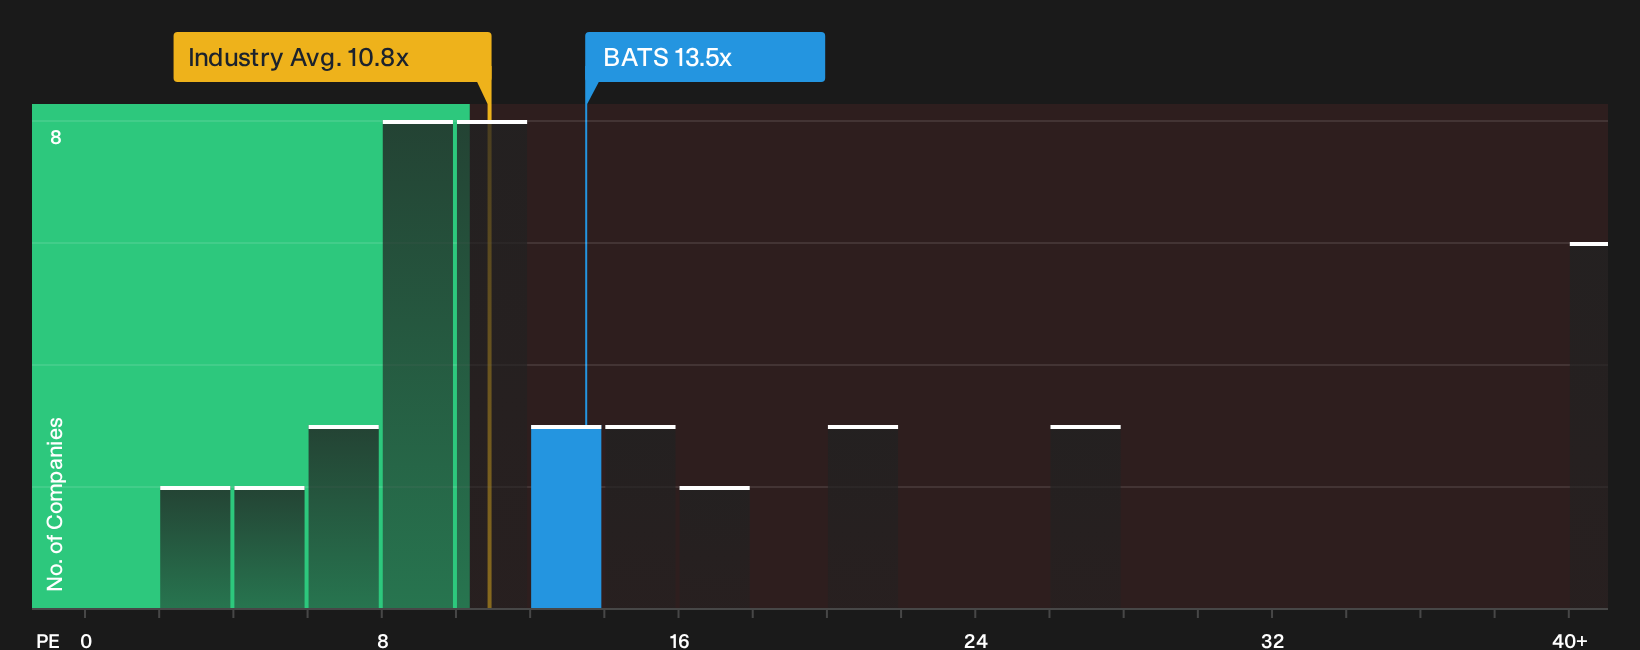
Analysts see British American Tobacco as undervalued on fair value estimates, yet the market is less generous on simple P/E. The shares trade on 13.5x earnings, above the global tobacco average of 10.8x but below the peer group at 17.6x and well under a fair ratio of 24.8x that our models suggest the market could move towards.
That mix of cheaper than peers but richer than the wider sector leaves a clear question: Is the current P/E a sensible middle ground on British American Tobacco, or a mispricing that eventually has to close one way or the other?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on British American Tobacco after all this, or already leaning one way? Move quickly from reading to testing the numbers yourself by weighing its 4 key rewards and 2 important warning signs
Looking for more British American Tobacco investment ideas?
If British American Tobacco has sharpened your focus today, do not stop here. Broaden your watchlist with fresh opportunities that match your goals and risk comfort.
- Target higher income potential by scanning companies built around robust payouts through the 1 dividend fortresses.
- Zero in on resilient balance sheets and steady fundamentals with the list of solid balance sheet and fundamentals (9 results).
- Hunt for future front-runners before the crowd catches on by reviewing 4 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com