
What UMH Properties Shares Activist Board Push Means For Shareholders
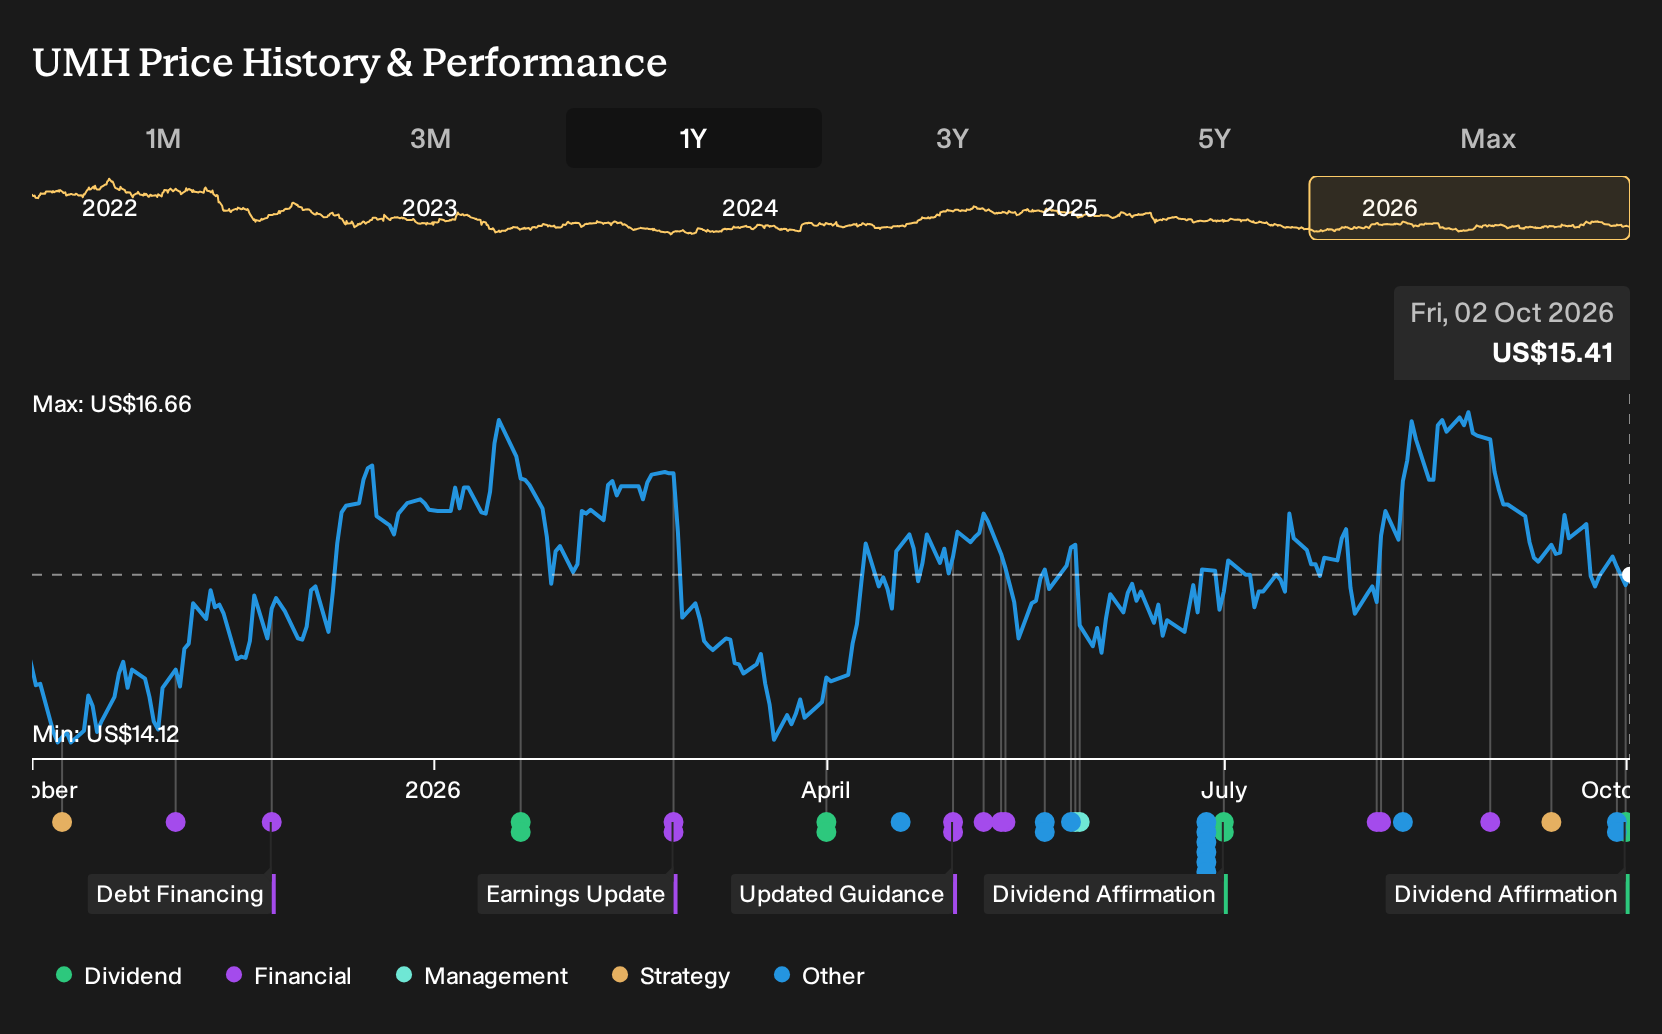
- UMH Properties' board recently declared quarterly dividends on both its common stock and 6.375% Series D preferred shares, confirming scheduled cash payouts to shareholders in December based on November record dates.
- The activist campaign from Erez Asset Management, which is seeking board changes and pushing a public case for change, puts UMH Properties' capital allocation, growth priorities, and governance structure under sharper scrutiny for investors.
- Investors can now monitor how UMH Properties' investment narrative may be influenced by Erez Asset Management's campaign to reshape the board.
Scan beyond UMH Properties' latest dividend and activism headlines to compare it with a hand picked 7 dividend fortresses that also balance income potential with business resilience.
UMH Properties Investment Narrative Recap
To own UMH Properties, an investor needs to believe in the long run demand for affordable manufactured housing and the company’s ability to keep its communities full at solid rental levels. The latest activist pressure and the October dividend decisions do not materially change that core story. The near term swing factor remains how effectively UMH converts its existing sites and recent expansions into higher rental and related income.
The biggest risk still sits on the funding and cost side. UMH relies on external capital and has interest payments and common dividends that are not comfortably covered by current earnings. If borrowing costs stay heavy or home sales margins stay under pressure, that could limit how much benefit investors see from strong occupancy and rental activity.
The most relevant fresh data point is the October 1 dividend declaration on both common and Series D preferred shares. It indicates that management is choosing to maintain cash payouts at existing annual rates, with the common dividend at US$0.90 per share and the preferred Series D at US$1.59375 per share. Those checks are scheduled for December based on November record dates, which locks in a clear near term cash outflow.
For catalysts, that choice matters because it keeps income investors engaged while UMH works to build on the reported 9.3% growth in total rental and related income and 28% gross home sales income increase for the recent period. The trade off is that interest expense is not well covered and the common payout is not fully supported by earnings, so execution on occupancy, rent levels and any future acquisitions needs to stay tight for this approach to remain comfortable.
UMH Properties Analyst Expectations In Focus
UMH Properties' analyst narrative points to forecast revenues of US$330.1 million and projected earnings of US$19.7 million by 2029. That outlook assumes revenue grows by 7.5% each year and earnings rise by about US$10.9 million from US$8.8 million today, with the business needing to support that profile through a higher profit margin and a still elevated P/E multiple compared with many residential REIT peers.
Uncover why UMH Properties' fair value indicates a 26% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
For a contrasting angle, focus on the bearish view that UMH Properties may struggle to improve profitability. The lowest analysts were modeling revenue of about US$333.8 million by 2029 but earnings of only US$7.3 million, well below consensus. Those forecasts came before the dividend affirmation and activism push, so opinions may evolve over time.
Explore 2 other UMH Properties fair value estimates, including one that suggests it could be worth just $18.88!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your UMH Properties research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for UMH Properties. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate UMH Properties' overall financial health at a glance.
Looking For More Ideas Beyond UMH Properties?
Once the UMH Properties story is clear in your mind, it can help to line it up against other companies with different income, value, and risk profiles using the Simply Wall St Screener.
- For investors hunting for higher yield with an eye on durability, start with a curated 7 dividend fortresses that focus on sustaining payouts through different conditions.
- If value is your priority, compare UMH Properties with a 31 high quality undervalued stocks that pair quality fundamentals with prices that sit below internal estimates of worth.
- When capital preservation matters most, filter for a 31 resilient stocks with low risk scores that score strongly on balance sheet strength and earnings stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com