
Mortgage Rates Are Reshaping BlueLinx Stock And U.S. Home Improvement Shares
High mortgage and HELOC costs have frozen many homeowners in place, squeezing big renovation budgets and reshaping where every repair dollar goes. That pressure is creating both stress and potential openings for investors watching U.S. home improvement and building materials retailers. This article unpacks the rate shock, explains how it filters into store aisles, and then walks through three stocks exposed to this news that could be affected in very different ways.
The three stocks covered below are just a sample from this theme, while the full screen surfaced 23 more U.S. home-improvement and building-materials retailers with equally compelling narratives that are not unpacked here. To identify your own highest-conviction angles in this corner of the market, head straight into the U.S. Home-Improvement Big-Box and Building-Materials Retailers screener.
BlueLinx Holdings (BXC)
Overview: BlueLinx Holdings is a U.S. distributor that supplies contractors and dealers with a wide range of building products for renovation and construction.
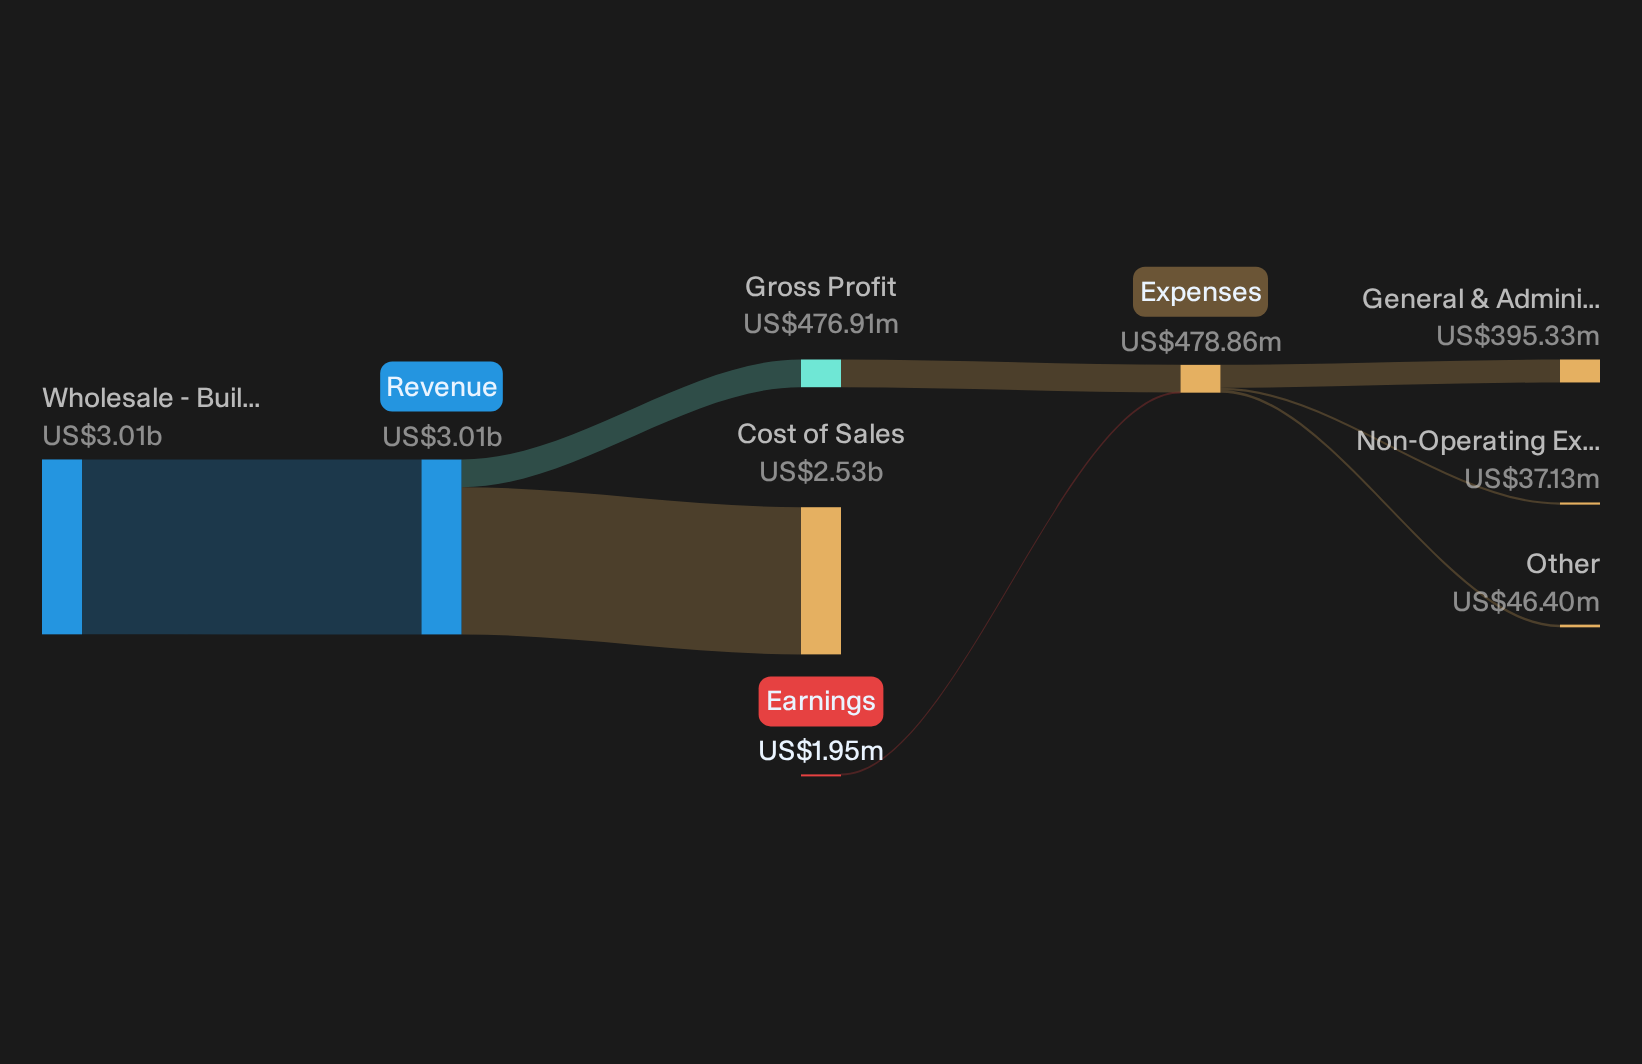
Operations: BlueLinx generates its entire US$3.0b in revenue from wholesale building products within the United States, tightly linked to home-improvement activity.
Market Cap: US$580 million
BlueLinx Holdings matters for this home-improvement and building-materials theme because it sits directly in the flow of lumber, siding, and other supplies that contractors rely on when renovation and construction demand shifts.
"Execution of BlueLinx's demand creation and channel strategy, especially in the multifamily segment where sales are up over 30% YoY, positions the company for outsized volume growth as multifamily construction rebounds to address the ongoing U.S. housing shortage, supporting future revenue and share gains."
What happens if one unseen pressure on pricing and product mix breaks differently than expected could meaningfully shape BlueLinx Holdings’ margin story.
That pricing pressure is exactly what full narrative for BlueLinx Holdings unpacks in detail, highlighting where margin risk could be masking an accelerating volume opportunity.
Boise Cascade (BCC)
Overview: Boise Cascade manufactures engineered wood and distributes building materials across the U.S. and Canada, serving new construction and home repair and remodel projects.
Operations: Boise Cascade generates about US$1.6b from Wood Products and US$6.0b from Building Materials Distribution, after intersegment eliminations.
Market Cap: US$2.6b
Investors tracking home improvement should watch Boise Cascade because it earns most of its money by feeding lumber, panels, siding, and decking into both new builds and renovation channels, including exterior upgrades that are tied directly to retailer aisles. The key variable is how the product mix between higher value engineered wood and broader distribution lines changes if a single key assumption about construction demand shifts.
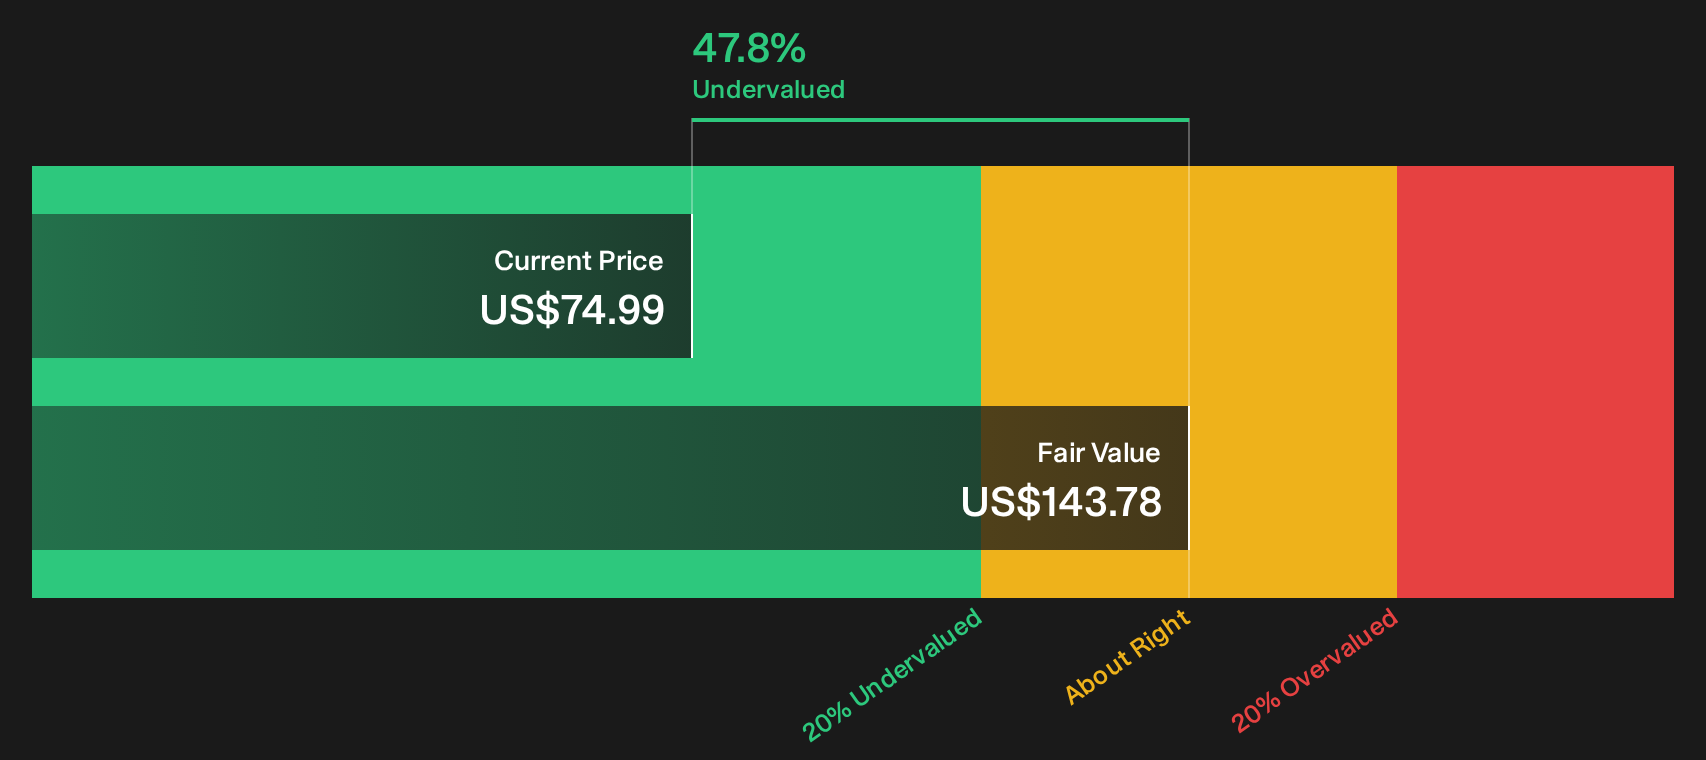
If that mix shift is what you care about most, jump into the DCF valuation analysis for Boise Cascade to see how Boise Cascade’s earnings power could be repriced.
Trex Company (TREX)
Overview: Trex Company manufactures composite decking, railing and related outdoor living products that cater to big-ticket home renovation and backyard upgrade projects.
Operations: Trex Company generates about US$1.2b in revenue from Trex Residential products, almost entirely from customers in the United States.
Market Cap: US$4.4b
Trex Company sits squarely in the home-improvement theme because its composite decking and railing lines depend heavily on how willing homeowners are to commit to larger outdoor projects rather than just patch-and-repair spending.
"The buildout and ramp of the Little Rock facility, designed as Trex's lowest cost and most automated plant with modular lines and advanced recycling technology that can handle dirtier waste streams, is expected to support up to about US$1.8 to US$2.0 billion of core product revenue capacity and can influence future gross margin and EBITDA margin as utilization improves."
What happens if one unseen pressure on outdoor renovation demand or pricing shifts could matter a great deal for Trex Company’s profitability.
That pressure on big-ticket backyard spending is exactly what the full narrative for Trex Company unpacks. It shows where accelerating capacity, pricing power and demand risk could be quietly decoupling for Trex Company.

Seeking Alternatives Before The Crowd?
Fresh themes can move fast, with potential breakouts gaining momentum while they are still under the radar for now. Screen what others might miss while it matters, act now.
- Spot resilient cash generators early and sift through a curated list of solid balance sheet and fundamentals (26 results) before everyone else starts talking about quality balance sheets and durable fundamentals.
- Hunt for under-the-radar yield and scan a hand picked 7 dividend fortresses that could help you keep income flowing even when growth stories cool.
- Zero in on underappreciated growth and comb through a focused 19 high quality undiscovered gems before momentum screens catch up and crowd the best ideas.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com