
Commerce Bancshares (CBSH) Could Be 17% Below Fair Value On Nolan Acquisition
Commerce Bancshares (CBSH) stock is in focus after Commerce Bank completed its acquisition of Nolan & Associates, a St. Louis investment banking boutique that serves middle market business owners.
The acquisition follows a mixed trading period for Commerce Bancshares, with the share price at US$55.28 and short-term returns under pressure. The 30-day share price return declined 4.62%, even though the year-to-date share price return is up 5.82% and the 3-year total shareholder return is 41.35%. This suggests that longer-term holders have still seen meaningful value creation compared with recent softness in momentum.
Compare Commerce Bancshares with a handpicked list of solid balance sheet and fundamentals (26 results) that could handle the same kind of acquisition driven expansion story.
Commerce Bancshares now owns a broader investment banking platform and a long record of shareholder value creation. The real tension is simple. Are you paying a fair price for that combination today, or too much optimism?
Most Popular Narrative: 17% Undervalued
Commerce Bancshares is currently trading at $55.28, while the most followed narrative anchors fair value closer to $66.56 and leans on fee income, wealth and payments strength, and ongoing acquisition integration to close that gap.
Further growth in Commerce Bancshares’ fee-based businesses, which already contribute about 37% of revenue and are led by national payments and a large wealth platform, could add relatively stable, less balance-sheet-sensitive revenue.
Ongoing integration of Nolan & Associates into the broader wealth and advisory offering gives Commerce Bancshares additional ways to monetize its more than $90 billion of trust and wealth assets, which could lift advisory fees and overall non-interest income.
See why 1 investors see Commerce Bancshares as 17% undervalued.
Result: Fair Value of $66.56 (UNDERVALUED)
Still, the Commerce Bancshares story can break if net interest margin pressure lingers or if acquisition related expenses stay high and dilute the fee income thesis.
Find out about the key risks to this Commerce Bancshares narrative.
Another View On Commerce Bancshares Valuation
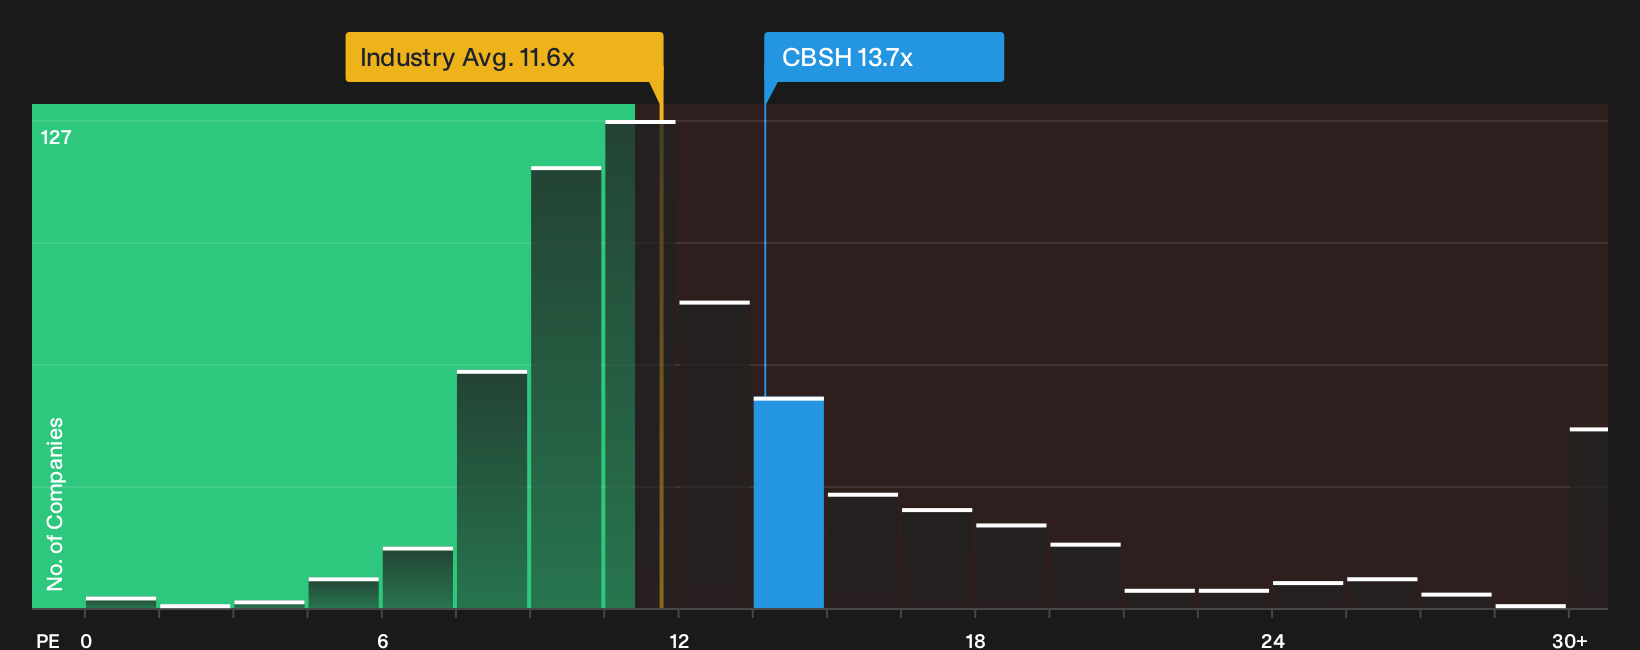
The market prices Commerce Bancshares on a richer P/E than many peers, even while one narrative suggests the stock is 17% below fair value. CBSH trades at 13.7x earnings versus 10.7x for peers and 11.5x for the US Banks industry, while the fair ratio sits at 11.8x. That gap can either be a quality premium investors accept or extra valuation risk if sentiment cools.
To see how those earnings multiples compare with the underlying numbers in more detail, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Commerce Bancshares and its valuation story can pull you in either direction, so move quickly, weigh the data, and then ground your own view in 5 key rewards and 1 important warning sign
Looking for more Commerce Bancshares sized investment ideas?
If Commerce Bancshares has your attention, do not stop here. Use disciplined screeners to uncover fresh ideas that match your risk, income, and value goals.
- Target stronger value opportunities by reviewing companies flagged in the 31 high quality undervalued stocks that align with your preferred quality and pricing mix.
- Strengthen your income stream by checking out yield focused candidates in the 7 dividend fortresses that still show solid financial foundations.
- Dial back overall portfolio risk by scanning the 31 resilient stocks with low risk scores and pinpointing businesses with steadier balance sheets and fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com