
Did Earnings Beat Just Shift Ciena (CIEN) Stock Investment Narrative?
- Ciena recently reported quarterly earnings with EPS of 2.11 for Q3 FY26, which was higher than prior market expectations for the period.
- The stronger profit figure indicates Ciena is managing its cost base and demand environment effectively, which supports analyst upgrades to earnings forecasts.
- We will now explore how Ciena's stronger than expected EPS performance might reshape the existing investment narrative around its AI driven demand.
Scan how other AI infrastructure players are reacting to this kind of earnings momentum by lining up Ciena's surprise against our curated list of 90 AI infrastructure stocks.
Ciena Investment Narrative Recap
Ciena appeals to investors who think AI driven data traffic will keep pushing cloud providers to buy higher capacity optical networks. The near term story hinges on whether those large customers keep spending at the pace implied by the recent demand backdrop. The Q3 FY26 EPS of 2.11 helps your confidence that management is running the cost side tightly while scaling into that demand.
The biggest operational swing factor is still hyperscaler ordering patterns. If those clients slow AI infrastructure rollouts, Ciena’s concentrated revenue base becomes a clear vulnerability. Supply chains and pricing pressure from large service providers remain important watchpoints, but this latest quarter does not materially change those core risks.
Recent commentary around Ciena’s focus on AI and cloud networking over residential broadband is the announcement that ties most directly to this earnings beat. Management has been leaning resources into optical, interconnect and automation where hyperscalers are spending heavily. Strong EPS in Q3 FY26 suggests that this mix shift is, at least for now, pairing higher demand with better profitability.
For you as a shareholder, that decision increases both potential upside and exposure. Earnings and revenue forecasts point to meaningful growth expectations tied to AI capex, yet that same concentration heightens sensitivity to any slowdown in data center builds or pricing pressure from a few large buyers. The key question is whether Ciena can keep converting that focused product roadmap into consistent execution while managing those customer and technology risks.
Ciena's current earnings are about US$654.4 million, with analysts projecting revenue growth of 27.3% per year and consensus earnings of US$2.8b by 2029. That outlook implies an earnings increase of roughly US$2.1b from earnings today, and requires revenues to reach about US$12.4b in the same year.
Uncover why Ciena's fair value indicates a 31% potential upside to its current price before other investors narrow that difference.
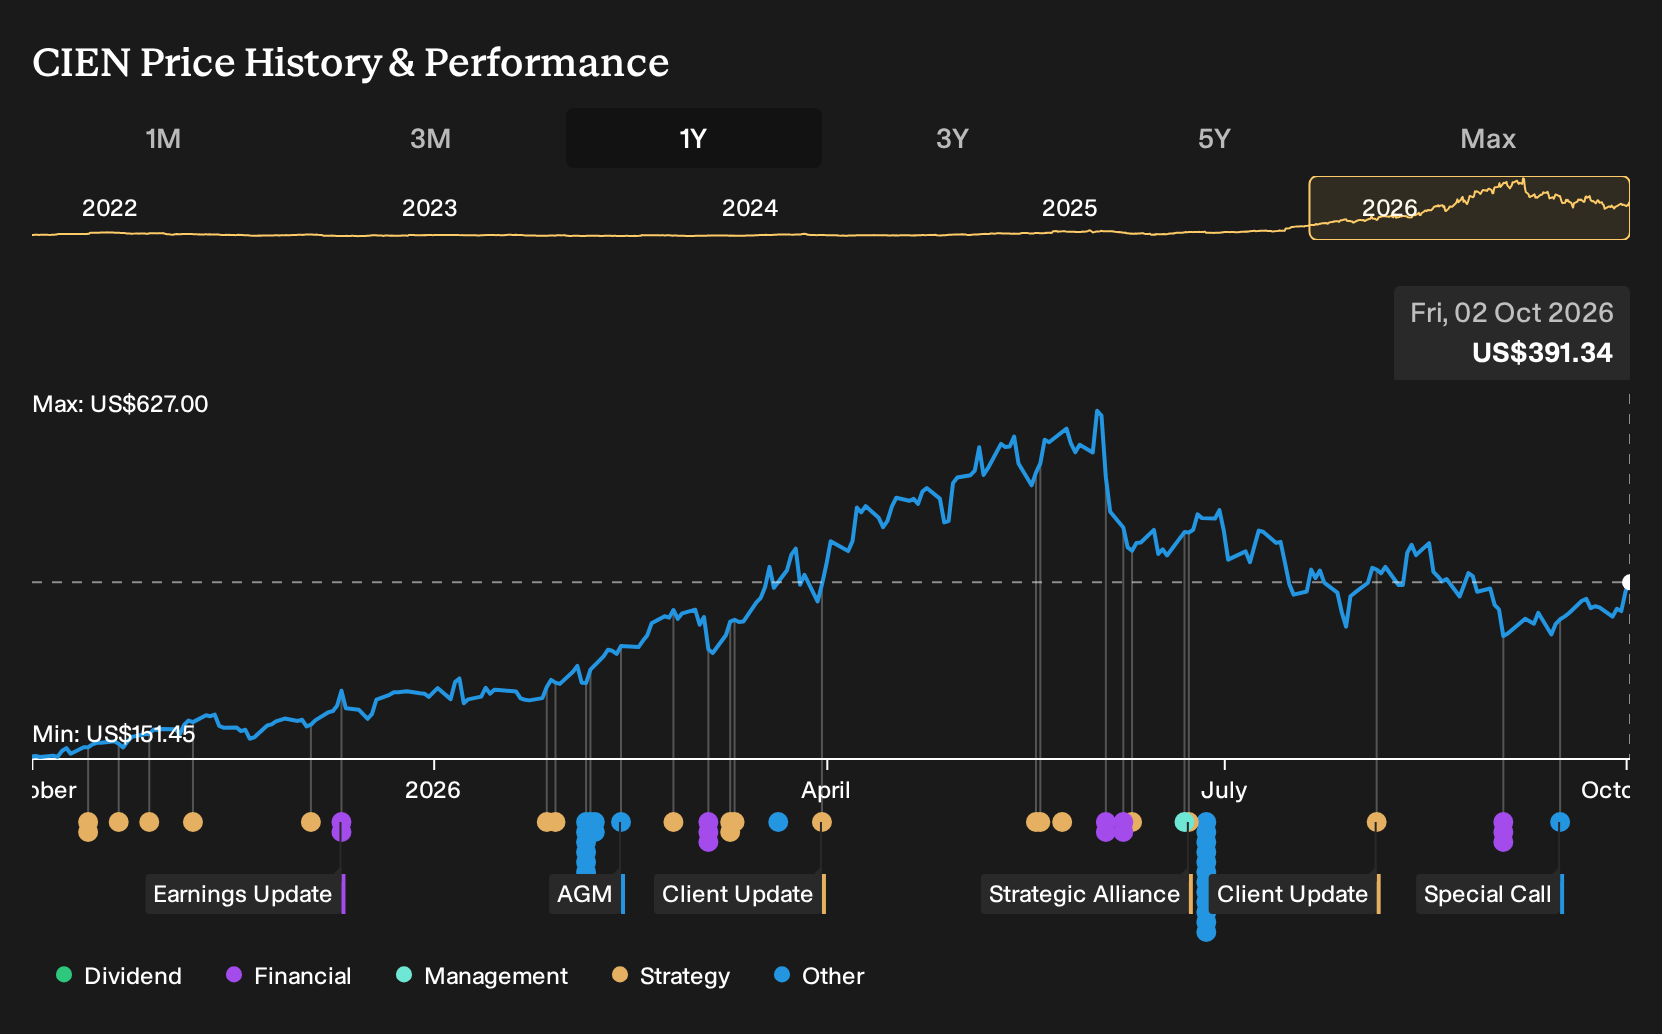
Exploring Other Perspectives
For a very different angle, some of the lowest Ciena forecasts leaned hard into the risk that AI driven spending cools. Those analysts were pencilling in revenue of about US$10.5b and earnings of US$1.6b by 2029, far below the US$2.8b consensus. That more cautious group might revisit those assumptions after this EPS surprise.
Explore 4 other Ciena fair value estimates, including one that suggests as much as 11% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ciena research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Ciena. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ciena's overall financial health at a glance.
Looking for more Ciena style investment ideas?
If the Ciena story has sharpened your view on AI infrastructure, you can apply the same lens to a broader watchlist using the Simply Wall St Screener. Filter for balance sheet strength, income potential or under the radar quality and let the data surface a shortlist that fits your approach rather than the market mood.
- If capital protection is your priority, start with companies that pair resilience with lower risk scores through the 31 resilient stocks with low risk scores.
- For investors focused on quality at reasonable prices, you can shortlist potential bargains by running your filters over the 31 high quality undervalued stocks.
- Those looking for growth stories the crowd has not fully focused on yet can scan the 19 high quality undiscovered gems and build a fresh set of ideas.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com