
Aramark (ARMK) Could Be 19% Undervalued After Arena Fan Experience Upgrades
Aramark (ARMK) is back in focus after its Sports + Entertainment unit outlined a broad refresh of fan experiences across seven arenas, from chef residencies to premium hospitality upgrades.
That arena refresh comes during a strong run for Aramark, with the share price up 51.86% year to date and a 1-year total shareholder return of 43.95%. The recent 30-day share price slip of 2.06% suggests momentum has cooled slightly after a powerful multi-year total shareholder return of 133.47% over three years and 122.79% over five years.
Spot opportunities riding similar consumer and hospitality trends as Aramark by scanning a curated 19 high quality undiscovered gems that could be flying under most investors' radar.Aramark now trades at US$55.55 with analyst targets clustered around US$68.50 and an internal fair value estimate implying a different story. Which signal deserves more weight as you think about valuation next?
Most Popular Narrative: 19% Undervalued
Against the latest close at $55.55, the most followed narrative anchors Aramark’s fair value at $68.50, which leans toward a material upside when that view is discounted back at 9.49%.
The launch and ramp of Nexus, with three AI data center hospitality sites expected to contribute roughly US$400m to US$500m of annualized revenue in fiscal 2027 and 2028 at above company margins and low capital intensity, points to a new earnings stream that can support both margin expansion and free cash flow.
See why 3 investors see Aramark as 19% undervalued.
Result: Fair Value of $68.50 (UNDERVALUED)
Still, a low free cash flow margin and ongoing reputational questions around correctional food service could easily weaken the bullish Aramark story if those issues intensify.
Find out about the key risks to this Aramark narrative.
Another View: Aramark On Simple Market Ratios
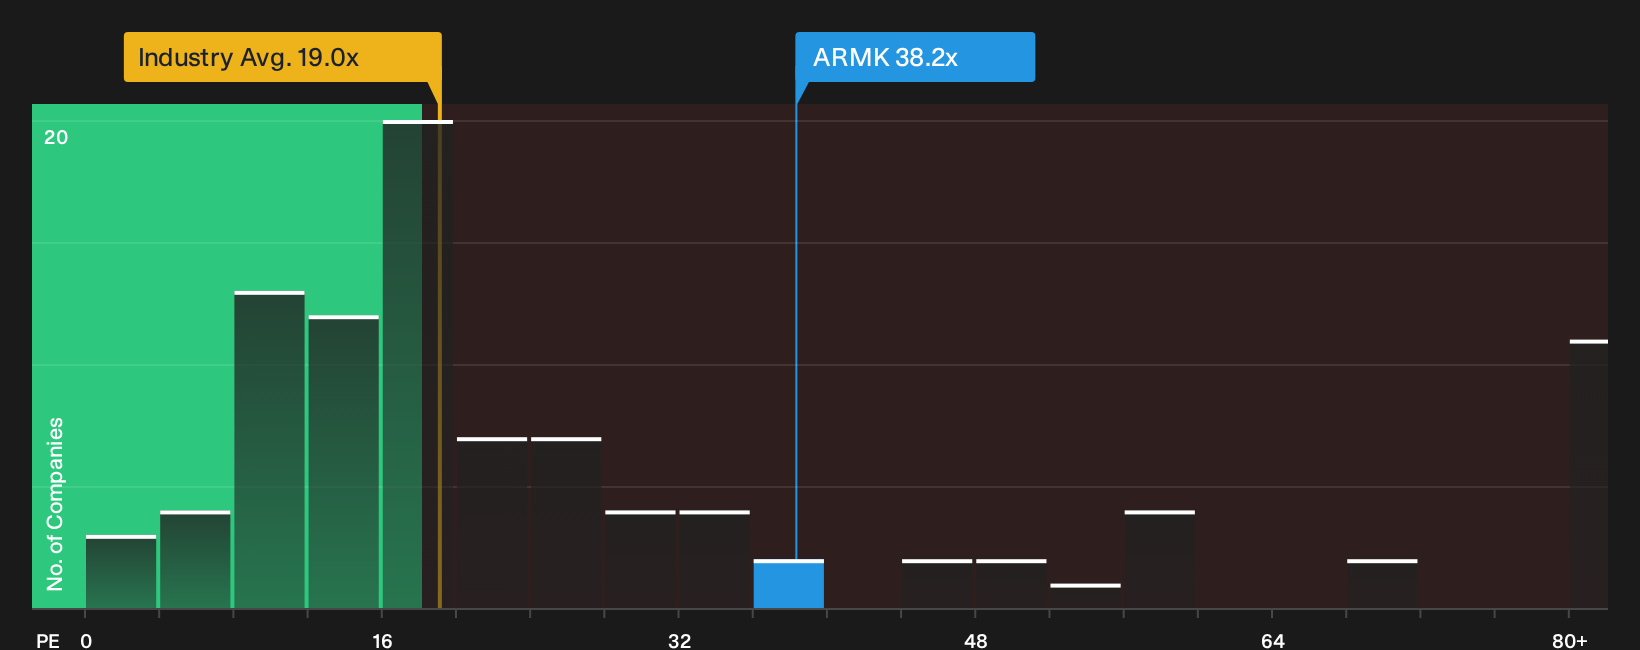
The story looks different once you leave narratives and price targets aside and just compare Aramark’s current P/E with simple benchmarks. At 38.2x, the stock trades at roughly double both the US Hospitality industry on 19x and its own fair ratio of 24.9x, which points to meaningful valuation risk if sentiment cools.
That kind of gap gives you a cleaner yardstick. It shows how much optimism is already baked into the price and how far the market could move if expectations reset toward that fair ratio, so which signal do you trust when you weigh the upside case against the risk of multiple compression next.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the optimism around Aramark outweighs the concerns? Review the data, pressure test both sides, and ground your own stance with 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Aramark?
Do not stop your research with one hospitality stock. Use the Simply Wall St screener to surface other opportunities that fit the kind of portfolio you actually want to build.
- Target resilient candidates that aim to keep downside contained by scanning a focused list of 31 resilient stocks with low risk scores aligned with more cautious investing styles.
- Hunt for future compounders by filtering through 31 high quality undervalued stocks where strong fundamentals and pricing leave room for potential upside.
- Strengthen long term foundations by reviewing a curated list of solid balance sheet and fundamentals (26 results) that focuses on financial resilience when conditions get tougher.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com