
Wallenius Wilhelmsen (OB:WAWI) Leaves OBX Index, Is The Stock Fully Priced?
Wallenius Wilhelmsen (OB:WAWI) has been removed from the Oslo OBX Total Return Index, a shift that can prompt forced trading by index-tracking funds and influence short term liquidity.
That index exit comes after a strong run in Wallenius Wilhelmsen’s shares. The NOK184.2 price reflects a 90 day share price return of 35.84% and an 83.28% year to date gain, while the 1 year total shareholder return of 128.05% points to powerful longer term momentum that recent index related selling pressure may test but has not yet reversed.
Scan how Wallenius Wilhelmsen’s index exit compares with other freight and logistics plays that are showing strong flows using our curated list of 615 high quality undiscovered gems.
Wallenius Wilhelmsen now trades above the average analyst target, yet below some implied fair value estimates. Where does a realistic valuation range actually fall after this index exit and sharp price move?
Most Popular Narrative: 17% Overvalued
The most followed narrative places Wallenius Wilhelmsen’s fair value at NOK156.83, which sits well below the NOK184.2 last close and frames the post index-exit surge as stretched relative to that anchor.
The accelerating rise of electric vehicle adoption, especially from Chinese OEMs, and the increasing localization of EV production (as Western OEMs lose competitiveness and shift to local/continental builds) may structurally reduce trans-oceanic shipping volumes, hindering long-term revenue and vessel utilization. Significant new vessel deliveries are coming online industry-wide (close to 40 delivered this year with more to come), raising the risk of overcapacity, which could put sustained pressure on shipping rates and compress industry-wide margins, even if Wallenius Wilhelmsen's contracts provide some temporary protection.
See why 53 investors see Wallenius Wilhelmsen as 17% overvalued.
Result: Fair Value of NOK156.83 (OVERVALUED)
Still, if Wallenius Wilhelmsen’s Asian export exposure stays resilient and long term contracts keep vessels filled, that bearish overcapacity story could lose traction.
Find out about the key risks to this Wallenius Wilhelmsen narrative.
Another View On Wallenius Wilhelmsen’s Valuation
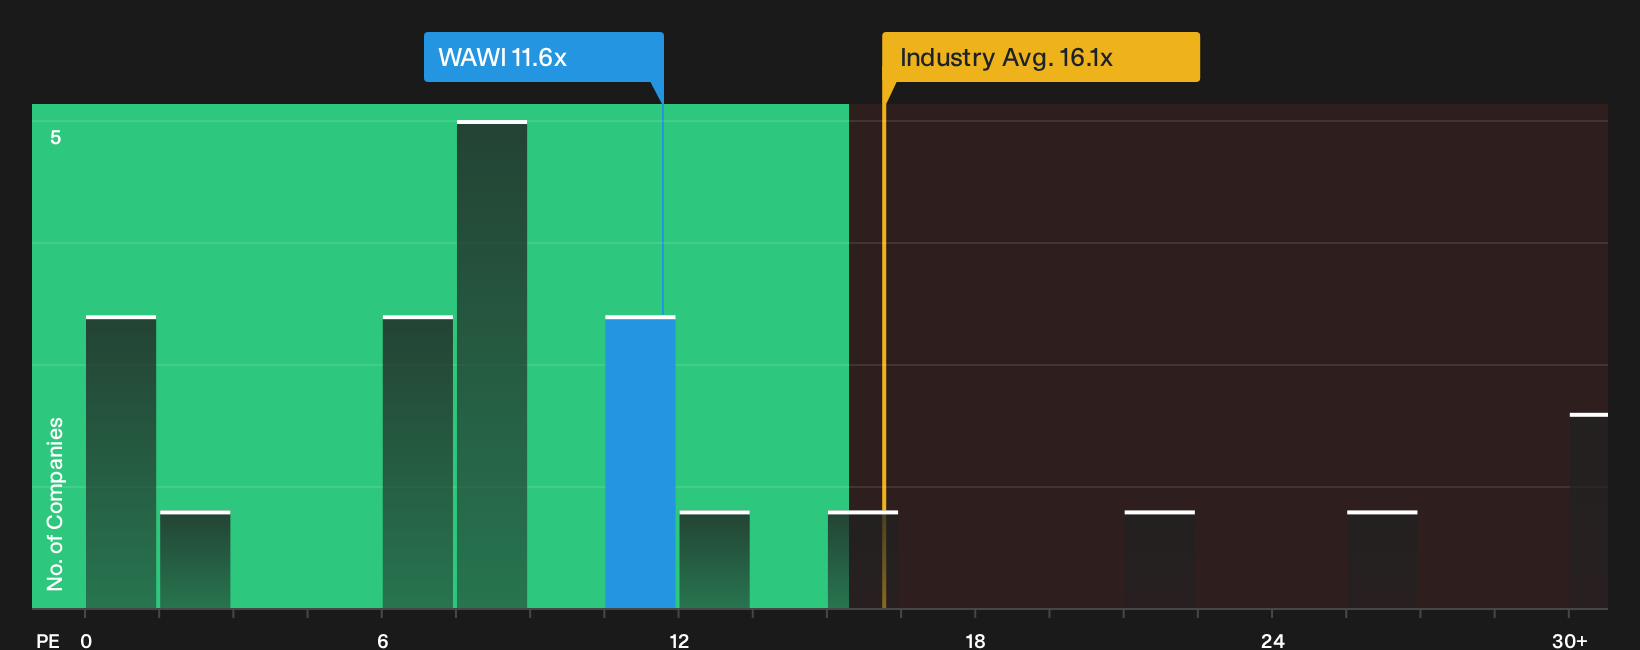
Analysts see Wallenius Wilhelmsen as 17.5% overvalued versus their NOK156.83 fair value. The current P/E of 11.6x is below the European shipping average of 15.8x and above a fair ratio of 9x, which points to richer pricing and raises the question of how much optimism is already baked in.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted about whether the recent enthusiasm around Wallenius Wilhelmsen is justified or stretched? Move fast, review both sides of the story, then weigh the 1 key reward and 3 important warning signs.
Looking for more ideas beyond Wallenius Wilhelmsen?
If Wallenius Wilhelmsen has sharpened your focus on pricing, risk and quality, broaden your watchlist now so you do not overlook other potential standouts.
- Target stronger value by scanning companies that combine quality fundamentals with discounted pricing through the 195 high quality undervalued stocks.
- Prioritise resilience by reviewing the 227 resilient stocks with low risk scores and see which businesses score well on financial strength and risk metrics.
- Reinforce income potential by using the 169 dividend fortresses to spot higher yielding payers that still show solid underlying numbers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com