
Is Seagate Technology Holdings (STX) A Bargain After Toshiba’s HDD Expansion Plan?
Toshiba’s plan to double hard disk drive output by fiscal 2027 and target a 30% market share has pushed Seagate Technology Holdings (STX) into focus as investors reassess competition and pricing power.
The share price reaction has been sharp, with Seagate Technology Holdings falling around 10% in the last day and down about 7% over the week, even though the 1-year total shareholder return sits above 200% and the 5-year figure is above 10x. This suggests powerful long term momentum that is now colliding with fresh concerns about future HDD pricing power.
Scan how the Toshiba shock ripples across AI storage and price expectations by reviewing the hand picked 90 AI infrastructure stocks alongside Seagate Technology Holdings.
After a one day drop of around 10%, Seagate Technology Holdings now trades well below both analyst targets and some intrinsic value estimates. Is that discount a cushion or a warning as the valuation work starts?
Most Popular Narrative: 27% Undervalued
Against a last close of $848.99, the leading narrative on Seagate Technology Holdings points to a fair value of $1,158.73, framing the latest pullback as a clash between Toshiba driven supply fears and an already bullish long term thesis.
Seagate is the storage-capacity position in a portfolio built on physical scarcity, and it is the one I would defend furthest into a downturn.
Not because the shortage is more durable than the others; it may or may not be. It is because Seagate is the only one of my three storage holdings with a margin lever that runs independently of the pricing cycle. HAMR penetration going from 40% to 70% happens on a qualification schedule, not a price schedule. That is a real asset in a portfolio otherwise dependent on shortages persisting.
See why 6 investors see Seagate Technology Holdings as 27% undervalued.
Result: Fair Value of $1,158.73 (UNDERVALUED)
Still, Seagate Technology Holdings faces real pressure if Western Digital closes the HAMR gap faster than expected or if either supplier loosens capacity discipline.
Find out about the key risks to this Seagate Technology Holdings narrative.
Another View: Seagate Technology Holdings Through The P/E Lens
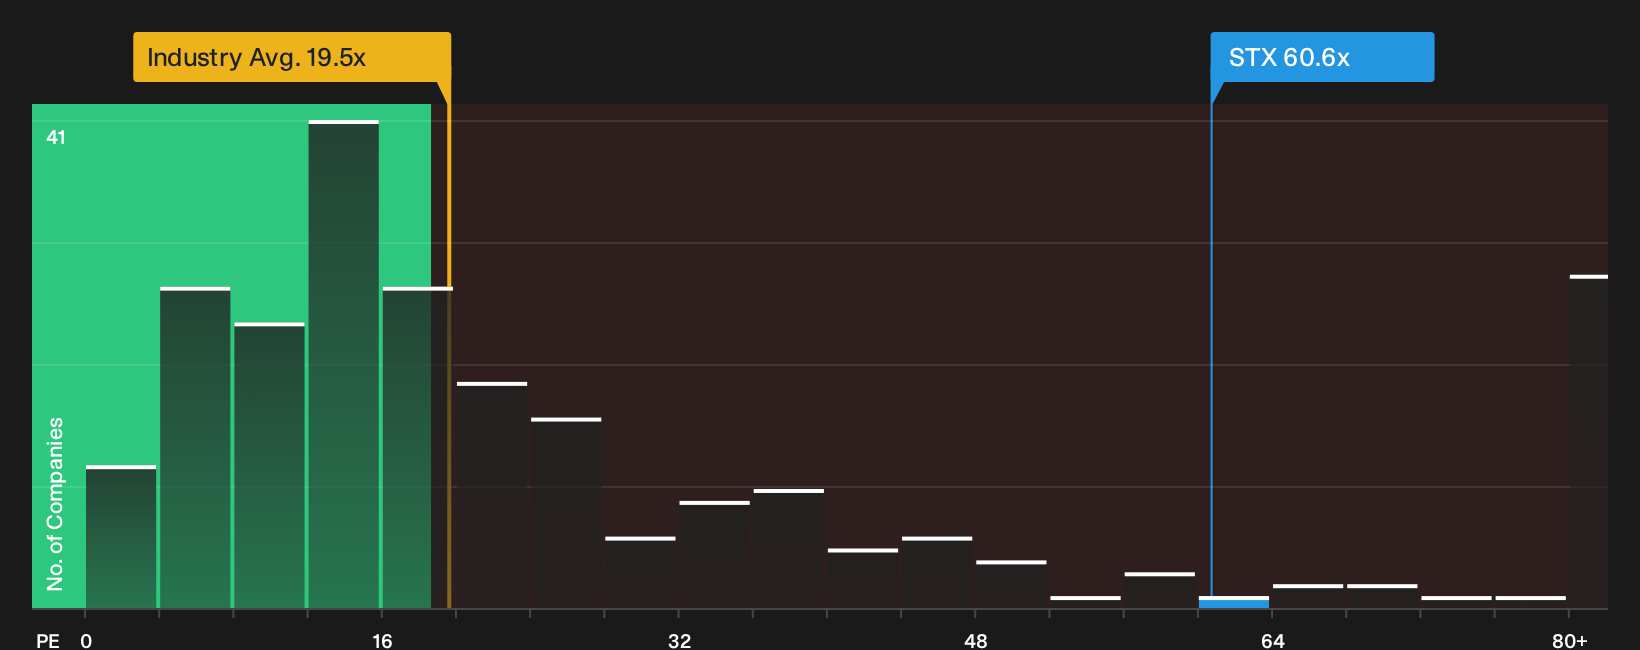
Our fair value estimate near $1,158 suggests Seagate Technology Holdings could be undervalued, yet the current P/E of 60.6x tells a very different story. That multiple sits above peers at 26x, the global tech average of 19.5x, and even a fair ratio of 57.5x. Is that premium a cushion or a risk if sentiment cools?
See what the numbers say about this price in our valuation breakdown, starting with the See what the numbers say about this price — find out in our valuation breakdown..
To put Seagate Technology Holdings' valuation gap against its sector in context, review the latest P/E comparison in
Next Steps
Mixed messages in the Seagate Technology Holdings story so far. Act while the data is fresh, consider both the risks and the potential rewards, and see the 3 key rewards and 3 important warning signs.
Ready For More Seagate Technology Holdings Investment Ideas?
If Seagate Technology Holdings has sharpened your focus on pricing power and risk, do not stop here. Broaden your watchlist now or risk missing sharper opportunities.
- Target potential mispricings by scanning the 31 high quality undervalued stocks that pair resilient cash flows with disciplined balance sheets.
- Strengthen income potential by reviewing the 7 dividend fortresses that combine higher yields with a focus on resilience.
- Dial down portfolio stress by filtering for the 31 resilient stocks with low risk scores that score well on stability and financial health.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com