
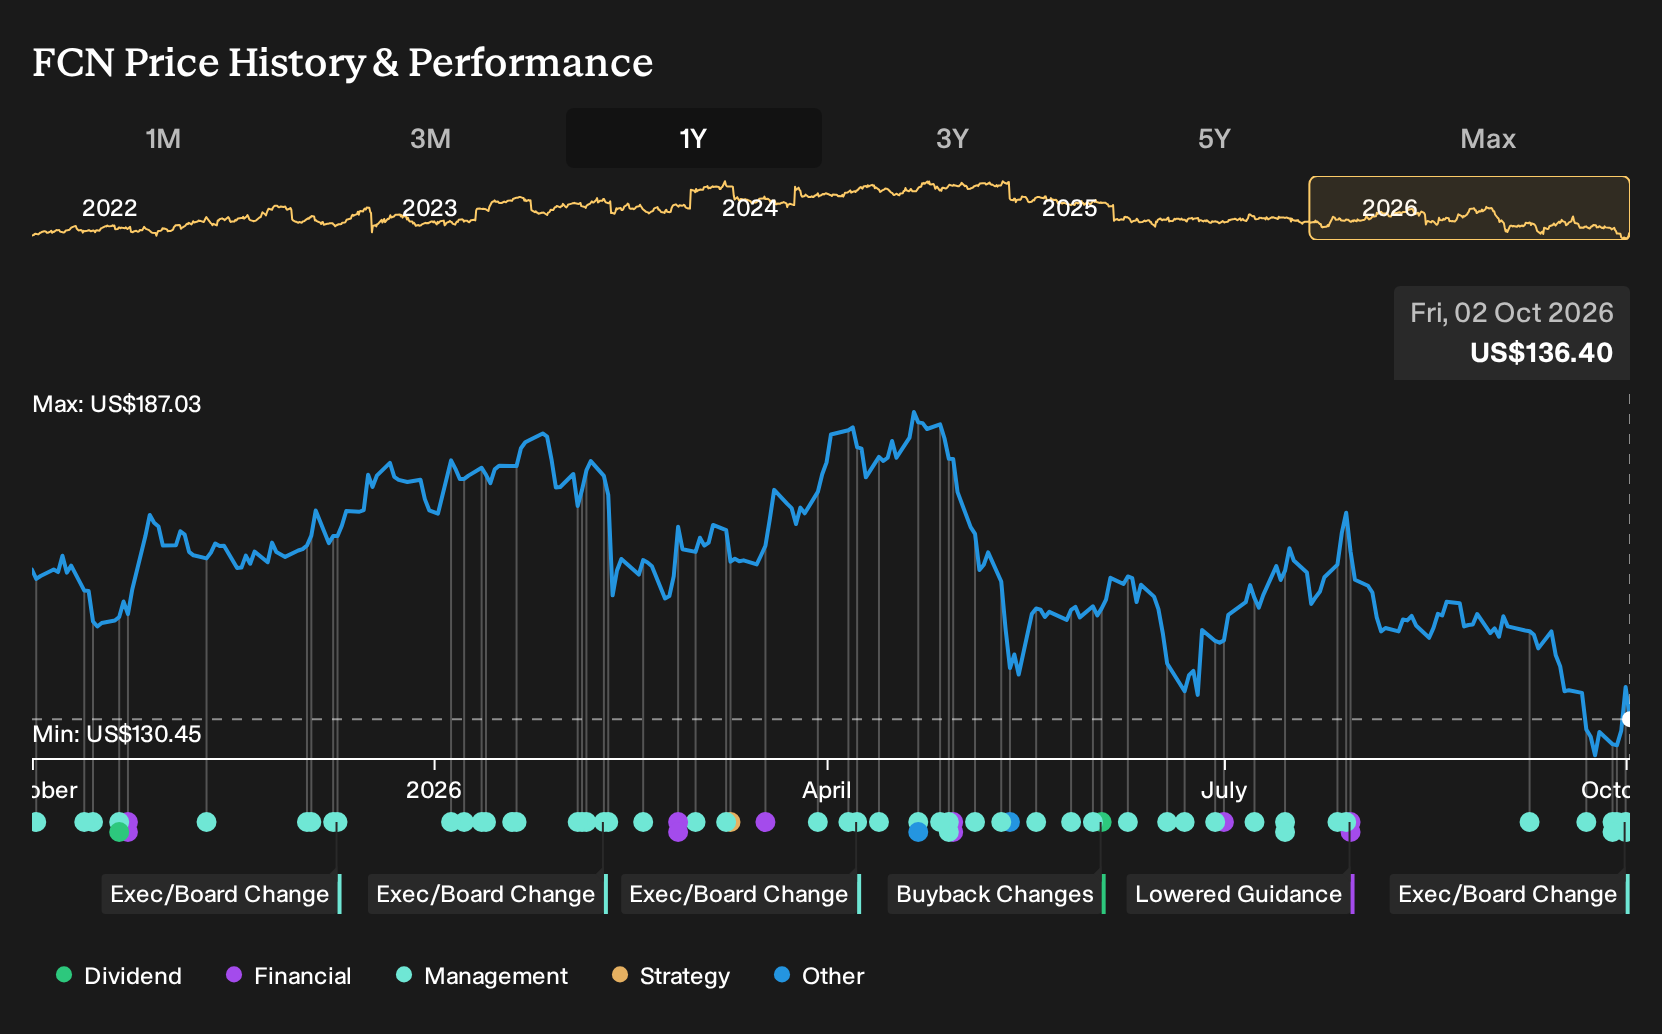
Did Senior Hires Just Shift FTI Consulting's (FCN) Investment Narrative?
- FTI Consulting announced a series of senior hires across healthcare risk, private equity tax, restructuring, investigations and energy advisory, with seasoned leaders joining key practices in the United States, UK, Italy and Mexico to work on complex mandates for global clients.
- These appointments concentrate experience in AI enabled process redesign, cross border restructurings, financial crime, energy transition and tax structuring, which directly affects how FTI Consulting can price complex work, win multi region engagements and support fee based revenue from higher value advisory projects.
- This article examines how FTI Consulting's investment narrative is influenced by this wave of senior hires focused on complex mandates.
Scan other consulting and advisory stocks that could benefit from similar high-complexity mandates by reviewing our hand picked list of solid balance sheet and fundamentals (26 results) alongside FTI Consulting’s latest senior hires story.
FTI Consulting Investment Narrative Recap
To own FTI Consulting, you need to believe that complex cross border disputes, restructurings and regulatory problems will keep requiring high end human expertise, even as AI tools spread. The near term swing factor remains execution on large, multi year mandates while keeping utilization and pricing healthy across Corporate Finance, Forensic and Technology.
The biggest risk still sits in segments and cost lines that are already under pressure. Economic Consulting has weighed on profitability, and elevated legal and SG&A expenses have limited margin progression. This cluster of senior hires is helpful signaling, but by itself does not materially change those core near term risks.
The most relevant update here is the hire of Christina Morris into Healthcare Risk Management & Advisory. Her track record in applying AI, automation and process orchestration lines up directly with one of FTI Consulting’s key catalysts, which is using digital tools and specialist talent to push work toward higher bill rates and more complex mandates.
For you as an investor, this kind of appointment matters if it feeds into more technology driven compliance and risk projects in healthcare and life sciences, where data, regulation and reputational stakes are high. The potential upside depends on these projects scaling faster than any drag from Economic Consulting or persistent legal and overhead costs.
What The Analyst Framework Implies For FTI Consulting
FTI Consulting's narrative ties directly into what analysts are penciling in over the next few years. Their models lean on moderate top line expansion, some margin lift and a higher contribution from complex work that fits exactly with these fresh senior hires.
Those assumptions translate into more than just a bigger fee pool. They inform how much headroom investors might see for reinvestment, buybacks or simply absorbing higher compensation and legal costs if those remain sticky.
FTI Consulting's narrative projects US$4.7b revenue and US$372.5m earnings by 2029. This is built on 6.1% yearly revenue growth and an earnings increase of about US$119.7m from US$252.8m today.
Uncover how FTI Consulting's fair value indicates a 29% potential upside to its current price before the discount closes.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your FTI Consulting research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for FTI Consulting. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate FTI Consulting's overall financial health at a glance.
Looking For More FTI Consulting Style Ideas?
If the FTI Consulting story has you thinking about where else complex, high value work might support durable fee income, the Simply Wall St screener can help you widen the field without losing discipline on quality.
- If you want businesses that already pair strong balance sheets with sound fundamentals, start by reviewing our hand picked list of solid balance sheet and fundamentals (26 results) that may benefit when clients seek out financially resilient advisers for complex work.
- If your focus is on quality at a sensible entry point, broaden your watchlist with the 31 high quality undervalued stocks and see which other consulting or professional services stocks might offer a similar risk reward profile.
- If stability and income matter most to your plan, line up potential holdings using the 7 dividend fortresses and compare those cash returns with what you expect from a specialist advisor like FTI Consulting.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com