
Is Five Year Union Deal Altering The Investment Case For Canadian Pacific Kansas City Stock?
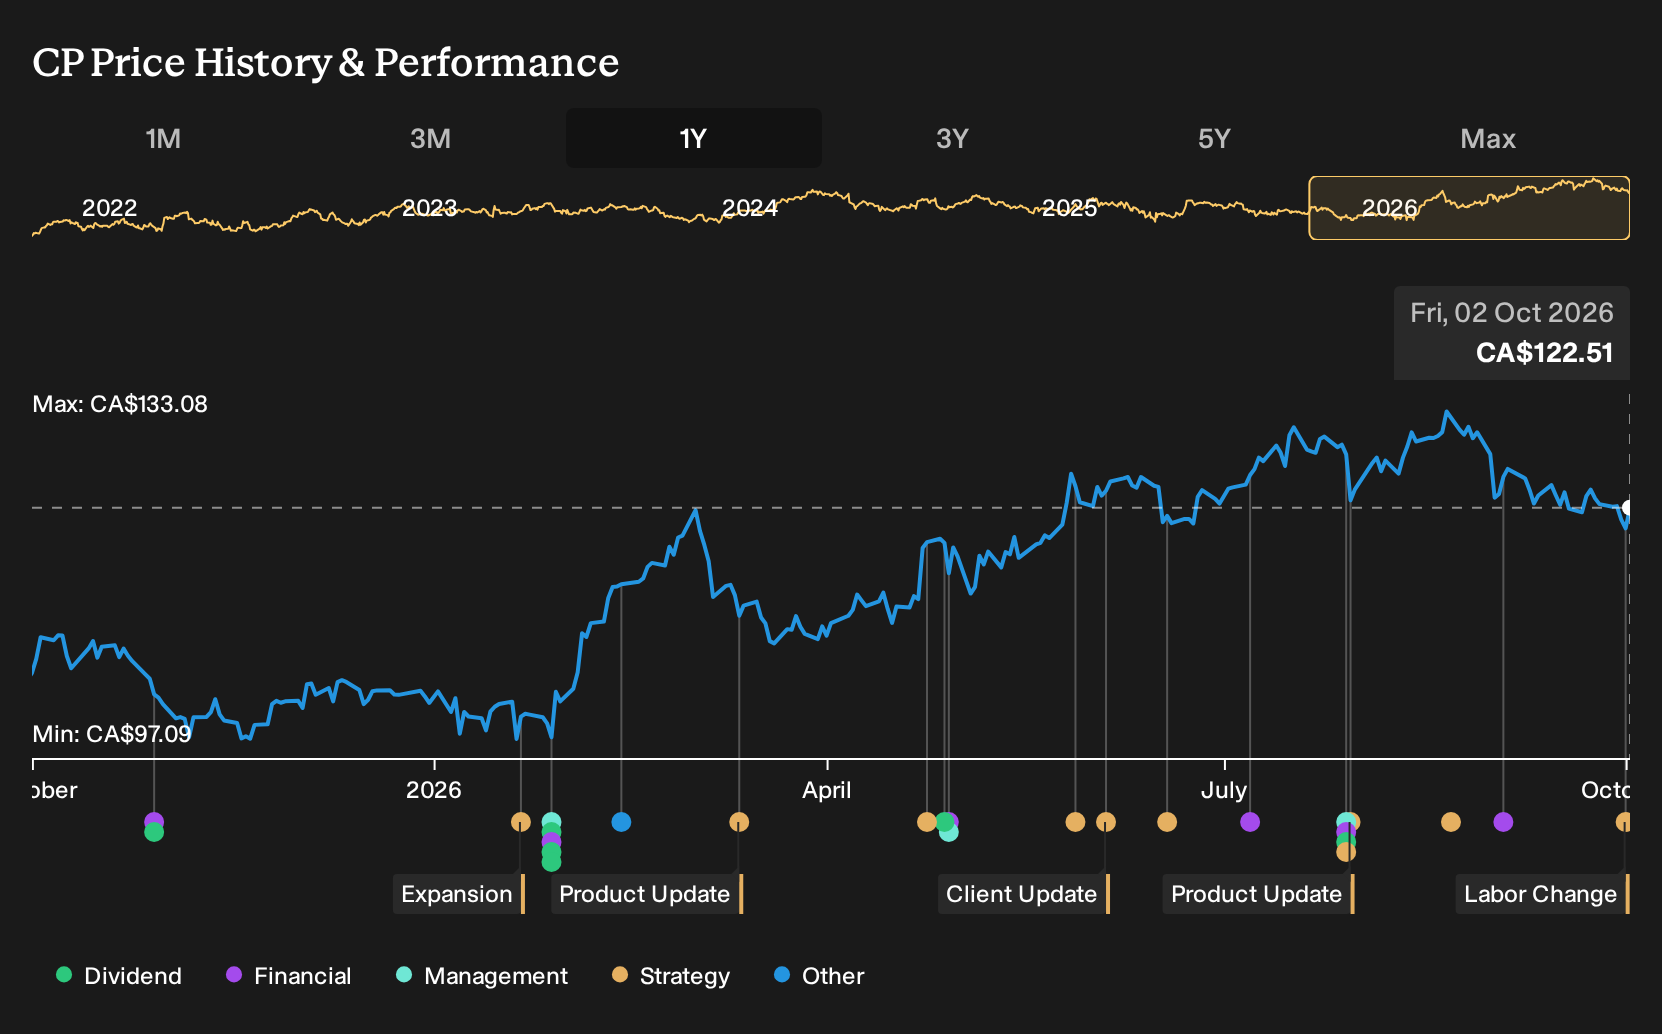
- Canadian Pacific Kansas City recently reached a tentative five year collective agreement with the Brotherhood of Locomotive Engineers and Trainmen, covering about 250 train and engine employees on its southern Dakota, Minnesota and Eastern routes across Minnesota, Iowa, Illinois and Missouri, with higher wages and more flexible work rules pending union ratification.
- The proposed five year deal signals management’s focus on labor stability and operational continuity on important U.S. corridors, which can influence crew availability, service reliability and cost visibility for Canadian Pacific Kansas City over a multi year horizon.
- We will now look at how Canadian Pacific Kansas City's investment narrative could be affected by the new five year BLET agreement.
Scan how Canadian Pacific Kansas City's latest labor deal fits into a wider set of resilient rail and infrastructure operators by checking our hand picked list of solid balance sheet and fundamentals (7 results) aligned with similar themes.
Canadian Pacific Kansas City Investment Narrative Recap
To own Canadian Pacific Kansas City, you need to be comfortable with a capital intensive rail operator that is leaning on its three country network, operating discipline and long haul corridors for grain, potash, energy products and intermodal volumes. The key near term swing factor remains how well management keeps trains moving efficiently while integrating projects like Meridian Speedway and new CSX connections without eroding service.
The tentative five year BLET agreement on the southern DM&E routes looks incremental rather than transformative. It supports crew stability and planning but does not remove bigger risks such as macro softness in energy and forest products, cross border trade policy shifts, or higher costs linked to a growing asset base and elevated debt.
The recent cluster of Canadian Pacific Railway Company fixed income offerings is the clearest companion development to this labor deal. CPKC has issued and announced multiple tranches of guaranteed, senior unsecured notes across 2030, 2037 and 2056 maturities, with coupons between 4.20% and 5.40% and an aggregate size of more than CA$1.2b completed plus further amounts announced.
For you as a shareholder, this highlights a simple tension. The rail network requires heavy, long dated investment in sidings, locomotives and cross border corridors. At the same time, the balance sheet already carries a high level of debt. Execution on capacity projects and intermodal partnerships may influence earnings, while interest costs and macro conditions across North America remain central risks.
How The Labor Deal Sits Beside Analyst Expectations For Canadian Pacific Kansas City
Canadian Pacific Kansas City now has a fresh labor framework on a slice of its U.S. network at the same time analysts are pencilling in steadily higher volumes and profitability over the next several years. The contract sets the stage for more predictable crew costs and availability, while the analyst models hinge on revenue momentum, margin gains and disciplined capital use through to the end of the decade.
Canadian Pacific Kansas City's narrative projects CA$19.0b in revenue and CA$5.4b in earnings by 2029. This is based on analysts assuming 7.2% yearly revenue growth and an earnings increase of about CA$1.5b from earnings today of roughly CA$3.9b.
Uncover why Canadian Pacific Kansas City's fair value indicates a 14% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between CA$124.25 and CA$139.68, which already shows how widely opinions on Canadian Pacific Kansas City can differ. When you set these against risks around trade policy or network execution, you get very different stories about future resilience. Explore several viewpoints before deciding where you stand.
Explore 2 other Canadian Pacific Kansas City fair value estimates, including one that suggests it could be worth just CA$124.25.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Canadian Pacific Kansas City research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Canadian Pacific Kansas City. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Canadian Pacific Kansas City's overall financial health at a glance.
Looking For More Investment Ideas Beyond Canadian Pacific Kansas City?
If this Canadian Pacific Kansas City update sharpened your thinking, use that momentum to scan a wider field of opportunities that fit your risk appetite and income goals.
- For investors who want potential income plus staying power, examine a curated set of 1 dividend fortresses built to highlight payout strength and resilience.
- If capital preservation matters most, check a focused group of 8 resilient stocks with low risk scores where balance sheet quality and volatility filters do the heavy lifting.
- For those hunting for underfollowed opportunities with solid fundamentals, review a targeted collection of 9 high quality undiscovered gems that rarely feature on headline stock lists.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com