
Sugar Separation Tool Could Matter For DuPont Stock
- DuPont de Nemours recently introduced the Sugar Separation Advisor, a digital tool that helps sugar and sweetener producers assess chromatographic separation options and identify DuPont AmberLite resins based on experimental data.
- The platform turns DuPont de Nemours’ chromatography know how and benchmarking work into a self service resource, which can streamline early process design for customers and potentially influence demand for higher performing resin products.
- We will now examine how DuPont de Nemours’ broader investment narrative could be affected by this new Sugar Separation Advisor launch.
Scan more process focused opportunities like DuPont de Nemours’ Sugar Separation Advisor launch by running the curated 19 high quality undiscovered gems that are building value from niche manufacturing and materials expertise.
DuPont de Nemours Investment Narrative Recap
To own DuPont de Nemours, you need to be comfortable with a focused industrial materials business that leans heavily on productivity programs, tight cost control and disciplined capital allocation to turn modest revenue expansion into higher free cash flow. The main near term swing factor is execution on those efficiency efforts while keeping the portfolio shift toward Healthcare & Water Technologies on track.
The biggest operational risk remains extra environmental or legal cash outflows and any squeeze from input cost inflation or pricing pushback. The Sugar Separation Advisor is helpful commercially, but it does not change that near term risk reward balance in a material way on its own.
The Sugar Separation Advisor launch fits squarely into DuPont de Nemours using digital tools and accumulated lab work to support its higher value resin and water businesses. This kind of product support can make R&D spend more visible to customers and keep existing assets, such as AmberLite, in front of engineers who specify separation solutions.
For catalysts, this matters most if it helps fill the pipeline of new separation projects in Healthcare & Water Technologies at a time when some water projects are being delayed in regions like the Middle East. The risk is simple. If tools like this fail to translate into qualified trials and orders, the burden stays on cost cutting to sustain earnings progress.
DuPont de Nemours' narrative projects US$8.0b revenue and US$942.0m earnings by 2029. This implies 4.4% yearly revenue growth and an earnings increase of about US$636.0m from the current US$306.0m level.
Discover why DuPont de Nemours' fair value signals a 31% potential upside to its current price, a gap that could close quickly.
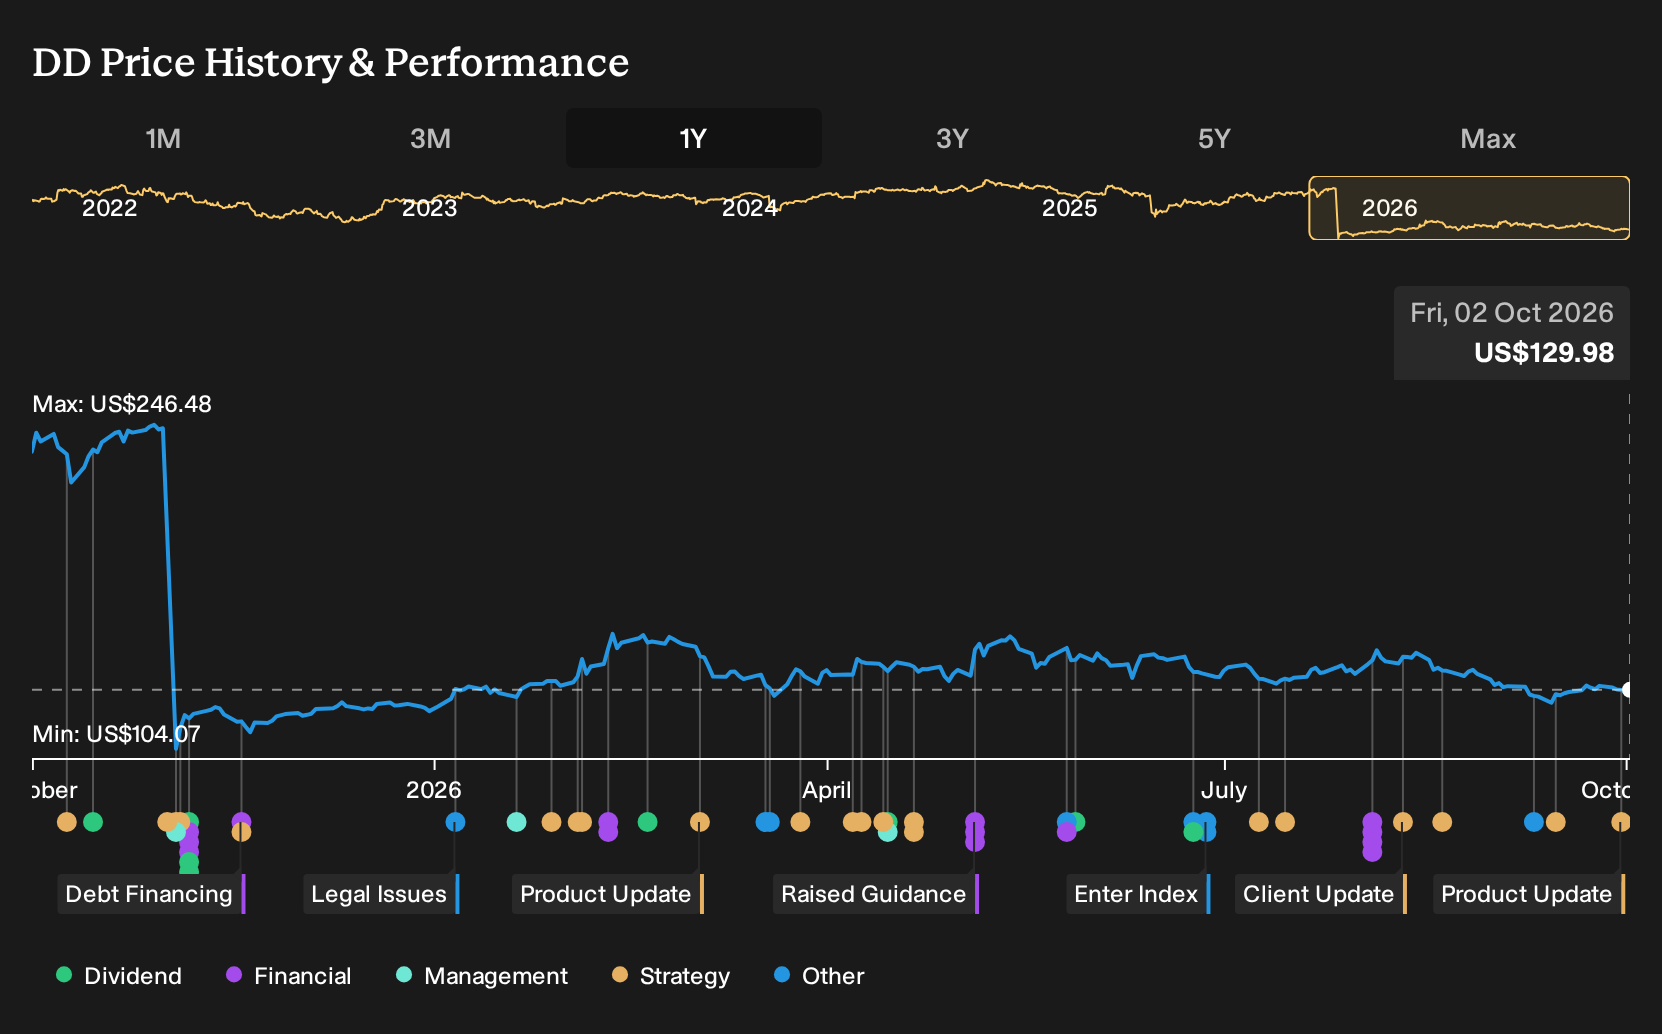
Exploring Other Perspectives
One alternate view puts less weight on DuPont de Nemours’ digital tools and more on environmental cash drag. The most cautious analysts were already building in PFAS settlements and only about 4.2% annual revenue growth to roughly US$7.9b by 2029. That more restrained story could shift if the Sugar Separation Advisor reshapes expectations.
Explore 3 other DuPont de Nemours fair value estimates, including one that suggests it could be worth just $156.00!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your DuPont de Nemours research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for DuPont de Nemours. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DuPont de Nemours' overall financial health at a glance.
Looking For More Ideas Beyond DuPont de Nemours?
If the DuPont de Nemours story has sharpened your thinking about quality, risk, and balance sheets, it can be useful to compare it with other candidates that match different objectives, from value hunting to income or capital preservation.
- For readers hunting for mispriced quality, scan a curated pool of companies that combine strong fundamentals with attractive pricing through the 31 high quality undervalued stocks.
- If dependable income matters most to you, start with a focused set of higher yield payouts by reviewing the 7 dividend fortresses.
- For a more defense minded approach, narrow your watchlist to sturdier balance sheets and lower risk profiles by filtering with the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com