
How Investors May Respond To CONMED (CNMD) Earnings Beat
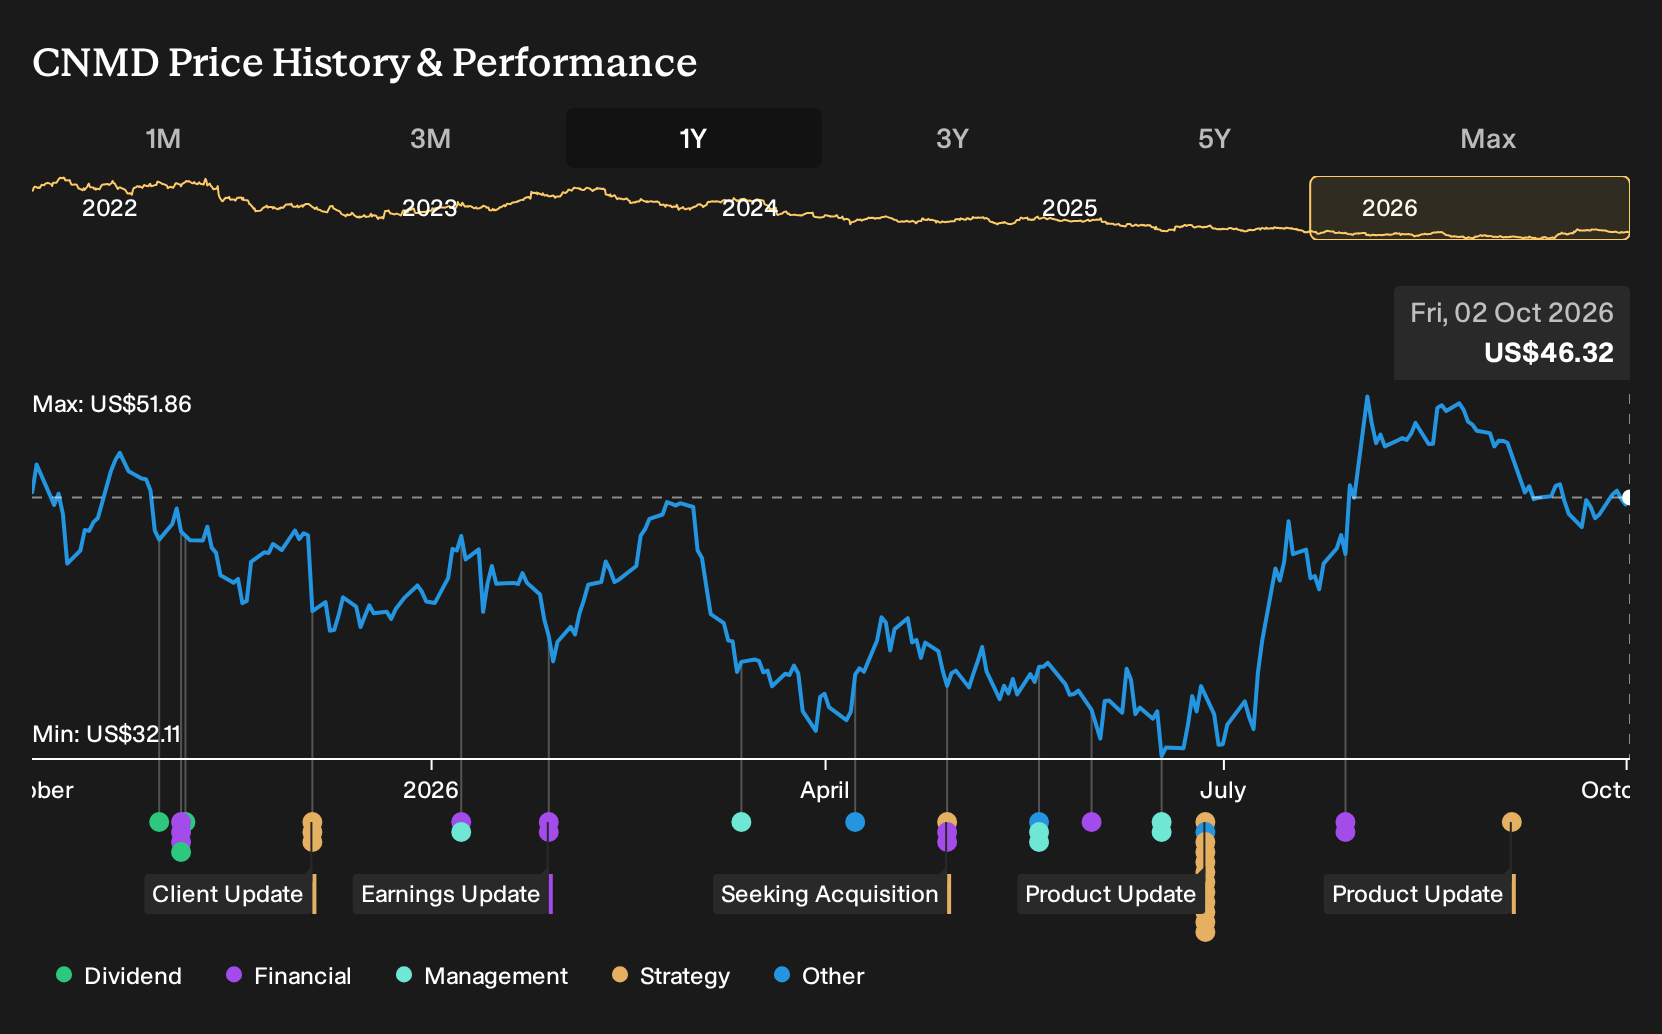
- CONMED reported quarterly revenue of $343.5 million that was flat year on year yet still above analyst expectations, and the company exceeded earnings per share estimates while lifting full year EPS guidance.
- Despite slower top line progress than peers, CONMED converted a stable revenue base into stronger profitability, which highlights the impact of cost control and mix on its earnings power.
- We will now explore how this earnings outperformance, built on flat sales but higher profitability, may influence CONMED’s broader investment narrative.
Compare CONMED's earnings-led move with other hospital and surgery suppliers by scanning our hand picked list of solid balance sheet and fundamentals (26 results) for potential candidates demonstrating similar profitability momentum.
CONMED Investment Narrative Recap
To own CONMED, you need to be comfortable with a story that leans more on procedure growth, product adoption in areas like AirSeal and BioBrace, and margin improvement than on rapid sales expansion. The latest quarter fits that lens. Revenue held flat at US$343.5 million, yet stronger earnings and higher full year EPS guidance show that cost discipline and product mix can still matter a lot in the near term.
The key short term swing factor is whether CONMED can keep translating a steady top line into cleaner, more repeatable profitability as supply chain and orthopedic share headwinds are addressed. The biggest immediate risk remains pressure on hospital capital budgets and elective procedure volumes, which could keep revenue sluggish and make further margin gains harder to sustain.
The most relevant recent development is CONMED lifting full year EPS guidance alongside flat quarterly sales that still came in slightly ahead of expectations. That combination reinforces the current focus on margin quality, operating leverage and the benefit of operational clean up, even when headline growth trails peers in medical equipment.
For catalysts, this earnings update puts more weight on execution in areas already flagged as potential drivers, such as supply chain improvements, orthopedics capacity and better manufacturing efficiency. It also interacts directly with risks already on the table, like elevated SG&A and R&D as a share of sales and debt that is not yet well covered by operating cash flow, since any stumble in profitability would quickly matter for balance sheet flexibility.
CONMED's current narrative rests on analysts expecting revenue to compound at 4.2% a year, building to US$1.6b in sales and US$179.7 million in earnings by 2029, compared with earnings of US$56.5 million today. This implies roughly a 3x increase in profit over that period.
Uncover why CONMED's fair value is essentially aligned with its current price.
Exploring Other Perspectives
One alternate view leans heavily on CONMED’s product adoption as a catalyst. Those bullish analysts were already penciling in revenue of about US$1.6b and earnings of roughly US$171.8 million by 2029, with EPS near US$5.79. This optimistic path could shift after flat sales but stronger profit in the latest report, so explore how expectations might reset.
Explore 3 other CONMED fair value estimates, including one that suggests potential upside of as much as 126% from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your CONMED research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for CONMED. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CONMED's overall financial health at a glance.
Looking for more CONMED investment ideas?
If this CONMED update sharpened your thinking and you want to widen the opportunity set, the Simply Wall St screener can help you quickly filter for businesses that fit your style, risk comfort and income needs.
- If you want companies that pair financial resilience with cleaner balance sheets, scan our 31 resilient stocks with low risk scores to keep downside risk in sharper focus.
- For investors hunting for quality at a sensible price, check out our 31 high quality undervalued stocks and see which businesses currently line up with that profile.
- If income is a priority, focus on stocks in our 7 dividend fortresses that combine higher yields with a focus on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com