
DXP Enterprises Stock Rally Raises A Bigger Question About Industrial Demand
- DXP Enterprises recently participated in a sector-wide uplift in industrial distribution stocks that reflected renewed optimism around industrial end markets and capital spending.
- The move spotlights how sensitive DXP Enterprises can be to shifts in macro signals that influence customer project pipelines and equipment spending decisions.
- We will look at how DXP Enterprises' investment narrative meshes with this sector-wide rally tied to stronger industrial demand signals.
Scan other industrial distributors moving on similar signals and see how DXP Enterprises stacks up by filtering for list of solid balance sheet and fundamentals (26 results).
DXP Enterprises Investment Narrative Recap
To own DXP Enterprises, you need to believe the business can keep turning its industrial niche, MRO distribution and pumping solutions, into steady earnings while managing its energy project exposure and acquisition program. The recent sector rally is mostly sentiment. It flags better macro signals but does not on its own change the near term fundamentals.
The key short term swing factor is execution in Service Centers and Supply Chain Services, where growth and contract profitability look uneven. The biggest risk is that rising labor costs, integration expenses and any slowdown in oil and gas orders pressure margins while debt remains only partially supported by operating cash flow.
With no fresh company specific announcements tied directly to this sector move, the most relevant reference point is the existing focus on digital initiatives and e commerce. That push matters because a rising industrial tide only helps if DXP Enterprises can route more activity through higher margin, more efficient channels.
Those same projects also connect to the main risks. If digital tools, supply chain services and acquisition integrations lag industry leaders, then manufacturer direct selling and competing platforms could compress gross margins over time. For you, the question is whether current execution on these programs is strong enough to justify treating this rally as more than a sentiment pop.
DXP Enterprises' current narrative rests on analysts expecting revenue to expand at about 8.7% a year, with earnings rising from US$93.1 million today to US$174.7 million by 2029. This implies earnings need to grow by roughly US$81.6 million for the business to reach the projected US$2.7 billion revenue and earnings profile in 2029.
Uncover how DXP Enterprises' fair value indicates a 3% potential upside to its current price before other investors fully recognize that gap in the market.
Exploring Other Perspectives
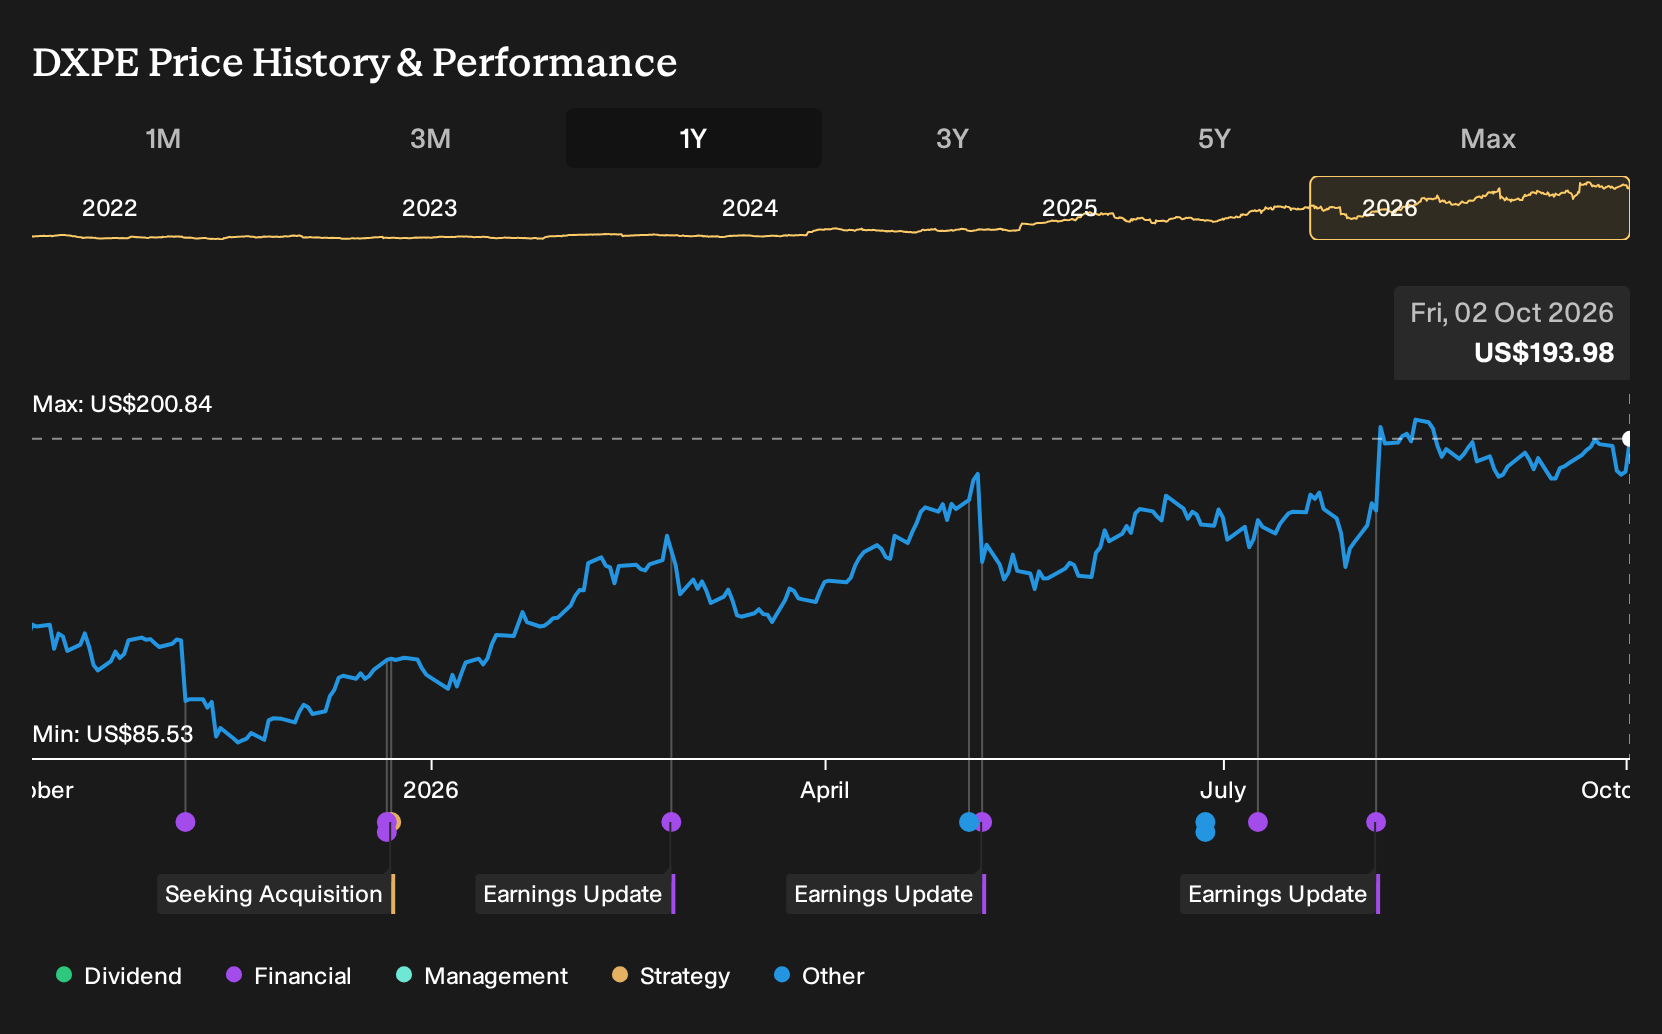
Two fair value estimates from the Simply Wall St Community cluster tightly between US$200 and about US$201 a share, suggesting those contributors see DXP Enterprises trading within a narrow valuation band. These views sit alongside meaningful risks in energy exposure, labor costs and acquisition execution, so explore multiple viewpoints before relying on any single number.
Explore another DXP Enterprises fair value estimate, including one that suggests it could be worth as much as $201.04.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your DXP Enterprises research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for DXP Enterprises. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DXP Enterprises' overall financial health at a glance.
Looking For More Ideas Beyond DXP Enterprises?
If you want to pressure test your view on DXP Enterprises, a smart next step is to compare it with a few other businesses that share similar quality markers or risk profiles. The Simply Wall St Screener can help you quickly surface a curated set of alternatives that match the type of opportunity you are looking for.
- For investors who care most about balance sheet strength and underlying fundamentals, start with a list of solid balance sheet and fundamentals (26 results) that already clear some key quality hurdles.
- If you are hunting for potential value opportunities that pair financial resilience with mispriced expectations, take a look at 31 high quality undervalued stocks that fit those criteria.
- For readers who want something off the beaten path but still grounded in solid numbers, consider scanning 19 high quality undiscovered gems that may not yet be widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com