
Should New Xbox Deal Require Action From Take Two Investors?
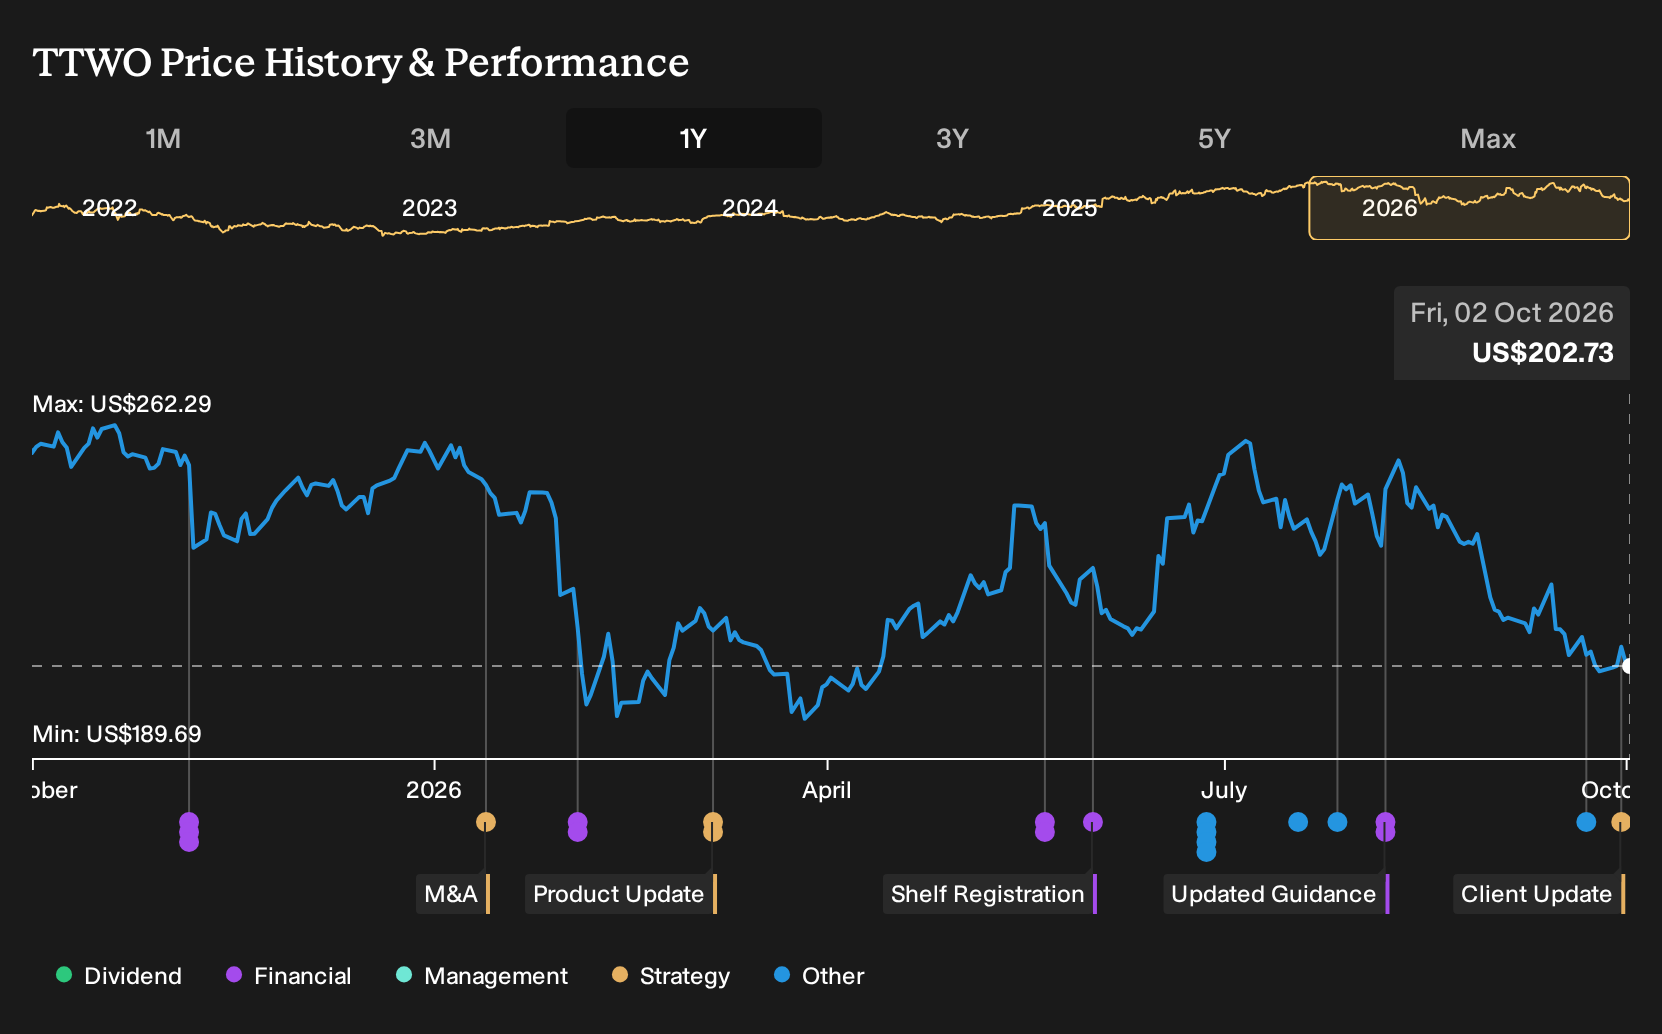
- Take-Two Interactive announced a new long term XBOX Publisher License Agreement with Microsoft, effective September 17, 2026. The agreement covers development, publishing, manufacturing, marketing and sales of XBOX compatible products and replaces all prior XBOX publisher arrangements.
- The refreshed Microsoft agreement sets clearer terms around digital revenue sharing, physical media fees and content approval. This directly affects how Take-Two Interactive monetizes its core console portfolio and allocates development and marketing spend over the contract period.
- We will examine how Take-Two Interactive's investment narrative is affected by this long term XBOX licensing deal that reshapes console economics.
Scan how Take-Two Interactive stacks up against other potential console and gaming beneficiaries by reviewing 19 high quality undiscovered gems before the next round of platform deals is announced.
Take-Two Interactive Software Investment Narrative Recap
To own Take-Two Interactive Software, you need to believe its big franchises and mobile portfolio can turn strong engagement into healthier earnings over time, even though the group is currently loss making on US$6.69b of revenue. The most important near term driver remains execution around major releases like Grand Theft Auto VI and monetisation of recurrent spending.
The biggest risk is still concentration in a few blockbuster series, especially after the Grand Theft Auto VI leak and recent project impairment. The long term XBOX Publisher License Agreement mostly formalises console economics rather than changing that risk reward balance in the short run. As a result, the near term story still depends heavily on content delivery and player spending.
The new long term XBOX Publisher License Agreement with Microsoft is the key disclosure to focus on here. It resets how Take-Two Interactive Software handles console distribution on XBOX, from digital revenue sharing through to physical media fees, which affects margins on core franchises and downloadable content.
For catalysts, that contract provides a clearer economic framework just as the business leans harder into digital and direct channels. The detailed revenue share terms and Microsoft approval rights sharpen execution risk if schedules slip or content needs rework, but they also give investors a more defined backdrop for how console bookings could convert to cash flow once major titles reach the market.
Take-Two Interactive Software's narrative projects US$9.8b revenue and US$1.2b earnings by 2029. This aligns with analysts assuming 13.6% yearly revenue growth and implies an earnings swing of about US$1.52b from current earnings of a US$320.4m loss.
Uncover why Take-Two Interactive Software's fair value signals a 41% potential upside to its current price and why this gap could narrow faster than many investors expect.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Take-Two Interactive using digital distribution and direct channels to lift earnings faster than the baseline suggests. Before this XBOX deal, they were already pencilling in revenue of US$13.1b and earnings of US$1.9b by 2029. That is far above consensus, and the new agreement could eventually reshape those views again.
Explore 7 other Take-Two Interactive Software fair value estimates, including one that suggests as much as 72% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Take-Two Interactive Software research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Take-Two Interactive Software. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, making it easy to evaluate Take-Two Interactive Software's overall financial health at a glance.
Looking for more investment ideas beyond Take-Two Interactive Software?
Once you have a view on Take-Two Interactive Software, the next step is to line it up against other opportunities that fit different risk and income profiles. The Simply Wall St Screener can help you quickly surface stocks that match the kind of portfolio you want to build, rather than forcing everything to fit the same mold.
- For investors hunting for mispriced opportunities with solid fundamentals, scan a focused list of 31 high quality undervalued stocks that may warrant a closer look.
- If capital preservation comes first and price swings keep you up at night, narrow your universe to 31 resilient stocks with low risk scores that aim to keep volatility in check.
- For readers who care most about balance sheet strength and financial resilience, start with a curated list of solid balance sheet and fundamentals (26 results) to see which businesses clear your quality bar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com