
Flotek Industries (FTK) Secured A $120 Million Loan, Is The Upside Already Priced In?
Why Flotek Industries Just Tapped a New $120 Million Debt Facility
Flotek Industries (FTK) has secured a new term loan facility of up to $120 million, a financing move that reshapes its debt profile and provides additional flexibility to invest in its Data Analytics segment.
The fresh financing arrives after a strong run in Flotek Industries’ stock, with the share price at $30.94 and a 30-day share price return of 31.44% feeding into an 81.47% year-to-date gain. The 3-year total shareholder return of roughly 7x and 5-year total shareholder return of 381.93% point to momentum that investors appear to be linking to both recent announcements and the longer-term shift toward its Data Analytics business.
Scan beyond Flotek Industries to see how other hand-picked operators with strong balance sheets and fundamentals are positioned around this kind of funding move with our list of solid balance sheet and fundamentals (25 results).
Flotek Industries has fresh capital in place, a sharp run in the share price, and a bigger push into Data Analytics. Is it worth committing cash now, or does patience offer a better entry point?
Most Popular Narrative: 19% Undervalued
Against a last close of $30.94, the most followed narrative for Flotek Industries anchors on a fair value of $38.25, which leans heavily on the Data Analytics story and long-term contracts rather than recent share price momentum.
Multi-year contracts and a growing customer base for high-margin Data Analytics offerings (including both power generation and custody transfer segments) provide significant revenue visibility and margin expansion potential, particularly as these segments shift to become the majority profit contributors by 2026. Strong pipeline of pilot programs and scalable deployments in both traditional O&G and fast-growing energy infrastructure/data center markets allow for faster ramp-up of recurring revenue streams and further diversification of end markets, reducing reliance on any single customer and bolstering long-term topline growth.
See why 15 investors see Flotek Industries as 19% undervalued.
Result: Fair Value of $38.25 (UNDERVALUED)
Still, two issues can quickly upset the Flotek Industries story: heavy reliance on a few large contracts and the unresolved PREPA termination and related class action.
Find out about the key risks to this Flotek Industries narrative.
Another View: Flotek Industries Through A P/E Lens
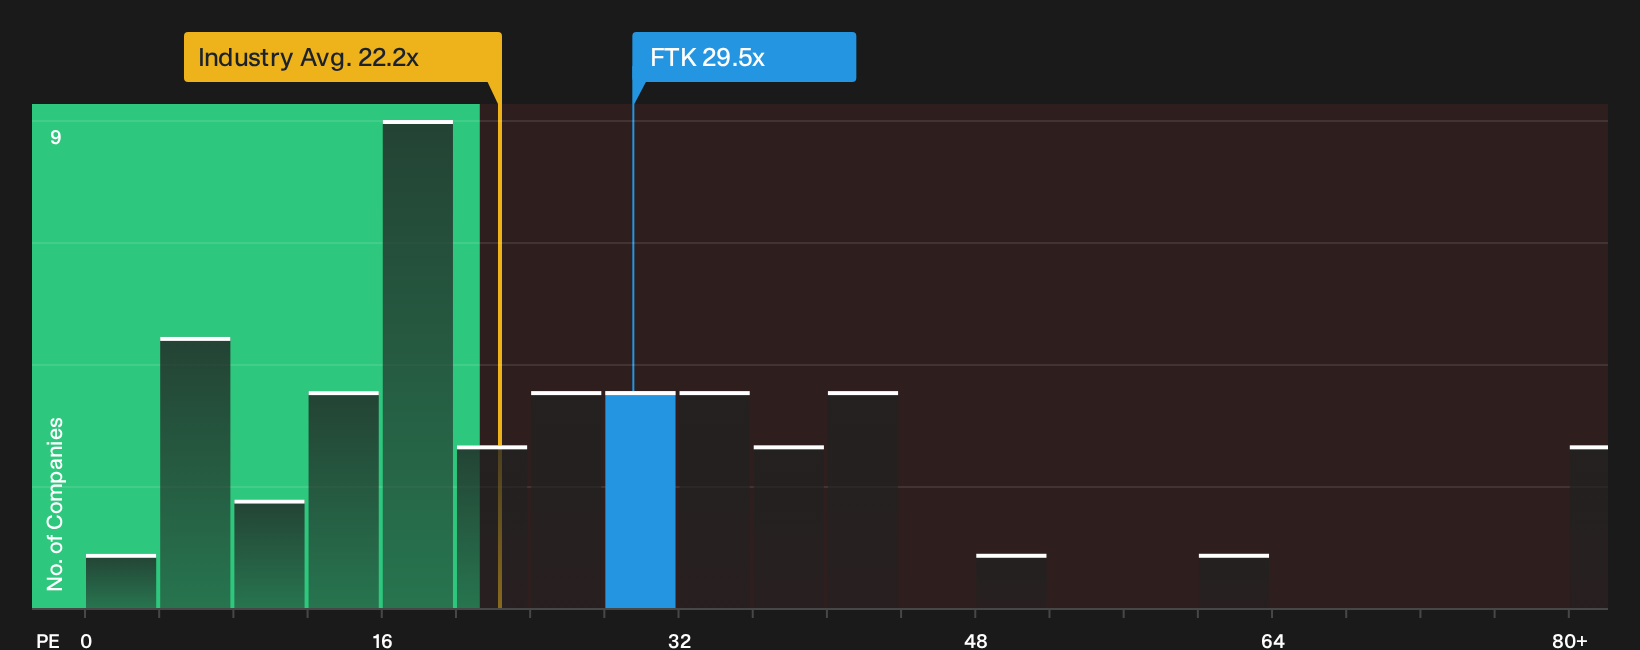
Flotek Industries may screen as undervalued against the $38.25 fair value narrative; however, its current P/E of 29.5x is punchy compared with a 22.2x multiple for the wider US Chemicals group and a 16x fair ratio that our work suggests the market could gravitate toward. Analysts still see the stock as cheaper than close peers on 40.1x, so the question becomes whether investors lean more on the bullish story or on the risk that the valuation converges toward that lower fair ratio.
To pressure test that kind of pricing against the underlying fundamentals and expectations, investors can go deeper into the valuation breakdown with the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this Flotek Industries story looks promising, yet the mix of contract risk and growth optionality pulls sentiment in two directions. To move quickly and shape a view based on the full picture, weigh the 3 key rewards and 3 important warning signs.
Looking for more Flotek Industries‑style investment ideas?
If Flotek Industries has you thinking more broadly about where to put fresh capital, do not stop with a single ticker. Use targeted stock lists to surface other opportunities that fit your risk, income, or value priorities.
- Target stronger downside protection by checking companies with steadier balance sheets and fundamentals through the 31 resilient stocks with low risk scores.
- Hunt for mispriced opportunities by reviewing the 31 high quality undervalued stocks and see which businesses offer quality at a discount.
- Build a watchlist with staying power by scanning the 19 high quality undiscovered gems before everyone else starts paying attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com