
Sodexo (ENXTPA:SW) Faces A Leadership Reset On A Fairly Valued View
What Sophie Bellon’s Exit Could Mean For Sodexo Stock
Sodexo (ENXTPA:SW) is in focus after Sophie Bellon announced she will not seek renewal as Chairwoman of the Board at the December 16, 2026 shareholders meeting.
Her decision follows a long period of reshaping the group, including the spin-off and listing of Pluxee and the sale of Sodexo’s stake in Sofinsod, which now frame the context for this leadership transition.
The leadership news lands after a choppy few weeks for Sodexo, with a 7.15% 1-month share price return decline and a 6.02% fall over the past week, even though the year-to-date share price return is 25.41% and the 5-year total shareholder return is 22.94%. This indicates that longer term momentum has been positive while shorter term sentiment has cooled around the €53.9 level.
Compare Sodexo’s leadership reset with other companies where boards and executives are reshaping direction by scanning our hand picked 615 high quality undiscovered gems.
Bulls see Sodexo’s reshaped portfolio and recent board overhaul as a cleaner story, while bears focus on mixed multi year returns and leadership uncertainty. Which side does the current valuation lean toward?
Most Popular Narrative: 1% Undervalued
The most followed narrative currently places Sodexo’s fair value at €54.63, almost level with the last close of €53.9, which keeps the focus squarely on execution rather than a big valuation gap.
The ramp-up of key contracts, notably in Healthcare with organizations like Captis, is anticipated to contribute significantly to revenue in fiscal year '26 and beyond, as delays in the current fiscal year are resolved.
The intensification of sales and retention efforts in North America, with a focus on branded offers and sales team incentives, aims to enhance contract wins and retention rates, supporting future revenue growth.
See why 12 investors see Sodexo as 1% undervalued.
Result: Fair Value of €54.63 (ABOUT RIGHT)
Still, the narrative can wobble if North American contract wins stay weak, or if macro pressures in Europe squeeze Sodexo’s already thin profit margin assumptions.
Find out about the key risks to this Sodexo narrative.
Another View On Sodexo’s Valuation
The earlier narrative leans on analyst targets. A different lens, the SWS DCF model, paints a harsher picture. On that cash flow view, Sodexo’s fair value sits at €42.24, well below the current €53.9 share price, which frames the stock as overvalued on this method.
This raises a simple question for investors: do you put more weight on discounted cash flows or on what the market is currently willing to pay for near term earnings and sentiment support? Look into how the SWS DCF model arrives at its fair value.
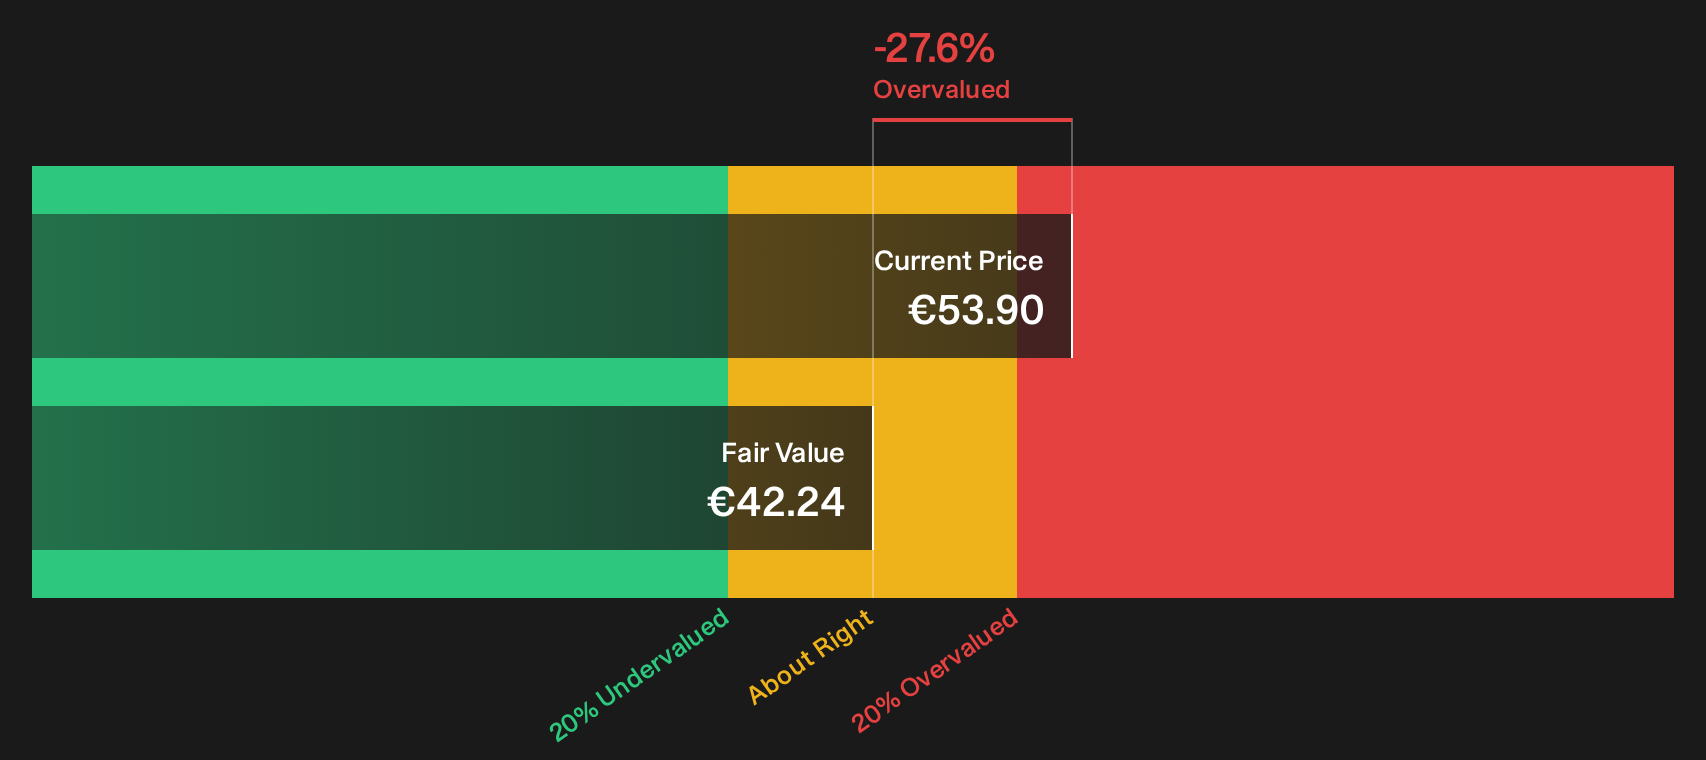
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sodexo for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 193 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Sodexo can feel confusing. Treat this as your prompt to move quickly, check the data yourself, and weigh both the 1 or more risks and the 1 or more rewards that other investors are focused on by starting with the 3 key rewards and 3 important warning signs
Ready For More Ideas Beyond Sodexo?
If Sodexo has sharpened your focus on valuation, do not stop here. Use the screener to surface other opportunities before the crowd moves on.
- Target stronger upside potential by scanning a curated pool of quality opportunities using the 193 high quality undervalued stocks.
- Strengthen your portfolio’s staying power by filtering for resilient balance sheets through the list of solid balance sheet and fundamentals (207 results).
- Build a steadier income stream by focusing on dependable yield opportunities inside the 169 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com