
Automatic Data Processing (ADP) Stock Dropped, So What Is Driving Attention Now?
Automatic Data Processing (ADP) drew investor attention after recent disclosures showed pays-per-control growth slowing to 1% in fiscal 2026, with fiscal 2027 guidance of 0% to 1% pointing to softer labor conditions.
The recent guidance hit a stock that was already losing steam in the short term, with the share price down 7.18% over the past 30 days and 2.27% over the last week. At the same time, a 12.38% three-year total shareholder return and 39.75% over five years show longer term holders have still seen gains. This suggests momentum has faded near term as investors reassess Automatic Data Processing’s growth tempo and risk profile against its current US$257.68 share price.
Compare how Automatic Data Processing stacks up against other profitable service providers by scanning our hand picked list of list of solid balance sheet and fundamentals (25 results).
Bulls see Automatic Data Processing’s recent pullback as a chance to own a profitable HCM leader on sale. Bears focus on slowing pays-per-control growth. Which story matches the valuation that comes next?
Most Popular Narrative: 10% Undervalued
Automatic Data Processing’s most followed narrative pegs fair value at $287.60, which is modestly above the recent $257.68 close and presents the pullback as a valuation gap tied to execution on its HCM roadmap and capital returns.
Adoption of Next Gen products such as Lyric HCM and Workforce Now Next Gen, together with continued uptake of global payroll and WorkForce Suite, is now showing in Employer Services bookings of more than US$2.2b in fiscal 2026 and a 94% rise in live Lyric clients, which supports future revenue and earnings growth as these contracts are implemented and ramp into the income statement.
See why 111 investors see Automatic Data Processing as 10% undervalued.
Result: Fair Value of $287.60 (UNDERVALUED)
Still, the bullish Automatic Data Processing story can crack if PEO margins stay under strain or if new AI driven payroll rivals start pressuring pricing and wins.
Find out about the key risks to this Automatic Data Processing narrative.
Another View: What The Cash Flows Say About Automatic Data Processing
The first story leans on analyst targets that put Automatic Data Processing at a fair value of $287.60. A second lens, the Simply Wall St DCF model, points to a future cash flow value of $254.88, which makes the current $257.68 price look slightly overvalued instead of 10% undervalued.
This gap is small in absolute dollars but meaningful for risk. One framework treats the recent pullback as a discount to fair value, while the cash flow lens says investors are already paying a little above modeled intrinsic value. Which anchor will you trust when sentiment swings again?
Look into how the SWS DCF model arrives at its fair value.
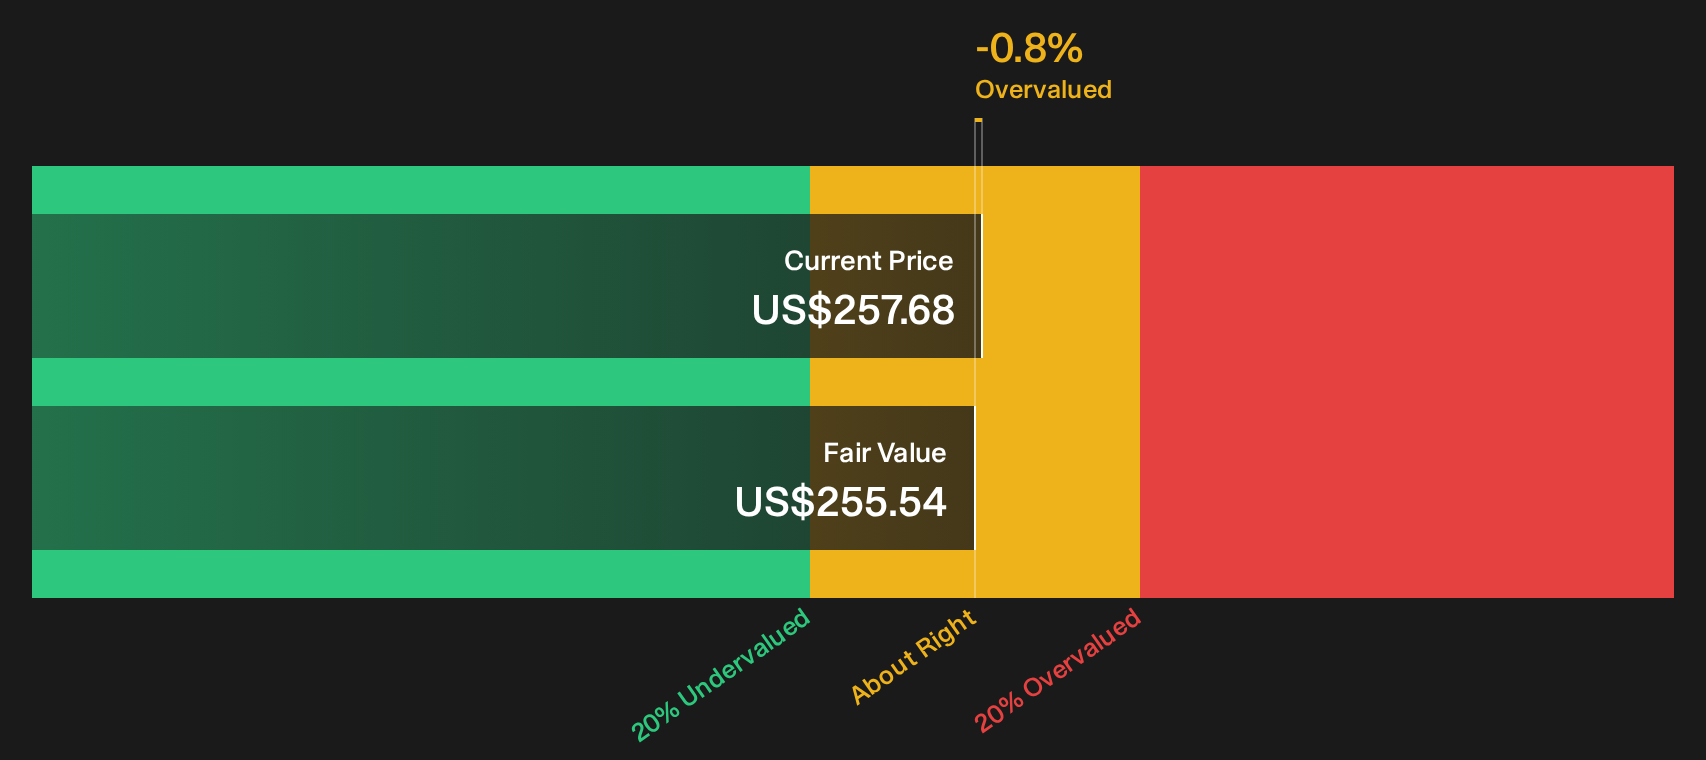
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Automatic Data Processing for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Automatic Data Processing is split right now, which is exactly when fresh eyes on the numbers matter most. Move quickly, stress test the assumptions that matter to you, and see how they line up with 3 key rewards
Looking For More Investment Ideas Beyond Automatic Data Processing?
If Automatic Data Processing has sharpened your focus on quality, you can broaden your opportunity set by hunting for stocks that better match your return goals and risk comfort.
- Target potential bargains by zeroing in on companies that combine quality fundamentals with attractive pricing through our 31 high quality undervalued stocks.
- Strengthen income potential by focusing on businesses that support higher yields in our 7 dividend fortresses.
- Prioritize resilience by screening for companies with healthier finances and robust fundamentals using the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com