
Why Adecoagro (AGRO) Could Be 45% Undervalued After Redeeming Its 2027 Notes
Adecoagro (AGRO) has moved to redeem all of its outstanding 6.000% Senior Notes due 2027. This liability management decision immediately reshapes the company’s near term debt profile for equity holders.
Adecoagro’s early bond redemption comes after a mixed stretch in the market. The share price is up 30.15% year to date but down 14.19% over the past 30 days, while the 1 year total shareholder return of 33.69% indicates that longer term momentum has been more supportive than the recent pullback.
Scan for other balance sheet focused opportunities that echo Adecoagro’s debt discipline by reviewing our hand picked list of 31 resilient stocks with low risk scores in similar and adjacent sectors.
Adecoagro now trades at a steep discount to both analyst targets and some intrinsic estimates after retiring its nearest bond maturity. Is that gap a sign of appropriate caution, or has the balance sheet reset been too widely ignored?
Most Popular Narrative: 45% Undervalued
Adecoagro’s most followed valuation storyline pegs fair value at $18.28 per share against the latest close of $10.10, which points to a sizeable gap that the recent bond redemption could influence over time.
While the market chases the next breakthrough in AI infrastructure, Adecoagro sits quietly as a deeply discounted, cash-flowing fortress. It offers growth investors a rare "Margin of Safety", a business fundamentally insulated from local currency risks, fortified by monopolistic assets, and mathematically positioned to turn the upcoming "Super El Nino" into a multi-year catalyst for margin expansion.
See why 5 investors see Adecoagro as 45% undervalued.
Result: Fair Value of $18.28 (UNDERVALUED)
Still, the Adecoagro narrative can break if climate patterns differ from current expectations or if fertilizer pricing and urea imports soften faster than forecast.
Find out about the key risks to this Adecoagro narrative.
Another Take On Adecoagro’s Valuation
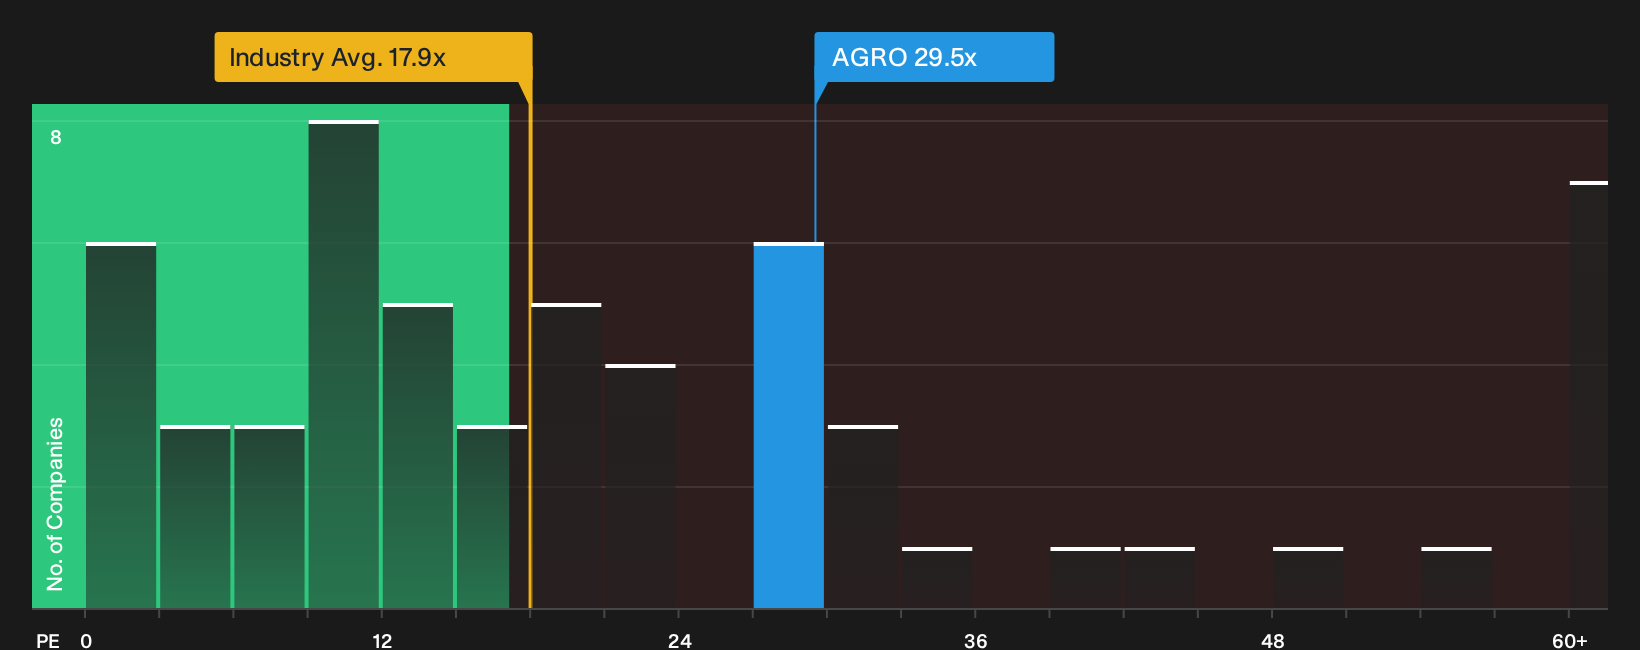
The share price story around Adecoagro looks generous on one metric and stretched on another. While the SWS DCF model points to AGRO trading at $10.10 versus an estimated future cash flow value of $55.02, the current P/E of 29.5x sits well above both the fair ratio of 22.6x and peer and industry averages near 17x to 18x. That gap signals either extra upside optionality or a thinner cushion if sentiment cools. Which risk are you more comfortable holding?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Adecoagro’s value and risk profile can create noise, so step in quickly, review both sides of the story, and weigh the 4 key rewards and 4 important warning signs.
Looking for more Adecoagro style investment ideas?
If Adecoagro has sharpened your focus on pricing and risk, do not stop here. Put that mindset to work and hunt for better opportunities.
- Target resilient cash generators by scanning our 31 high quality undervalued stocks that combine compressed prices with solid fundamentals.
- Prioritize capital preservation and sleep-at-night holdings by reviewing a list of solid balance sheet and fundamentals (25 results) that can better handle tough conditions.
- Pursue asymmetric upside by zeroing in on a 8 elite penny stocks with strong financials that already shows strong financial underpinnings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com