
What Did The Market Miss About Methode Electronics (MEI)?
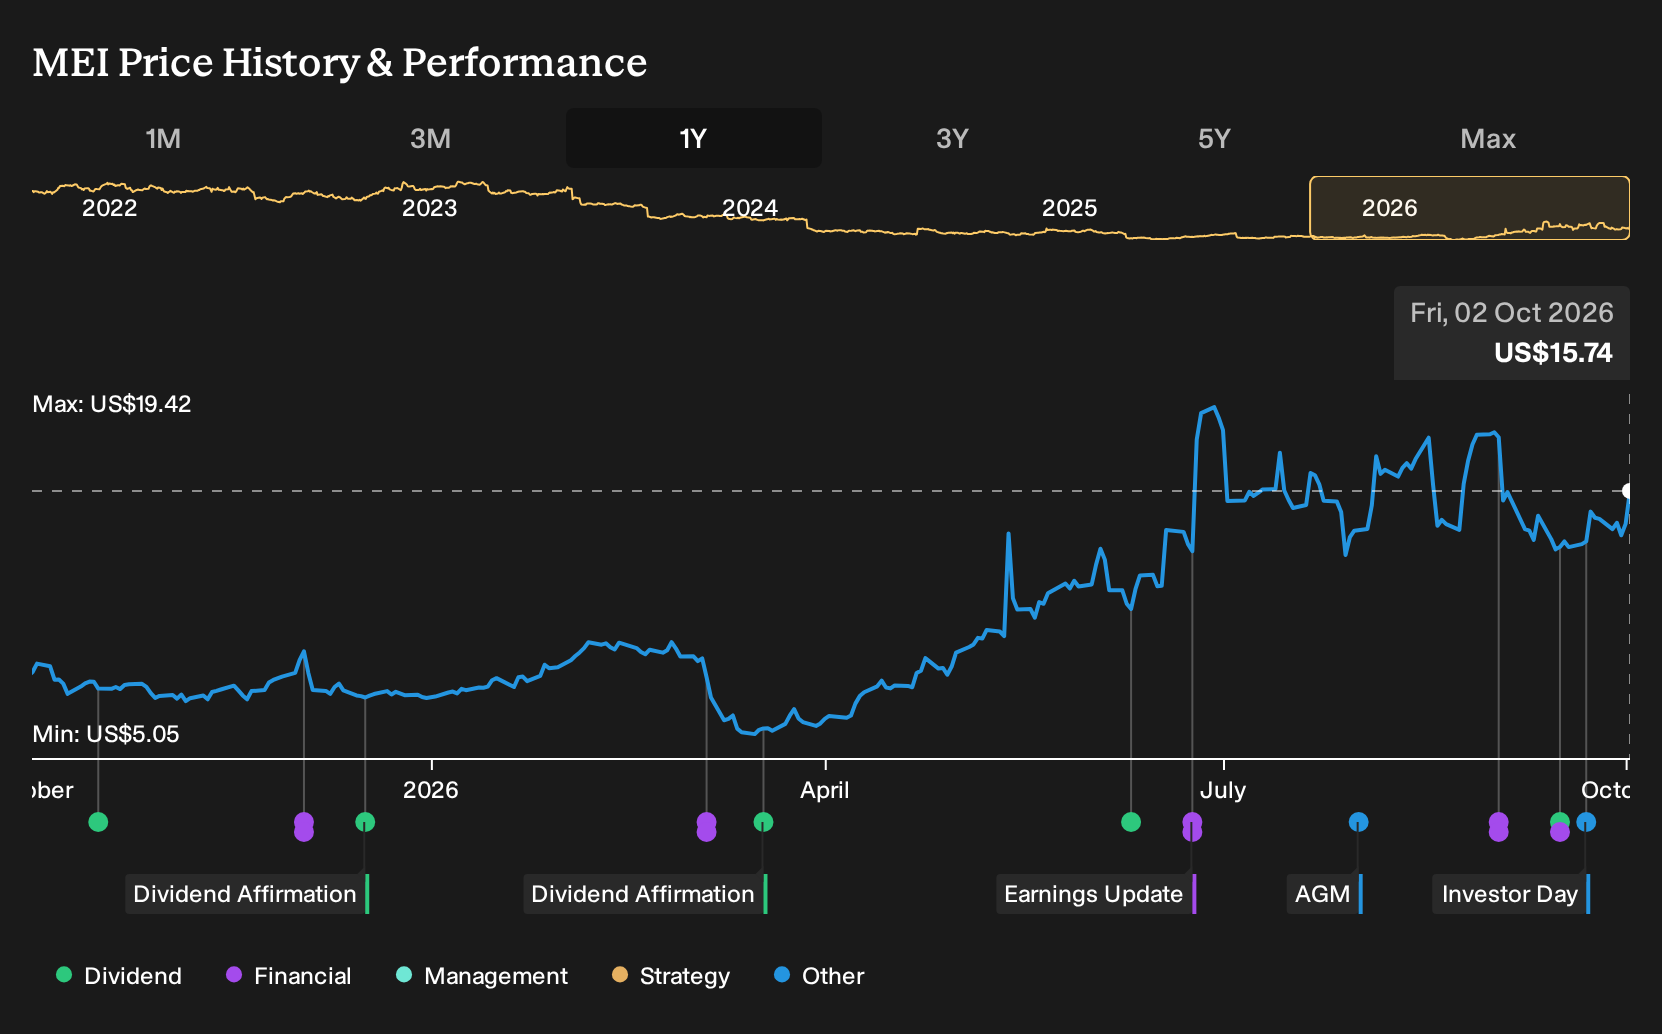
If you had read the opposing August 2025 views on Methode Electronics, you saw one camp expecting long-term opportunity from data centers and EVs while another warned Stellantis delays and shrinking auto demand could drag on results. Holding Methode Electronics over the past year would have returned 97.9%, including dividends. If that outcome rested on such conflicted expectations, what exactly did investors really know when they chose to buy or to stay away?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
Methode Electronics is not the only name tied to this theme. Zero in on 16 top copper producer stocks and compare how each one is priced.
What Investors Were Really Arguing About On Methode Electronics
The shares cost US$7.78 at the start of the period, and anyone looking at Methode Electronics then had to choose between two sharply different stories about where the business might head next.
The bullish Narrative put Fair Value at US$9.5, banking on data center and EV demand and assuming revenue would decline 6.8% a year while profit margin moved to 9.0% and supported a future P/E of 6.0x.
The bearish view set Fair Value at US$7 and focused on Stellantis delays and shrinking EV volumes, assuming revenue would fall 4.2% annually but margin would still reach 9.1% on a future P/E of 4.1x.
What The Results Changed For The Methode Electronics Debate
The later Q1 2027 figures gave Methode Electronics investors a reality check. Revenue was US$265.4 million versus US$240.5 million a year earlier, yet the company still reported a loss of US$11.4 million and net margin held at a loss of 4.3%. That combination cut both ways for the original bullish and bearish narratives.
The key lesson is simple. When a thesis leans on future profit improvement, keep tracking net margin alongside sales. If losses persist even as revenue shifts, treat any forecasted margin recovery as unproven and test that claim line by line against each new earnings release.
What Today's Price Already Assumes For Methode Electronics
Methode Electronics now trades at US$15.74, roughly double the level a year ago. The selected Narrative still places Fair Value above that mark and frames the thesis around cost discipline plus a shift toward data center, EV, and automation programs.
On that view, buyers today would be assuming the 800VDC data center push and internal restructuring are not yet fully reflected in the current quote.
"Analyst consensus expects strong EBITDA growth from program launches and operational improvements, but the pace of cost reduction, global supply chain rationalization, and SG&A discipline evident in recent quarters signals a much more rapid expansion in both net margin and free cash flow than is currently factored into expectations."
The price and this Narrative do not agree. → Uncover what this Narrative says Methode Electronics is actually worth
Another Way To Play Data Centers
Methode Electronics leans on content inside vehicles and hardware around power. You could also look one step outward, at the data traffic itself.
Every new rack and AI cluster needs wired connections that move huge volumes reliably. One specialist focuses on high bandwidth switching gear plus the software that runs it.
Its operating system ties these boxes together so customers can manage networks as one fabric. That helps big buyers reconfigure capacity quickly as workloads shift.
As AI and cloud builders refine their plans, the question is how much of that long haul networking work might keep concentrating with a focused vendor.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 16% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com