
Special Dividend Approval Could Be A Game Changer For Jardine Matheson Southeast Asia (SGX:C07)
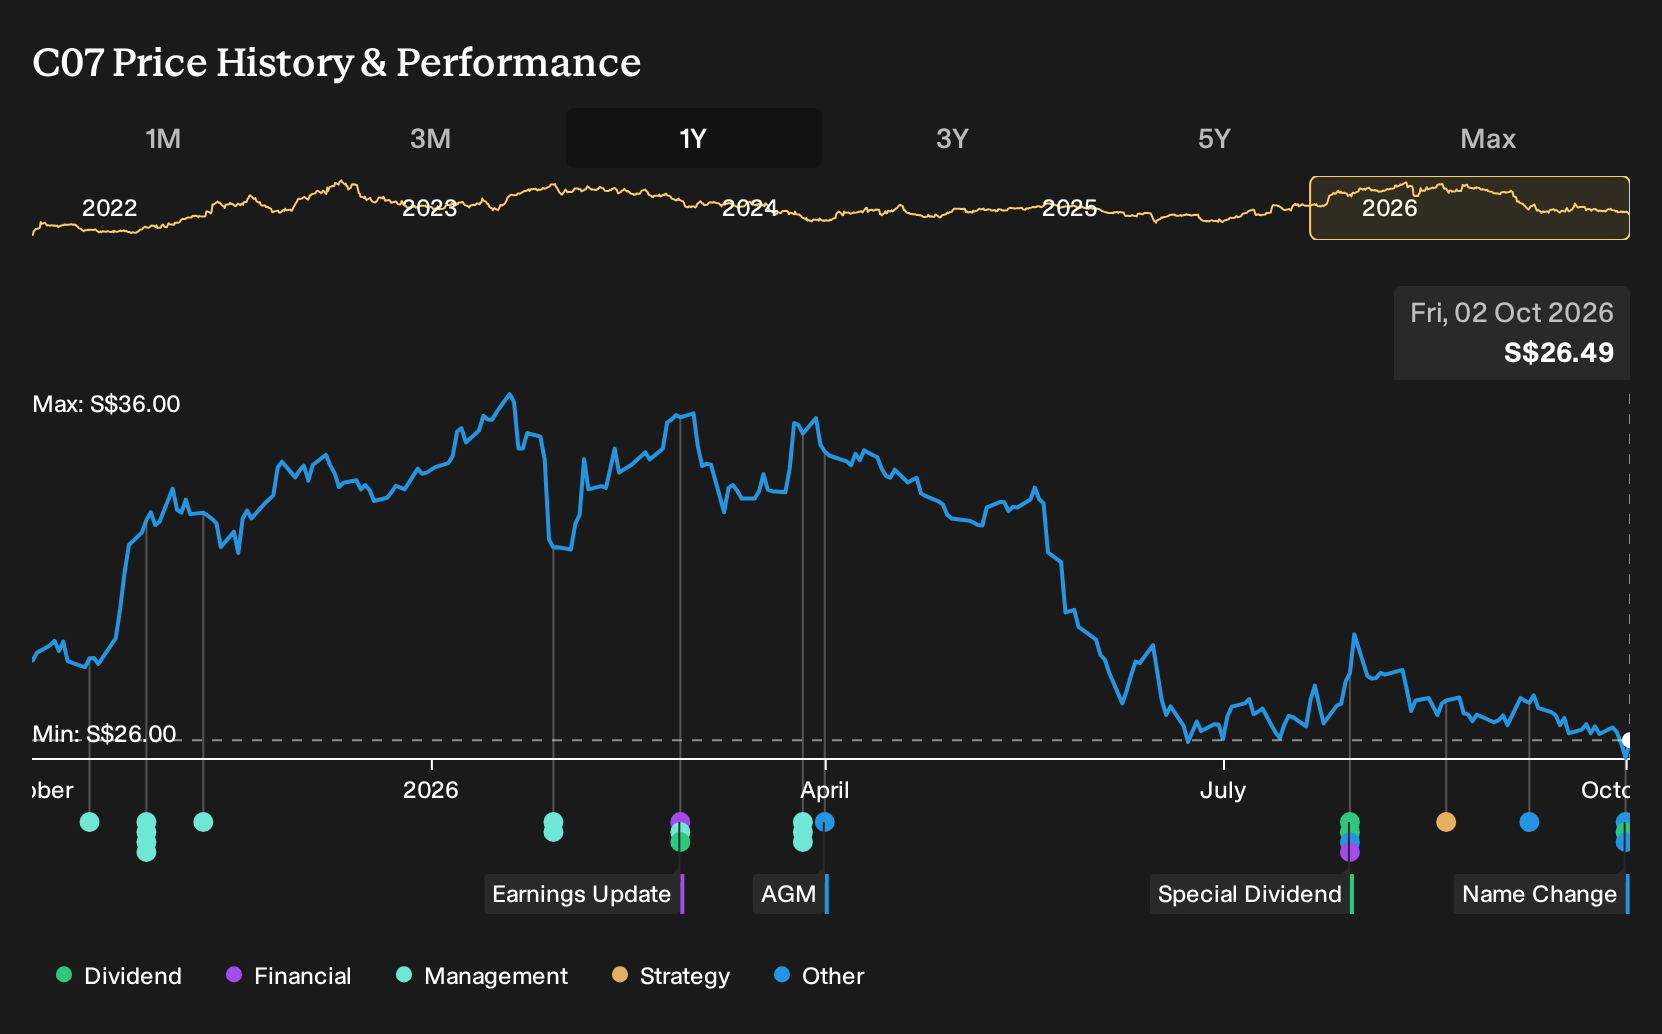
- Jardine Matheson Southeast Asia Limited, formerly Jardine Cycle & Carriage, secured shareholder approval on 1 October 2026 for a US$0.37 per share special dividend, with a record date expected on 9 October 2026, alongside amendments to its corporate constitution.
- The combination of a one off cash distribution and a rebrand toward a broader Southeast Asia identity signals management’s focus on capital return and a wider regional positioning beyond its legacy vehicle centric profile.
- We will assess how Jardine Matheson Southeast Asia’s investment narrative interacts with the newly announced special dividend to reshape investor expectations.
Compare Jardine Matheson Southeast Asia’s one off payout and regional refocus with a hand picked 168 dividend fortresses built around income strength and balance sheet resilience.
Jardine Matheson Southeast Asia Investment Narrative Recap
To own Jardine Matheson Southeast Asia, you need to believe its exposure to Indonesia via Astra and to broader regional consumption, finance, and infrastructure can keep generating resilient earnings even if headline revenue trends are soft. Revenue is currently US$20.55b with net income of US$989.7m, so profitability rather than rapid sales expansion is doing more of the heavy lifting.
The near term catalyst is operational delivery against expectations that earnings can keep growing while revenue is forecast to drift lower. The key risk is concentration in Astra and higher risk funding through external borrowing. The special dividend and rebrand are mostly capital allocation and perception events, not clearly identifiable changes to operating momentum.
The US$0.37 per share special dividend is the headline announcement that ties directly into the story. For you as a shareholder, it is a cash return that sits on top of an already mixed track record on dividend stability, which is flagged as a risk. That makes it more of a one off event rather than evidence of a new payout pattern.
Income focused holders will likely watch what this means for financial flexibility as Jardine Matheson Southeast Asia manages restructuring, external competition in autos and EVs, and pressure on Indonesian demand. The dividend sits alongside a P/E of 8.3x compared to higher sector multiples and expectations for 6.1% annual earnings growth, so execution on the core portfolio still drives the medium term story.
Jardine Matheson Southeast Asia is being valued on analyst assumptions that point to about US$19.4b in revenue and US$1.1b in earnings by 2029, based on revenue declining 1.8% per year and an earnings increase of roughly US$110m from US$989.7m today.
Uncover why Jardine Matheson Southeast Asia's fair value highlights a 7% potential upside to its current price that could close sooner than you expect.
Exploring Other Perspectives
One alternate view treats debt servicing as the real swing factor for Jardine Matheson Southeast Asia. The most cautious analysts were working with roughly flat revenue around US$20.7b and earnings of about US$1.2b by 2029, at a lower 8.0x P/E. Those assumptions pre date the special dividend, so their narrative may shift.
Explore 4 other Jardine Matheson Southeast Asia fair value estimates, including one that suggests as much as 7% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis.
- A great starting point for your Jardine Matheson Southeast Asia research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Jardine Matheson Southeast Asia. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Jardine Matheson Southeast Asia's overall financial health at a glance.
Looking for more investment ideas beyond Jardine Matheson Southeast Asia?
Once the Jardine Matheson Southeast Asia story is on your watchlist, it can help to line it up against a wider field of opportunities so you can judge income strength, balance sheet resilience, and potential mispricing side by side.
- For investors who care most about income durability, compare this special payout with other high yield opportunities using a focused 168 dividend fortresses.
- If capital preservation sits higher on your priority list, stress test Jardine Matheson Southeast Asia against a 227 resilient stocks with low risk scores that filters for resilience first.
- When you want to look beyond the usual large caps, broaden your watchlist with a 615 high quality undiscovered gems that surfaces under-the-radar businesses with strong fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com