
Waste Management (WM) Pulls Back As Undervaluation Claims Grow, Is It Cheap Or Fully Valued?
Recent Share Performance Context for Waste Management
Waste Management (WM) has drawn investor attention after a weaker run for the shares. The stock is down about 6% over the past month and roughly 11% over the past 3 months, based on the latest returns.
Despite the softer recent patch, Waste Management’s 1 year total shareholder return is down 5.4% while the 3 year total shareholder return is up 37.7%. This suggests long term holders have still seen meaningful gains even as near term momentum has faded around the current US$204.45 share price.
Compare Waste Management’s recent pullback with other resilient operators by scanning our 31 resilient stocks with low risk scores that have weathered similar swings without significantly changing their risk profiles.
Waste Management’s pullback and mixed return profile leave a simple fork in the road. Has most of the upside already played out, or does the recent weakness reset the valuation enough to keep potential gains ahead?
Most Popular Narrative: 21% Undervalued
Against the recent pullback, the most followed narrative values Waste Management at a fair value of about $259.92 compared with the last close at $204.45. This frames the current share price as a discount that depends on execution in several newer business lines.
The main thing that has to go right is that Waste Management turns its large investments in healthcare solutions, recycling automation and renewable natural gas into sustained cross sell, synergy capture and free cash flow conversion now that major capex is largely complete.
The current valuation implies the share price does not fully reflect a business that is growing operating EBITDA, expanding margins, lifting free cash flow conversion toward the high 40s% to low 50s% range and benefiting from scarce disposal and energy assets.
See why 90 investors see Waste Management as 21% undervalued.
Result: Fair Value of $259.92 (UNDERVALUED)
Still, if Stericycle synergies fall short or renewable natural gas economics shift with tax credit changes, the bullish Waste Management story could prove overly optimistic.
Find out about the key risks to this Waste Management narrative.
Another View On Waste Management’s Valuation
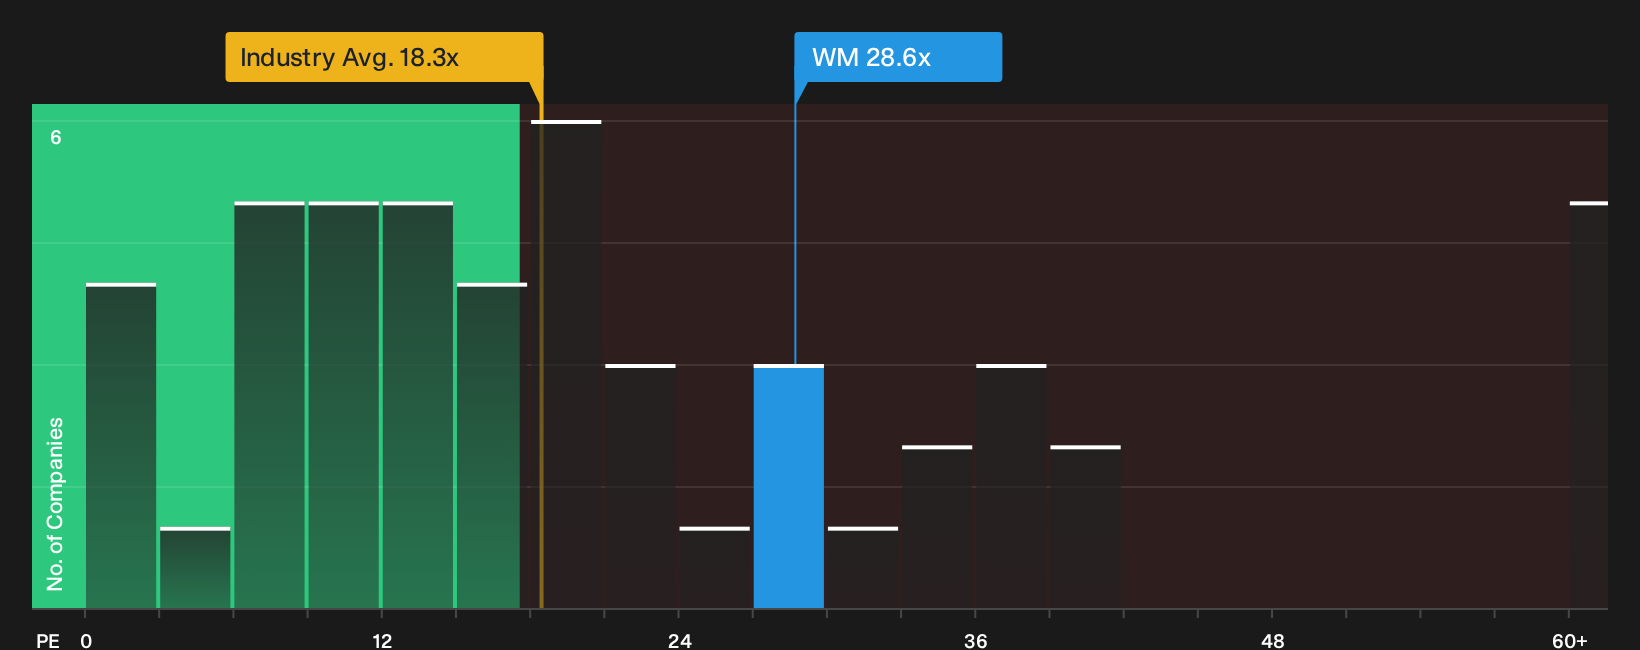
The first story presents Waste Management as about 21% undervalued relative to a fair value of $259.92. A simple earnings multiple sends a cooler signal. At a P/E of 28.6x, the stock trades richer than the US Commercial Services industry on 18.3x and above its own fair ratio of 26.6x, which points to some valuation risk if sentiment shifts.
So which matters more for you: the discount to cash flow estimates, or the premium to current earnings multiples on Waste Management’s shares?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Waste Management’s value story are clear. Act quickly, and stress test both the bullish and cautious angles against the 5 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Waste Management?
If Waste Management has you rethinking your next move, do not stop here. Broaden your watchlist with targeted ideas built from hard numbers, not headlines.
- Chase potential mispricing by scanning companies that look statistically cheap on quality and valuation using our 31 high quality undervalued stocks.
- Strengthen your income stream by checking out businesses screened for reliable payouts and higher yields through the 7 dividend fortresses.
- Protect your downside by focusing on financially resilient businesses that consistently pass balance sheet checks in our list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com