
3 Canadian Value Stocks To Own In October 2026
Rising US interest rates are putting global borrowing costs under the spotlight, and that includes Canadian markets where higher discount rates can quietly pull down valuations even when underlying businesses still generate solid cash. That gap between price and cash flow appeals to value hunters. This article walks through three Canadian stocks that screen as attractively priced on future cash generation and explains what their numbers might mean for long term investors.
The three stocks in this piece are just a starter set, and the full screen on Simply Wall St surfaced 5 more companies with equally compelling cash flow stories that are not covered below. To go straight to the source and identify candidates that look undervalued on discounted cash generation, head into the Undervalued Stocks Based On Cash Flows screener.
Groupe Dynamite (TSX:GRGD)
Overview: Groupe Dynamite is a women’s fashion retailer that designs and sells apparel and accessories through its Dynamite and Garage store and online network.
Operations: Groupe Dynamite generates about CA$1.49 billion in revenue from apparel retail, with roughly CA$578 million from Canada and CA$902 million from the United States.
Market Cap: CA$5.85 billion
Groupe Dynamite matters for a cash flow focused screen because its Garage and Dynamite banners convert everyday fashion spending into recurring operating cash across stores and e commerce.
"Rapid expansion in the United States and early traction in the United Kingdom, including Oxford Street and other prime centers, positions Groupe Dynamite to reach more higher income shoppers and tourists, which can support sustained revenue growth and higher sales per square foot."
What happens to margins and free cash flow will depend heavily on how one unseen pressure in its pricing power plays out.
That pressure point is exactly what the full narrative unpacks, so read the full narrative for Groupe Dynamite to see how pricing power and cash generation could decouple.
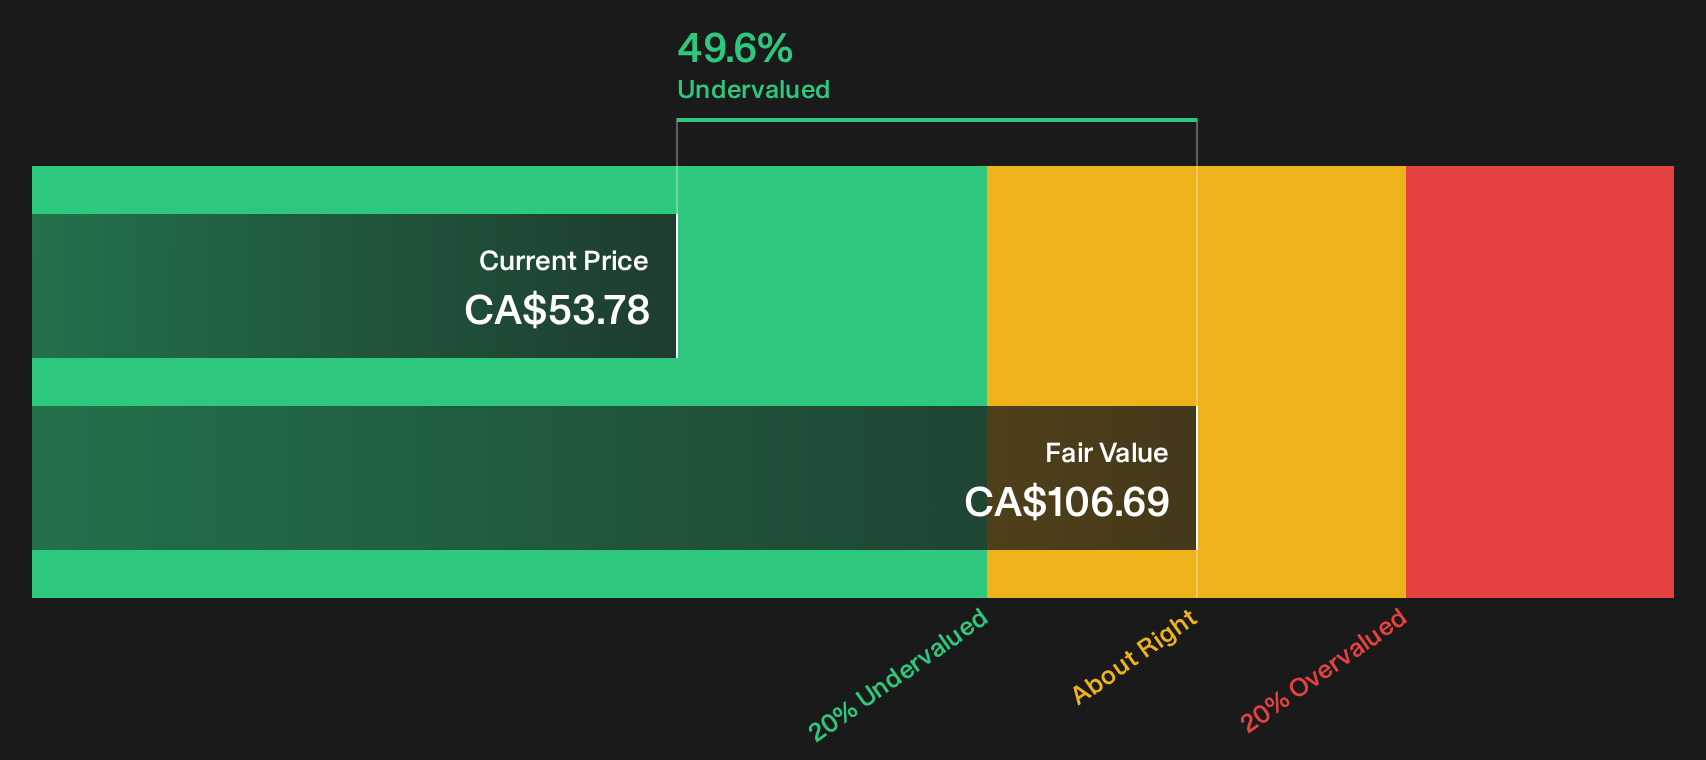
Suncor Energy (TSX:SU)
Overview: Suncor Energy is an integrated oil producer and refiner built around Canadian oil sands, where long life projects drive cash generation.
Operations: Suncor Energy records CA$26.9 billion from Oil Sands, CA$36.8 billion from Refining and Marketing, and CA$2.5 billion from Exploration and Production.
Market Cap: CA$116.0 billion
Suncor Energy interests value investors because the oil sands operations can generate meaningful operating cash that underpins the DCF case when pricing stays supportive.
"Reliance on very high utilization of existing oil sands and refining assets, including refinery runs consistently at or above 100% and upgrader utilization above 100%, leaves little unused capacity to offset unplanned outages, which could pressure volumes and compress margins if reliability slips from current record levels."
What happens to Suncor Energy cash returns will depend on whether one crucial operating constraint tightens or quietly loosens over time.
If that operating bottleneck is what could eventually separate routine cash returns from something stronger, the full narrative for Suncor Energy shows where Suncor Energy’s next leg of upside or strain might emerge.

Chemtrade Logistics Income Fund (TSX:CHE.UN)
Overview: Chemtrade Logistics Income Fund supplies industrial and water treatment chemicals across the Americas, with sulphuric acid products supporting steady cash generation.
Operations: Chemtrade Logistics Income Fund records about CA$738.5 million from Electrochemicals and CA$2.12b across Brazil, Canada, and the United States.
Market Cap: CA$1.6b
Chemtrade Logistics Income Fund matters for a cash flow focused screen because sulphur and water treatment chemicals often run on long term, usage based contracts that can feed relatively predictable cash streams into a DCF model.
"Chemtrade's expanding focus on water treatment solutions, reinforced by the Polytec and Thatcher acquisitions, has been described as positioning the company to benefit from persistently rising demand from municipalities and food processing industries, supporting durable revenue growth and improved earnings stability as water scarcity and regulatory pressures intensify globally."
What eventually happens to unit valuations will hinge on how one evolving pressure in these higher margin projects filters through long run free cash flow.
As that pressure builds around higher margin projects, read the full narrative for Chemtrade Logistics Income Fund to see whether Chemtrade Logistics Income Fund cash flows are quietly accelerating or at risk of stalling.

Seeking Fresh Alternatives Before They Fly
Fresh ideas move fast. Breakout stories gain momentum, slow movers get caught chasing entries, and quiet winners drop off the radar. Scan these under the radar themes to explore potential opportunities at an earlier stage.
- Identify companies generating strong cash flow with relatively low balance sheet stress by running the list of solid balance sheet and fundamentals (7 results) before the broader market fully reflects those characteristics.
- Track income-oriented stocks with comparatively high yields through the curated 1 dividend fortresses while those payouts may still be underfollowed and pricing remains relatively stable.
- Look for early infrastructure beneficiaries related to AI buildout by scanning the 90 AI infrastructure stocks while these companies operate with less attention than higher-profile names.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com