
Will Earnings Beat Change Paychex Stock Narrative (PAYX)
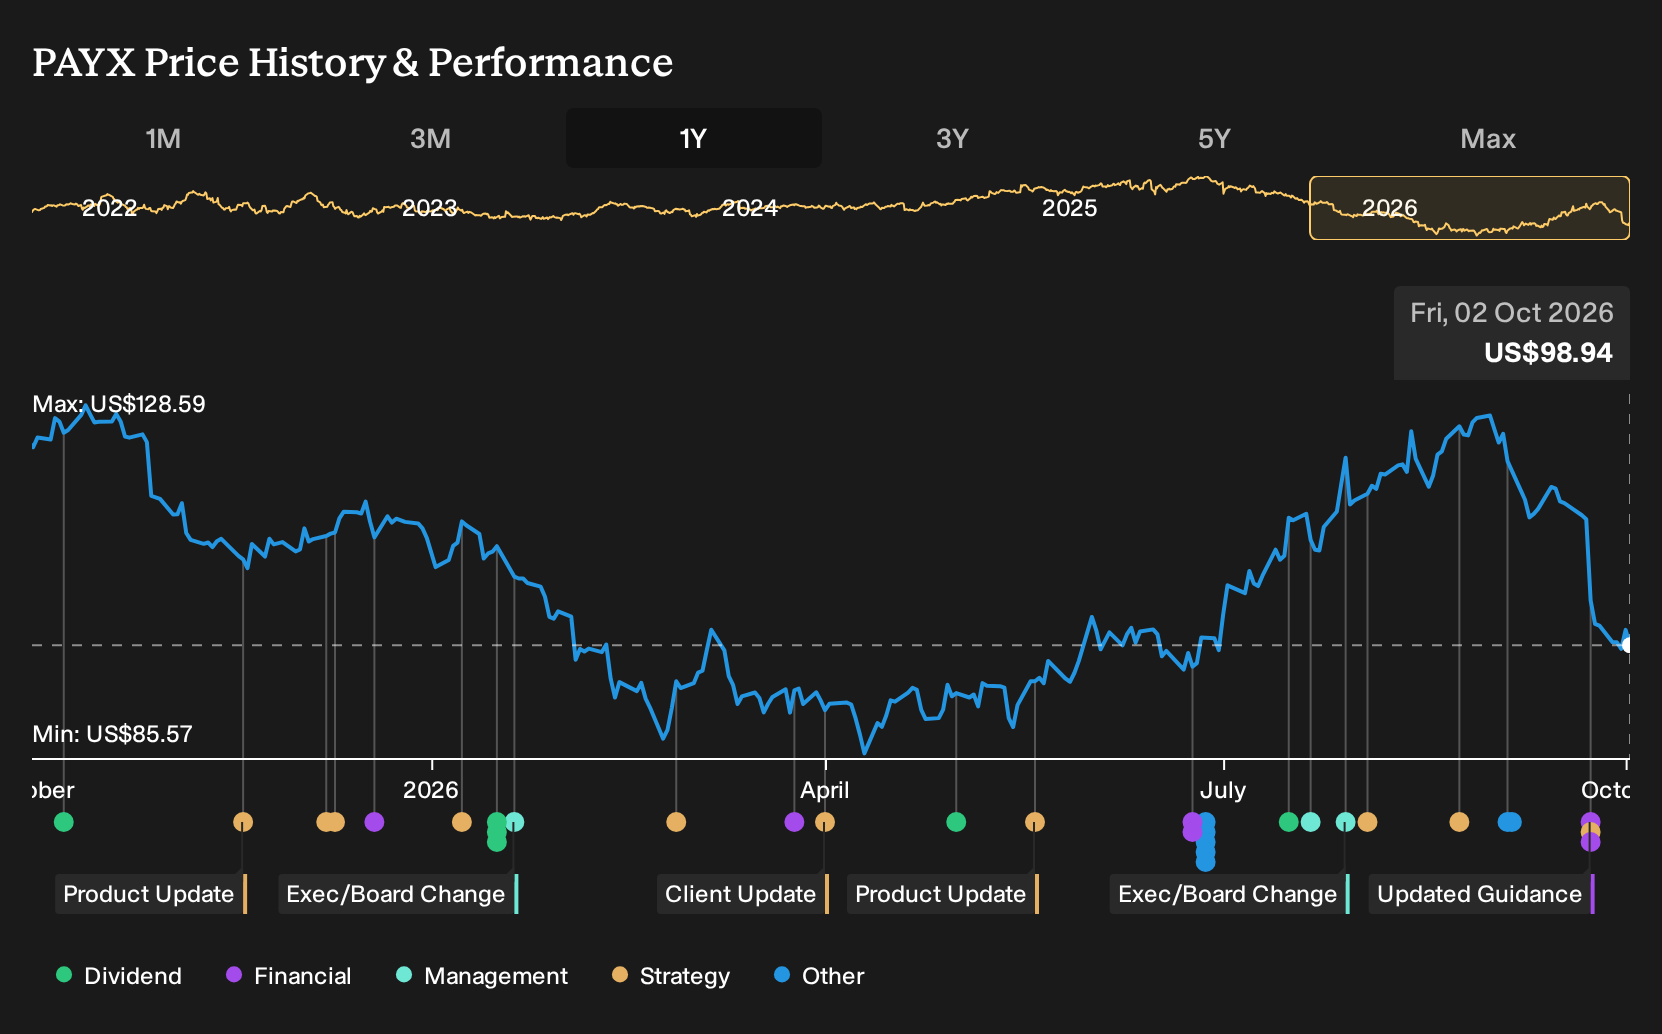
- Paychex reported first quarter fiscal 2027 results for the period ended August 31, 2026, with revenue of US$1,630.5 million, net income of US$429.7 million, and basic earnings per share from continuing operations of US$1.21. The company also provided fiscal 2027 revenue guidance targeting 5% to 6% growth.
- The business also launched WISE Hire, an AI-native recruiting solution available both as a standalone product and within its HCM platforms. WISE Hire embeds automation and candidate matching with human oversight, signaling continued focus on efficiency and value for employers rather than on balance sheet actions such as recent low share repurchase activity.
- We will now look at how Paychex's stronger earnings and new WISE Hire AI recruiting tool could reshape the existing investment narrative.
Scan how Paychex's AI hiring push and measured buyback activity compare with a curated group of workforce and automation plays in our 89 robotics and automation stocks.
Paychex Investment Narrative Recap
To own Paychex, you need to believe in a steady HCM operator that leans on AI, higher value PEO offerings, and the Paycor combination to support earnings over time. The latest quarter showed higher revenue and profit versus a year earlier, and management is guiding to 5% to 6% total revenue growth for fiscal 2027.
The near term pivot point is execution on AI products and client mix, while managing pressure from expected lower interest on client funds and slower Management Solutions growth. The absence of buybacks in the recent quarter does not materially change those operating drivers or the primary risk around Paycor and go to market integration.
The WISE Hire launch is the most relevant piece of recent news because it feeds directly into the existing WISE AI engine story. Paychex is rolling out an AI native recruiting tool that automates sourcing, screening, coordination, and scheduling. Human oversight is built into the workflow so employers still own the hiring decision.
For catalysts, WISE Hire sits on top of the same AI platform that has already reduced manual payroll work and error rates in pilots. If Paychex executes well, this kind of product can deepen client relationships, support the shift into richer PEO and advisory services, and partially offset risks from softer interest income and any integration friction with Paycor.
What The Analyst Playbook Implies For Paychex
Paychex's analyst model is built on a relatively measured top line assumption. Consensus points to revenue rising about 5.2% a year over the next 3 years, with profit margins moving from 27.4% today to 31.1% by around 2029 as WISE AI, PEO mix and Paycor integration feed through.
The same framework anchors on current earnings of about US$1.8b and a forecast consensus of US$2.4b by 2029, which implies an earnings increase of roughly US$600m. To line that up with the price targets, the group would be earning US$2.4b on about US$7.7b of revenue in 2029, with the stock trading on a P/E of 20.4x versus about 19.6x today and a sector multiple near 21.0x.
In addition, analysts plug in about a 1.09% yearly decline in share count and use a 7.6% discount rate to pull those future cash flows back into today's valuation work. That combination of modest revenue growth, rising margins and a slightly higher future P/E multiple is what underpins the current consensus price target range.
Paychex's narrative projects about US$7.7b of revenue and US$2.4b of earnings by 2029. This leans on 5.2% yearly revenue growth and roughly US$600m of earnings increase from about US$1.8b today.
Discover how Paychex's fair value indicates a 15% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts lean into Paychex’s AI push as a long term earnings driver. Before this WISE Hire launch and updated guidance, they were sketching out roughly US$7.7b of revenue and about US$2.5b of earnings by 2029. You can treat that as one possible path and compare it with more cautious views.
Explore 3 other Paychex fair value estimates, including one that suggests as much as 89% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Paychex research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Paychex. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Paychex's overall financial health at a glance.
Looking For More Paychex-Like Investment Ideas?
If Paychex fits the kind of business you want to study, it can help to compare it with other stocks that share similar financial traits. The Simply Wall St Screener lets you filter for exactly what you care about, whether that is resilience, value, or balance sheet strength.
- If capital preservation is high on your list, focus on steadier profiles by scanning a universe of 31 resilient stocks with low risk scores that may suit a more cautious style.
- For investors hunting for quality at a reasonable price, compare Paychex with a curated pool of 31 high quality undervalued stocks that pair stronger fundamentals with more modest pricing.
- When balance sheet strength matters most, line Paychex up against a list of solid balance sheet and fundamentals (25 results) to see which other companies match your standards on debt and liquidity.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com