
Ero Copper (TSX:ERO) Beat Q2 Estimates, Is The Stock Already Above Fair Value?
Q2 Earnings Surprise Puts Ero Copper in Focus
Ero Copper (TSX:ERO) moved onto more investor watchlists after reporting Q2 FY26 earnings per share ahead of market estimates, a result that often shifts attention to how the business is currently valued.
The Q2 beat landed on a stock that already had momentum, with a 90-day share price return of 44.29% and an 80.65% 1-year total shareholder return. Recent gains suggest investors are reassessing Ero Copper’s growth prospects and risk profile rather than reacting to a single quarter in isolation.
Scan how Ero Copper’s latest earnings surprise compares with other copper producers by reviewing the hand picked 16 top copper producer stocks that is now shaping sentiment across the materials sector.
After a 1 year total return of 80.65% and a recent Q2 surprise, Ero Copper now sits near analyst targets. Do you lean into the momentum, or wait for a pullback before committing fresh capital?
Most Popular Narrative: 3% Overvalued
Ero Copper last closed at CA$54.05, compared with a most followed fair value estimate of CA$52.30. This estimate is built on detailed long term earnings and cash flow assumptions using an 8.31% discount rate.
The ramp-up of higher-grade and lower-cost sources (notably Surubim's open-pit and Xavantina's newly mechanized stopes), combined with ongoing modernization at Pilar and strong balance sheet deleveraging, create a foundation for both near
and medium-term earnings accretion and free cash flow growth.
See why 31 investors see Ero Copper as 3% overvalued.
Result: Fair Value of CA$52.30 (OVERVALUED)
Still, the narrative can be shaken if Ero Copper faces further production guidance cuts or cost overruns on projects such as Tucumã and the Pilar shaft.
Find out about the key risks to this Ero Copper narrative.
Another View On Ero Copper’s Valuation
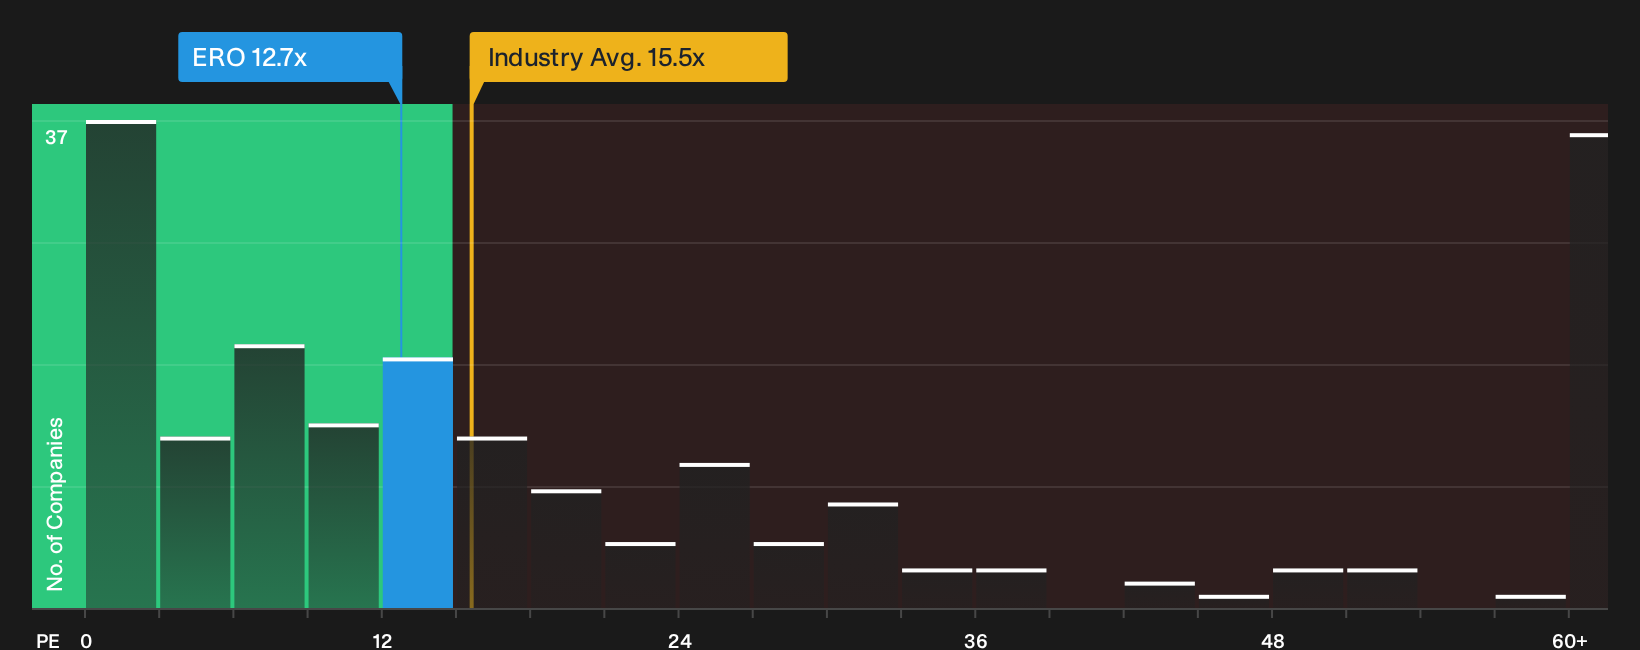
The fair value story for Ero Copper does not end with the analyst target of CA$52.30. On simple P/E math, the shares trade at 12.7x, which sits below peers at 14.6x and under a fair ratio of 14.5x that the market could move toward over time.
That gap points to a lower implied valuation risk if earnings hold up, since the stock already bakes in a cheaper multiple than both sector averages and the fair ratio. The open question for you is whether earnings quality and forecast growth justify that discount staying in place or narrowing.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Ero Copper are clear, with strong recent returns on one side and valuation questions on the other. Move quickly, review the underlying numbers, and weigh both the potential upside and the risks by checking the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Ero Copper?
You do not need to stop with Ero Copper. Use a few focused stock lists to pressure test your thinking and spot opportunities you might otherwise overlook.
- Target resilient balance sheets by reviewing the list of solid balance sheet and fundamentals (7 results), which filters for companies pairing financial strength with grounded fundamentals.
- Hunt for value opportunities through the 6 high quality undervalued stocks, which highlights businesses combining quality metrics with discounted pricing.
- Spot early stage potential by scanning the 18 elite penny stocks with strong financials to see which smaller companies already show promising financial traits.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com