
Enpro (NPO) Jumped, But What Is Catching Investors' Attention?
Enpro (NPO) trades around $332.56 after a solid year-to-date share gain of about 52%. The move comes as investors weigh its US$1.22b revenue base and exposure to semiconductor and industrial end markets.
Recent trading has been brisk, with a 5.27% 1-day share price return and 11.99% 30-day share price return signaling fresh momentum after a period in which the 90-day share price return declined 2.56%.
Scan other industrial and semiconductor exposed plays that are showing similar momentum to Enpro by using our curated 31 high quality undervalued stocks.
After a 52% YTD surge and strong earnings growth, Enpro now poses a straightforward question to investors: Does the current price still offer a favourable trade off between risk and potential reward?
Most Popular Narrative: 15% Undervalued
Against Enpro's last close at $332.56, the most widely followed valuation narrative pegs fair value at $389.50, implying a discount that hinges heavily on what its higher margin future could look like.
Continued portfolio transformation and disciplined capital allocation, including targeted organic investments, bolt-on acquisitions, and share repurchases, are expected to boost free cash flow, enhance return on invested capital, and support long-term EPS growth.
See why 2 investors see Enpro as 15% undervalued.
Resulting fair value estimates rely on an 8.48% discount rate and analysts' assumptions that Enpro can lift profit margins from 3.6% to 17.4% over time while growing revenue at about 9% a year. The gap between current earnings of $44.1 million and the projected $278.0 million by 2029 is large, so any shortfall in execution, especially in Advanced Surface Technologies, could weaken the case for that $389.50 figure.
Result: Fair Value of $389.50 (UNDERVALUED)
Still, Enpro's heavy spending on new capacity and its exposure to cyclical semiconductor and commercial vehicle markets could quickly test this upbeat valuation story.
Find out about the key risks to this Enpro narrative.
Another View: What Enpro's Sales Multiple Is Telling You
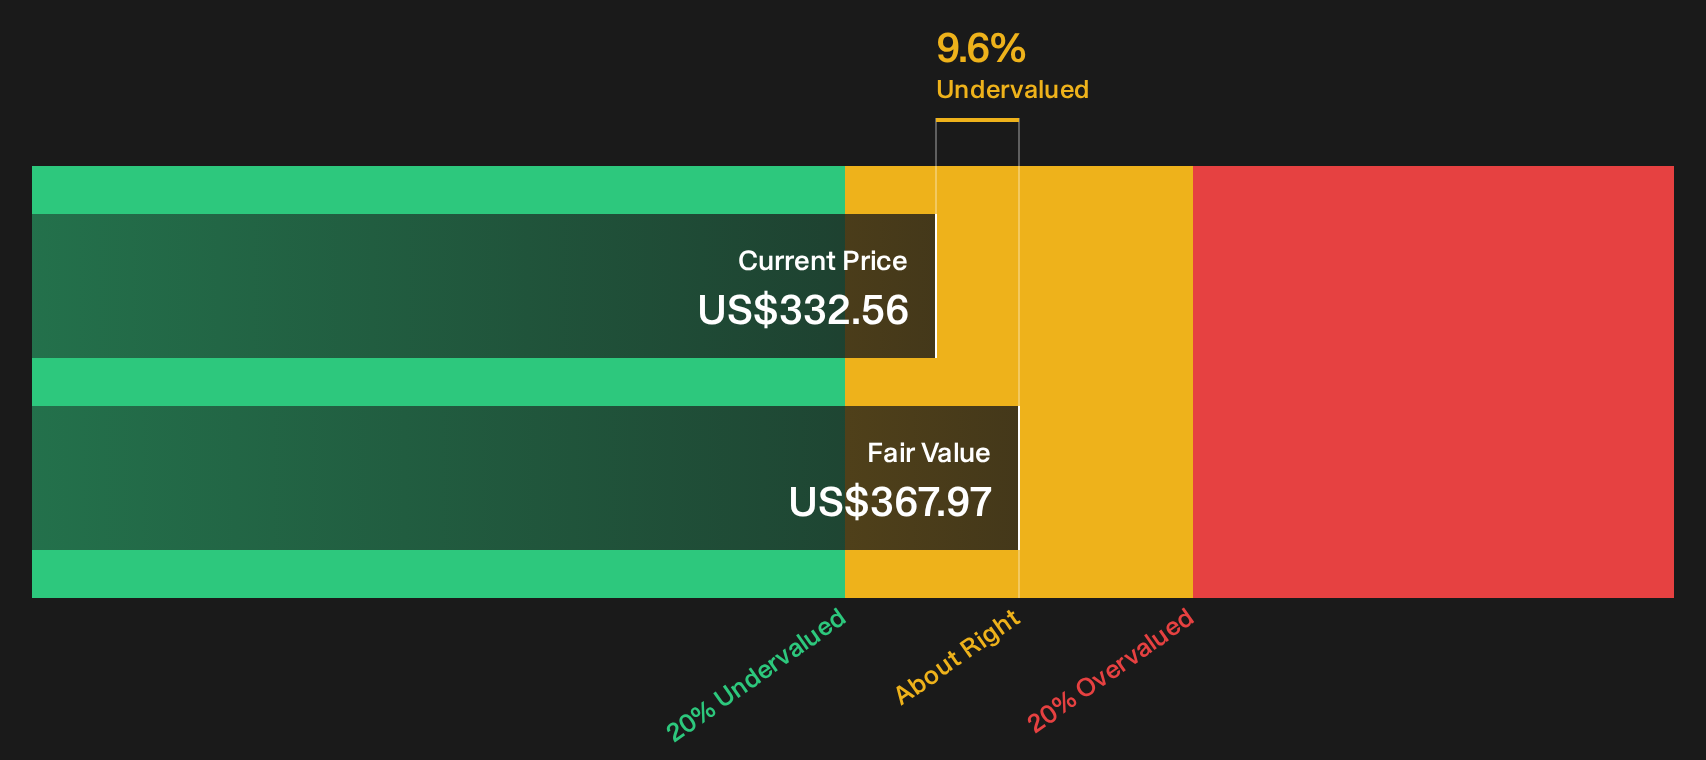
The SWS DCF work suggests Enpro is undervalued, trading at $332.56 versus an estimated future cash flow value of $367.97. Yet the P/S ratio paints a tougher picture, with the stock at 5.7x sales compared with a fair ratio of 2.8x and a US Machinery industry average of 2x. That kind of gap signals investors are already paying a heavy premium for the growth story, so it may be worth considering how comfortable you are with the earnings ramp implied in that price.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
If this mix of optimism and concern around Enpro feels familiar, consider acting while the details are fresh and stress test the thesis against the 2 key rewards and 2 important warning signs.
Looking for more Enpro-style investment ideas?
Do not stop at Enpro. Use this moment to widen your watchlist and compare what you see here with other opportunities lining up for fresh capital.
- Target robust cash generation and potential mispricing by scanning companies on our curated 31 high quality undervalued stocks.
- Prioritise resilience and balance sheet strength by running companies through the list of solid balance sheet and fundamentals (25 results).
- Hunt for under-followed opportunities by searching the 19 high quality undiscovered gems before others catch on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com