
Home BancShares (HOMB) Could Be 41% Below Fair Value Following Argus Hold Call
Argus move puts a spotlight on Home BancShares
Argus has shifted its view on Home BancShares (HOMB) to a HOLD rating, a change that highlights investor caution around regional banks and invites a closer look at the stock’s current setup.
Recent trading tells a mixed story for Home BancShares. The share price is US$28.67 after a 1-month share price return that declined 4.91% and a year to date share price gain of 2.72%. Total shareholder return over the past 3 and 5 years is 45.88% and 37.22% respectively, hinting that long term holders have seen materially stronger outcomes than short term traders facing recent sector caution.
Scan beyond Home BancShares and see how other regional financials are priced for caution or a rebound by reviewing our hand picked list of list of solid balance sheet and fundamentals (25 results).
Argus recently shifted its rating to HOLD while Home BancShares trades at US$28.67 compared with a US$33.25 target and a larger estimated intrinsic value gap. How far from fair value is this really?
Preferred P/E of 12x for Home BancShares: Is it justified?
On Simply Wall St’s SWS DCF model, Home BancShares screens as undervalued, yet the market is still pricing the shares at a P/E of 12x. That leaves you weighing a discounted cash flow view that points to upside against a more cautious earnings multiple that sits only a little below peer averages.
The P/E ratio compares the current share price with the last twelve months of earnings per share, so it anchors what investors are paying for each dollar of profit. For a regional bank like Home BancShares, this metric often reflects expectations around loan growth, credit quality, and the stability of funding rather than fast headline expansion.
Relative to an estimated fair P/E of 11.3x from the fair ratio framework, the current 12x looks slightly rich. The market is assigning a premium to the bank’s high quality earnings and 10.6% annual earnings growth over the past 5 years. That premium could narrow if growth tracks the 4% yearly pace that is currently forecast.
Peer comparisons tell a similar story. Home BancShares trades on a lower P/E than the peer average of 13.7x, which implies some restraint when set against similar banks, yet still carries a higher multiple than the broader US Banks industry at 11.6x. That combination points to a valuation that leans a bit expensive versus the fair ratio, even though it is not stretched against direct peers.
Explore the SWS fair ratio for Home BancShares.
Result: Price-to-earnings of 12x (OVERVALUED)
Still, the story for Home BancShares could change quickly if credit quality weakens or if funding costs rise and put more pressure on those recently reported earnings trends.
Find out about the key risks to this Home BancShares narrative.
Another View on Home BancShares valuation
The P/E story for Home BancShares points to a slight premium. The SWS DCF model sends a very different signal. On that framework, HOMB at US$28.67 is trading below an estimated future cash flow value of US$48.97, which screens as undervalued and raises questions about how patient investors want to be.
Look into how the SWS DCF model arrives at its fair value.
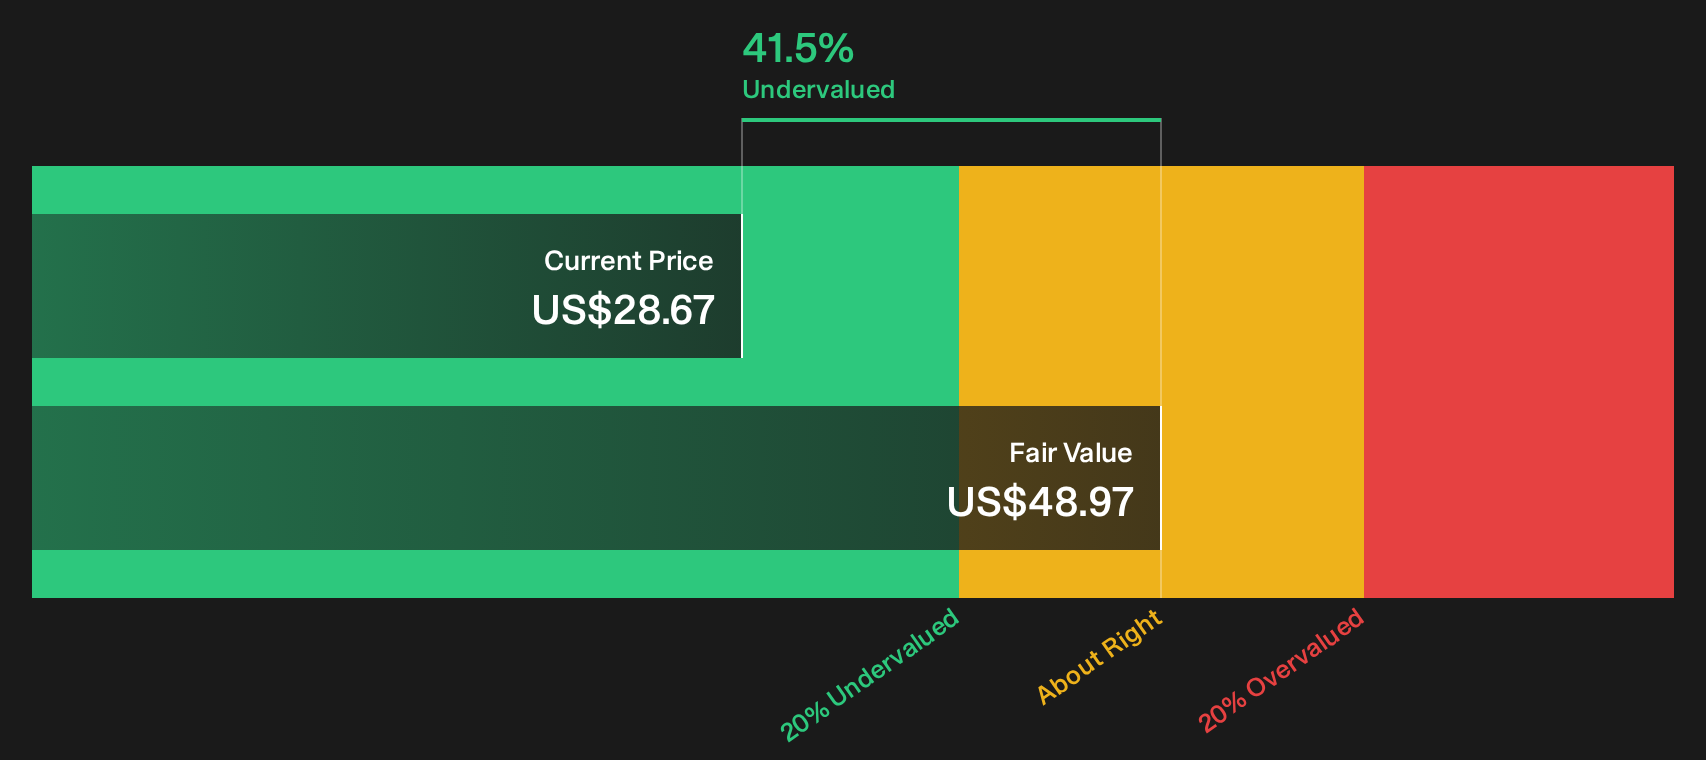
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Home BancShares for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Home BancShares valuation and risk profile can cut both ways, so move quickly to review the evidence and shape your own stance with the full breakdown of 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Home BancShares?
If Home BancShares has sparked your interest, do not stop here. Broaden your watchlist using focused stock ideas that match different investing goals and risk levels.
- Target potential mispricing by reviewing a curated set of companies that look attractively valued on both quality and price using our 31 high quality undervalued stocks.
- Lock in income-focused opportunities by scanning for reliable payers and higher yields across our hand picked group of 7 dividend fortresses.
- Dial back risk without stepping completely to the sidelines by filtering for businesses flagged in our resilient, lower risk universe of 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com