
ALK-Abelló (CPSE:ALK B) Expands Catalent Deal, Is The 32% Undervaluation Case Convincing?
ALK-Abelló (CPSE:ALK B) has just expanded its long-running manufacturing partnership with Catalent, securing access to Zydis tablet technology and a substantial increase in future capacity for its allergy treatments.
Against that backdrop, ALK-Abelló’s share price has been under pressure, with a 90-day share price return down 16.56% and the year-to-date share price return down 11.03%. The 1-year total shareholder return is down 3.91%, but the 3-year total shareholder return is up 144.89%. This suggests that longer term holders have still seen very strong gains even as shorter term momentum has faded and fresh news like the Catalent capacity deal and recent leadership changes reshape how investors weigh its future growth potential and execution risk.
Spot under-pressure stories like ALK-Abelló early, then compare them with other resilient healthcare and pharma plays using our hand picked 227 resilient stocks with low risk scores.With ALK-Abelló’s share price under pressure despite the Catalent capacity deal and solid recent growth in revenue and net income, the key question now is whether to lean into this weakness or wait for a cheaper entry as the valuation picture comes into focus.
Most Popular Narrative: 32% Undervalued
Against ALK-Abelló’s last close of DKK201.60, the most followed narrative pegs fair value at DKK297.50. This frames the recent share price weakness in a very different light for patient allergy-immunotherapy investors.
ALK's strong pipeline progress (for example, accelerating Phase II/III trials in peanut allergy and ongoing geographic expansion into Japan and China) leverages long-term trends in personalized and preventive medicine, increasing the likelihood of future product portfolio expansion, revenue diversification, and long-term earnings growth.
See why 21 investors see ALK-Abelló as 32% undervalued.
Result: Fair Value of DKK297.50 (UNDERVALUED)
Still, ALK-Abelló’s heavy reliance on a narrow allergy portfolio, along with higher planned R&D and capacity spending, could pressure margins if product uptake or pricing disappoints.
Find out about the key risks to this ALK-Abelló narrative.
Another View on ALK-Abelló’s Valuation
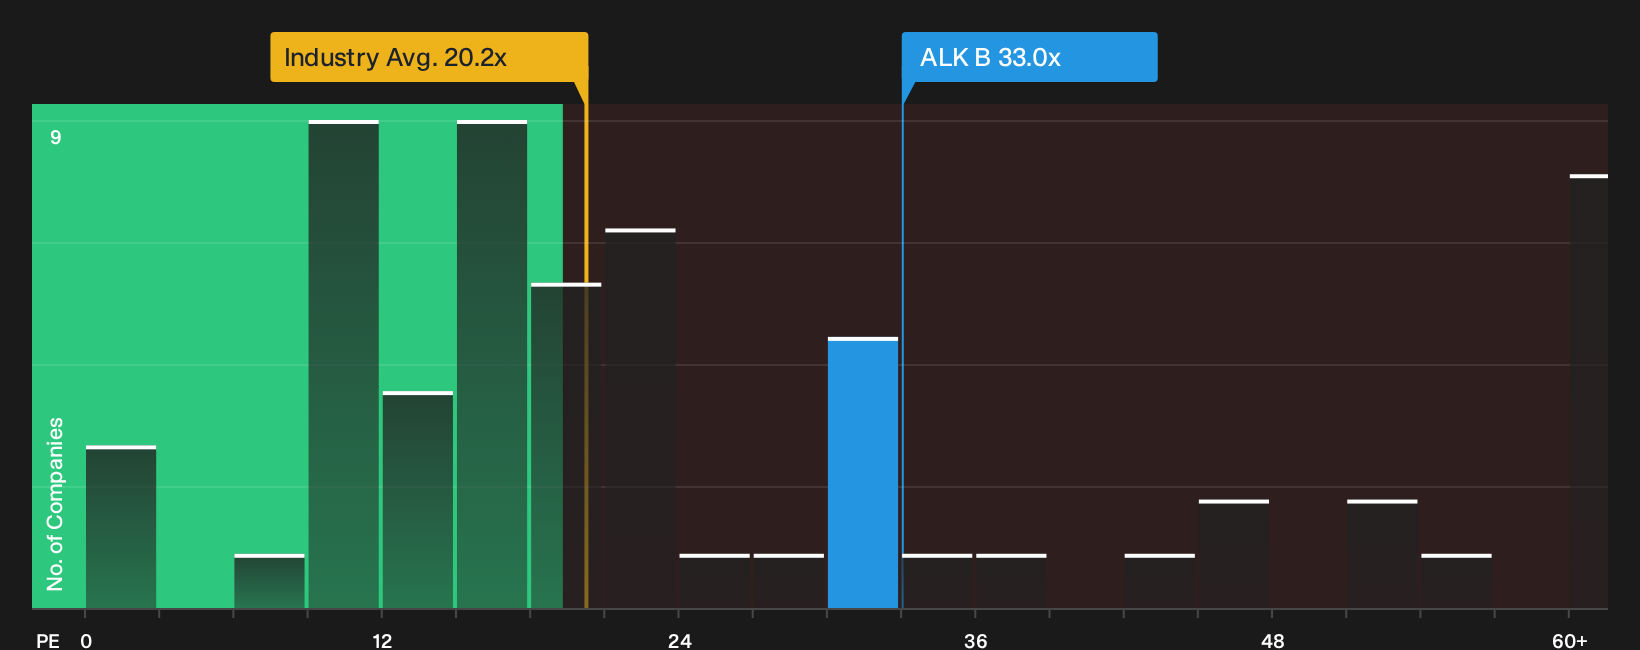
The fair value narrative points to DKK297.50, yet the current P/E of 33x tells a different story. That ratio sits well above the European pharmaceuticals average of 20.2x, the peer average of 14.2x, and even the 20.6x fair ratio that the market could gravitate toward over time.
If sentiment shifts closer to that fair ratio, the gap between today’s multiple and those lower benchmarks could matter more than any single price target when you think about upside and downside risk.
For a closer look at how the numbers line up against earnings power, explore the valuation breakdown in our detailed comparison and then decide which signal you want to trust in your own work on ALK-Abelló, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on ALK-Abelló so far, with rich multiples on one side and an undervaluation narrative on the other, so move quickly and pressure test the optimism by reviewing the 3 key rewards.
Looking for more investment ideas beyond ALK-Abelló?
If ALK-Abelló has your attention, do not stop here. Broader idea sourcing can sharpen your judgment and highlight better risk and reward tradeoffs.
- Spot potential bargains early by scanning a curated pool of quality stocks that may trade below their estimated worth using the 192 high quality undervalued stocks.
- Prioritise resilience first and hunt for companies with strong balance sheets and solid fundamentals through the list of solid balance sheet and fundamentals (206 results).
- Target cash returns by focusing on businesses that offer higher dividend yields with more defensive profiles using the 168 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com