
Did Special Call Plans Just Shift Pinnacle West Capital's (PNW) Investment Narrative?
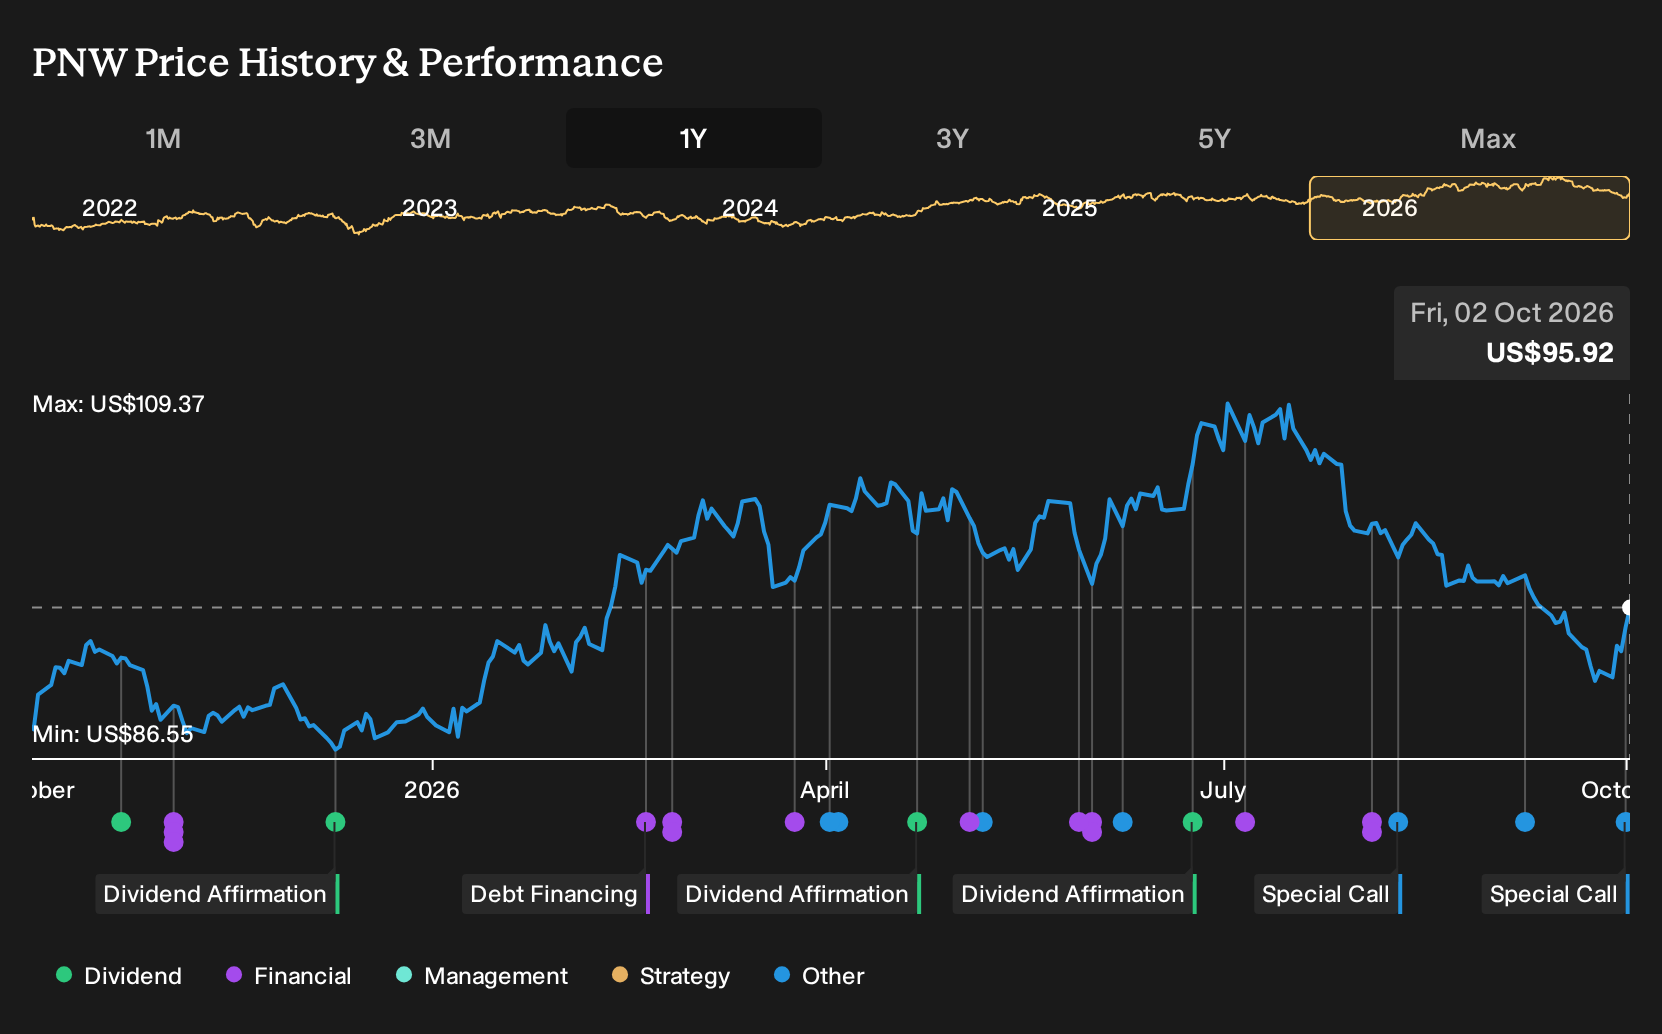
- Pinnacle West Capital recently held a special call, signaling that management wanted to address investors directly about upcoming developments in the business.
- The decision to convene a special call highlights how management communication can shape expectations around capital plans, regulatory progress, and load growth execution.
- We will look at how Pinnacle West Capital’s investment narrative intersects with the new special call focus on upcoming business updates.
Scan how Pinnacle West Capital’s special call fits into the wider utilities story by lining it up against 40 power grid technology and infrastructure stocks that are poised for the next leg of grid and infrastructure investment.
Pinnacle West Capital Investment Narrative Recap
To own Pinnacle West Capital, you need to be comfortable with a regulated utility that leans heavily on Arizona load growth and a multi year build out of generation and transmission. The key belief is that customer and usage growth, including large industrial projects, will keep filling that capacity pipeline in a way that supports earnings and the regulated asset base.
At present, the main short term swing factor is execution on that almost US$7.95b 2026 to 2028 capital program, together with regulatory outcomes that support timely cost recovery. A major risk is funding that build with higher cost debt and equity while interest coverage is already tight. This can pressure returns even if volumes remain healthy. The special call itself does not yet appear to be a material change to that core equation.
The special call focuses more attention on how Pinnacle West Capital is pacing large projects such as Redhawk, Agave, Ironwood, Sundance and the planned Cholla gas conversion. These projects are central to meeting more than 4,500 MW of committed large load and over 1 GW tied to TSMC, and they feed directly into future rate base growth.
Investors are likely to listen closely for clarity on capital timing, regulatory filings and any signals around the potential Four Corners to Cholla transmission line, which could approach US$1b. Clearer milestones on these items can help you assess whether strong Arizona demand and lower O&M in early 2026 are sufficient to offset higher interest expense, heavier depreciation and the pressure from interest payments that are not well covered by earnings.
Pinnacle West Capital Analyst Expectations In Focus
Pinnacle West Capital now comes with a fairly tight analyst script. The consensus view is built around revenue expanding by 4.9% a year over the next 3 years and profit margins moving from 11.5% today to 13.3% by 2029. In simple terms, the story is that a larger grid and a fuller network of high usage customers could lift both the top line and the share of each dollar that drops to the bottom line.
On earnings, analysts see profit moving from US$640.1m today to US$851.7m by 2029. That implies an increase of about US$211.6m over the period, which is a sizeable jump for a regulated utility and relies on both capital spending and regulatory outcomes working roughly as planned. The same forecast pins earnings per share at US$6.36 by around September 2029, with relatively little disagreement across the analyst set.
Pinnacle West Capital's narrative projects US$6.4b revenue and US$851.7m earnings by 2029. This assumes 4.9% yearly revenue growth and an earnings increase of roughly US$211.6m from current earnings of US$640.1m.
Valuation work around the stock ties these earnings and revenue paths to specific trading assumptions. The current market price of about US$93.31 compares against a consensus target of US$105.46, with individual analyst views stretching from US$87.00 to US$129.00. To land near that central target, the shares would need to trade on about 19.2x the 2029 earnings estimate, compared with a P/E of 17.7x today and around 19.9x for the broader US electric utilities peer group.
This framework gives you a checklist to hold against the upcoming special call. If you think revenues can plausibly reach around US$6.4b by 2029, earnings can get to roughly US$851.7m and a 19.2x P/E feels acceptable for a regulated utility with this mix of growth and risk, then the analyst narrative may feel reasonable. If you are more cautious on execution, regulatory treatment or future funding costs, the same numbers can look demanding and the call becomes a chance to test where your own expectations differ.
Uncover why Pinnacle West Capital's fair value indicates a 10% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The Simply Wall St Community only supplies two fair value views on Pinnacle West Capital, stretching from about US$89.39 to US$105.46, so opinions already differ meaningfully. Set those against the capital heavy build out and higher debt costs, and your own stance on earnings resilience and stranded asset risk will probably drive which camp you lean toward.
Explore another Pinnacle West Capital fair value estimate, including one that suggests there may be as much as 10% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Pinnacle West Capital research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Pinnacle West Capital. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Pinnacle West Capital's overall financial health at a glance.
Looking For More Investment Ideas Beyond Pinnacle West Capital?
If Pinnacle West Capital helps frame how a regulated utility story can play out, it can also be useful to compare it with other businesses that fit different risk and income profiles. The Simply Wall St Screener gives you an efficient way to line up alternatives that match your preferred mix of balance sheet strength, income potential and long term compounding.
- If capital preservation sits high on your list, start with a basket of resilient companies by reviewing 31 resilient stocks with low risk scores which prioritise stability and lower risk scores.
- If income is your focus, you can size up potential cash generators by scanning 7 dividend fortresses which target yields of 5% or more.
- If you want to back under followed opportunities with solid fundamentals, run your eye over 19 high quality undiscovered gems which combine quality metrics with relatively limited market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com