
Is Dividend Hike Altering The Investment Case For BancFirst (BANF)?
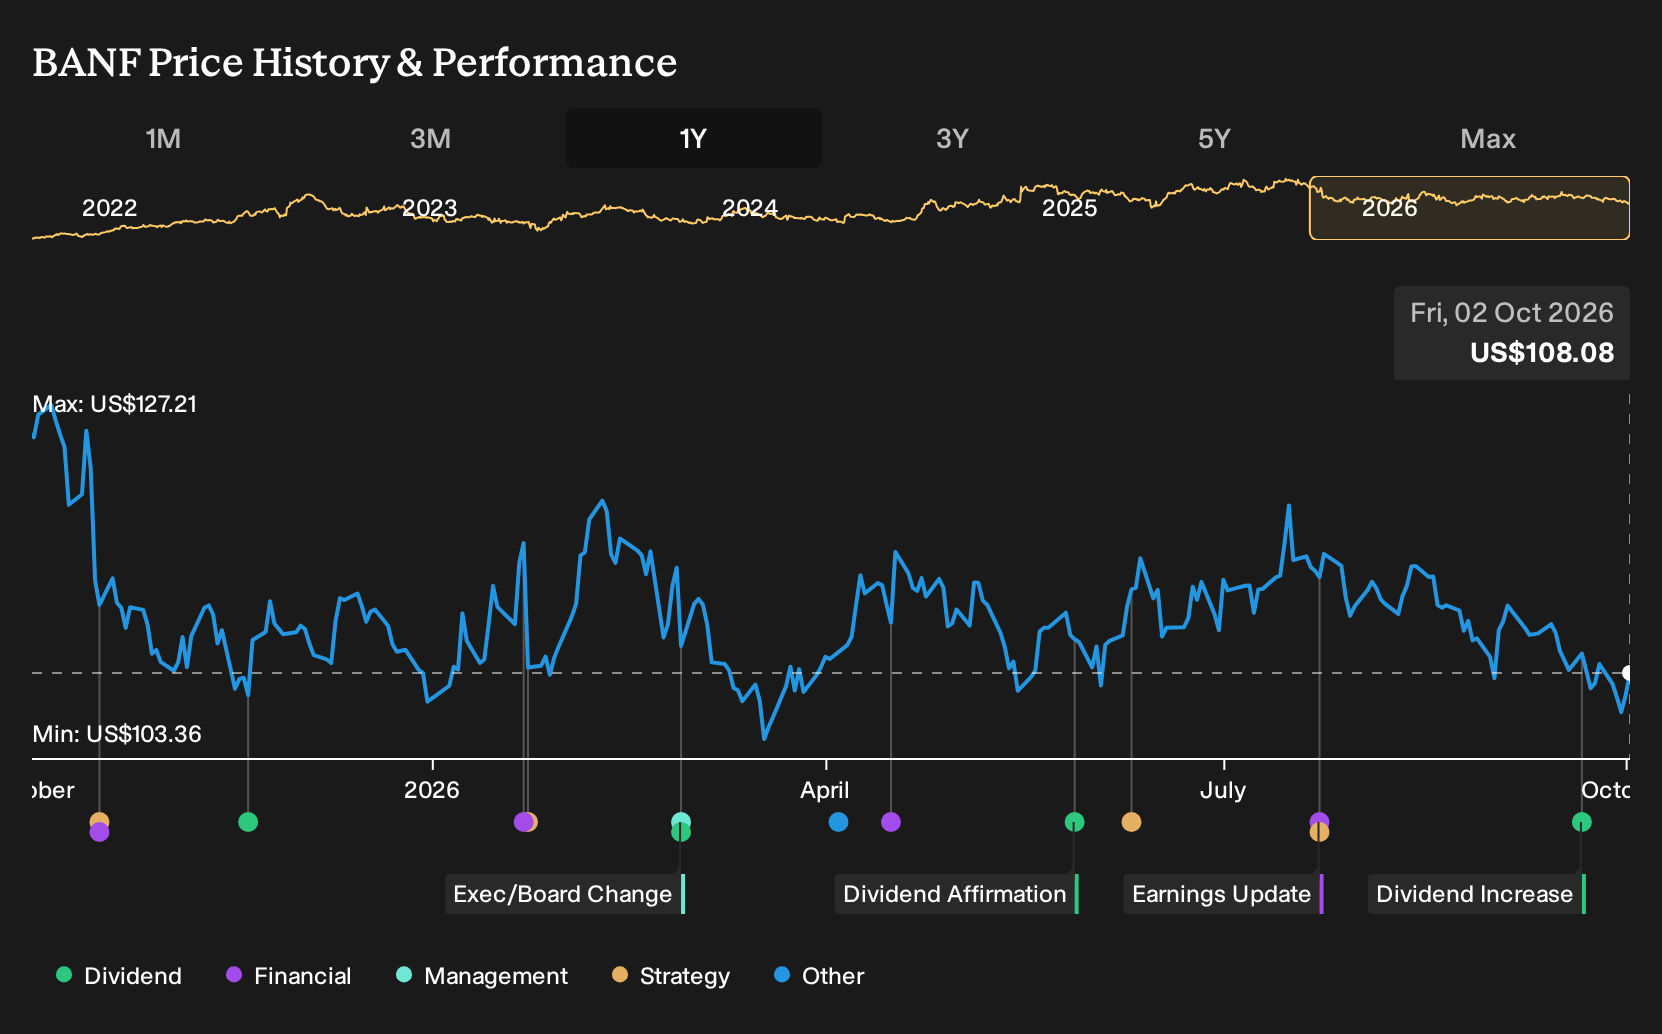
- BancFirst Corporation previously announced a higher regular quarterly cash dividend of US$0.52 per share, with an ex dividend and record date of 30 September 2026 and payment scheduled for 15 October 2026.
- The richer payout reflects management’s emphasis on consistent cash returns, alongside BancFirst’s focus on integrating Tulsa acquisitions and supporting capital strength.
- This article will explore how BancFirst’s higher US$0.52 quarterly dividend may influence the existing investment narrative around profitability and growth.
Scan beyond BancFirst and see how other income focused stocks are positioning their payouts today by running through our curated 7 dividend fortresses
BancFirst Investment Narrative Recap
BancFirst appeals to shareholders who want a conservative regional bank that leans on solid capital, steady fee income and a long record of profitability. To stay comfortable, you need to believe management can keep integrating Tulsa acquisitions while handling slower forecast revenue and earnings growth without letting efficiency slip too far.
The higher US$0.52 dividend fits that income first story but does not rewrite the near term drivers. The key near term swing factor remains how well loan growth, deposit mix and non interest income offset pressure on the net interest spread. The main risk is that mediocre revenue growth and a weaker efficiency ratio compress returns.
The latest US$0.52 quarterly dividend increase is the clearest recent signal relevant to this catalyst and risk mix. A higher payout leans on BancFirst’s strong capital position and history of reliable distributions, and it aligns with commentary that the dividend is attractive at about 1.92%.
For you as a holder, the question is whether this richer check is being funded alongside enough reinvestment into Tulsa integration, technology and cost control. If earnings growth continues to trail the wider US market while the stock trades on a premium P/E to banks, any disappointment on margins or fee income could matter more than the extra dividend.
What BancFirst’s Dividend Sits On Top Of
BancFirst's dividend story only really makes sense once you layer it over the analyst growth grid. The firm is modeled to grow revenue by 7.0% per year over the next few years, while profit margins are expected to ease from 35.3% today toward 32.8% in 3 years. Current earnings are put at US$251.8 million, with consensus pointing to US$286.7 million by about 2029, which is an increase of roughly US$35 million. On those forecasts, the business would be generating US$874.9 million in revenue and US$286.7 million in profit by 2029, with analysts using that endpoint to anchor fair value work.
Uncover why BancFirst's fair value indicates a 15% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster tightly at about US$124.33 per share, so retail views here are unusually aligned. Those opinions pre date the latest US$0.52 dividend move and Tulsa consolidation steps, so you should weigh them against current growth expectations, margin risks and capital strength before deciding how BancFirst fits your income plan.
Explore another BancFirst fair value estimate, including one that suggests it could be worth just $124.33.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your BancFirst research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for BancFirst. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BancFirst's overall financial health at a glance.
Looking For More Ideas Beyond BancFirst?
If you want to put BancFirst in context and stress test your income or total return plan, it can help to line it up against other stocks with different risk and payout profiles. The Simply Wall St Screener lets you quickly sort through companies by balance sheet strength, valuation and dividend focus so you can build a shortlist that matches how you actually invest.
- If capital preservation sits high on your list, filter for steadier businesses with 31 resilient stocks with low risk scores that may better match a cautious profile.
- For investors hunting for quality at a reasonable price, scan through 19 high quality undiscovered gems that combine solid fundamentals with limited current attention.
- Income focused portfolios can be rounded out by reviewing list of solid balance sheet and fundamentals (25 results) to find payers whose distributions rest on stronger financial footing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com