
What Just Happened With National Bank Holdings (NBHC)?
National Bank Holdings (NBHC) moved back into focus after the bank raised its equity repurchase authorization to US$40.1 million on 30 September 2026, prompting fresh questions about capital priorities and valuation.
At a share price of US$38.06, National Bank Holdings has seen short term momentum soften, with the share price down 9.5% over the past 30 days and 14.2% over 90 days. Total shareholder return sits at 2.6% over one year and 35.6% across three years, suggesting the buyback increase lands against a backdrop of weaker recent sentiment but still constructive longer term outcomes for investors who have held through the past few years.
See how National Bank Holdings compares with other banks returning cash to shareholders by checking our curated list of 7 dividend fortresses.
The higher repurchase pool at National Bank Holdings sits awkwardly against a sliding share price. Is management signaling confidence in the franchise, or is the market assigning a cheaper tag for a specific reason as valuation comes into focus next?
Most Popular Narrative: 21% Undervalued
With National Bank Holdings trading at $38.06 against a widely followed fair value estimate of $48.25, the current share price sits well below that narrative anchor and puts the new buyback authorization in a very different light for anyone focused on valuation and capital returns.
The successful launch of the 2UniFi platform, with positive early feedback and plans for further feature expansion (including fee-based membership offerings and integrated fintech services for SMBs), positions the company to capitalize on the shift toward digital banking and technology-driven financial solutions, potentially driving incremental noninterest income and expanding high-margin fee revenue streams.
See why 4 investors see National Bank Holdings as 21% undervalued.
Result: Fair Value of $48.25 (UNDERVALUED)
Still, the narrative can unravel quickly if regional concentrations in sectors like trucking and commercial real estate bite, or if 2UniFi adoption stalls and drags on fee income.
Find out about the key risks to this National Bank Holdings narrative.
Another Angle On National Bank Holdings’ Valuation
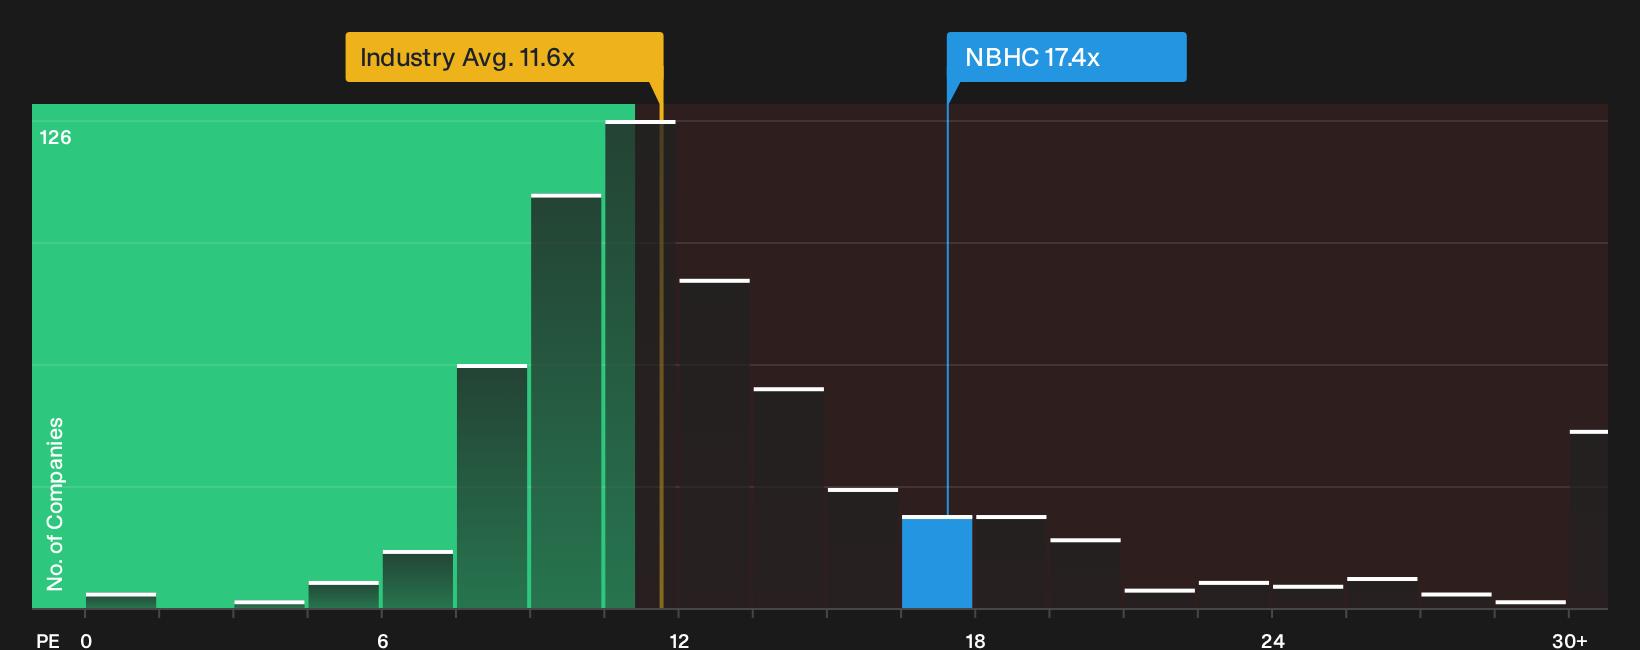
The story shifts once the focus moves from DCF and fair value estimates to what National Bank Holdings actually costs today. At a P/E of 17.4x, the stock trades above both the US Banks industry at 11.6x and its own fair ratio of 16.6x. This points to less margin for error if earnings underwhelm.
That gap raises a simple question for investors. Is the richer multiple a sensible premium for the National Bank Holdings narrative, or a sign that expectations may already be running ahead of reality, at least relative to peers and the fair ratio our models point to?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals and competing storylines around National Bank Holdings only matter if you use them. Act now by weighing the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond National Bank Holdings?
If National Bank Holdings has sharpened your focus on quality and price, do not stop here. Use the Simply Wall Street Screener to uncover complementary ideas that match your style and risk tolerance.
- Target potential upside by scanning for companies our models flag as mispriced using the 31 high quality undervalued stocks.
- Prioritise resilience by filtering for businesses with strong financial footing through the list of solid balance sheet and fundamentals (25 results).
- Get ahead of the crowd by spotting promising smaller opportunities with the 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com