
Skyworks Solutions (SWKS) Following Russell Index Removal Still Looks Pricey On Fair Value
Why Skyworks Solutions Is Back In Focus After Index Changes
Skyworks Solutions (SWKS) has just been removed from several Russell defensive and value indices, a technical reshuffle that can prompt mechanical selling or buying as index-tracking funds adjust their portfolios.
For individual investors, that kind of benchmark exit often raises practical questions. You are not looking at a change in the underlying semiconductor business on that date, but at a rules based index decision that influences which institutions hold the shares.
Index removal is landing in the middle of a sharp rebound for Skyworks Solutions, with a 30-day share price return of 14.87% and a 90-day gain of 37.34%. At the same time, the 5-year total shareholder return is down 39.13%, suggesting momentum has recently been rebuilding while longer term holders remain under water.
Compare Skyworks Solutions with a curated group of hardware and chipmakers that could be setting up their next move using our 90 AI infrastructure stocks as a starting universe.
After a near 37% rebound in 90 days but a 5 year return that is still down more than 39%, is Skyworks Solutions now skewed toward upside potential or downside risk on valuation grounds?
Most Popular Narrative: 24% Overvalued
At a last close of $85.03 versus a narrative fair value of $68.35 using an 11.47% discount rate, Skyworks Solutions screens as priced for optimism and leaves less room for error if expectations slip.
The planned Qorvo merger is framed around creating a combined mobile business of roughly US$5.5b and a non mobile business of about US$2.5b to US$2.6b, together with at least US$500m of cost synergies over 24 to 36 months and a long term model of 50% to 55% gross margin and 30% to 35% operating margin. This could materially lift net margins and earnings power that current pricing may assume will be delivered in full.
See why 54 investors see Skyworks Solutions as 24% overvalued.
Result: Fair Value of $68.35 (OVERVALUED)
Still, two pressure points could flip the Skyworks Solutions story quickly: the heavy reliance on a single mobile customer and any stumble on Qorvo merger synergies.
Find out about the key risks to this Skyworks Solutions narrative.
Another View On Skyworks Solutions Using Market Ratios
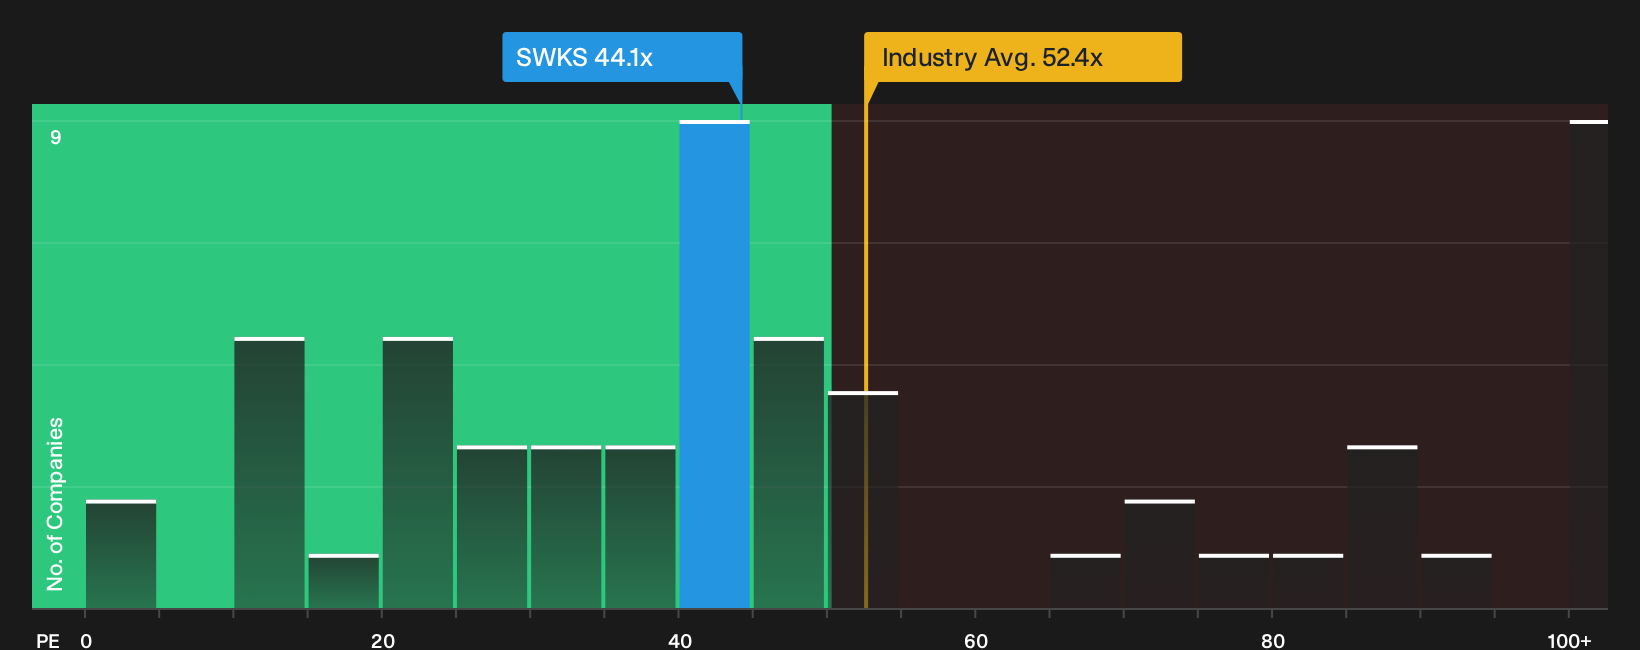
The narrative fair value of $68.35 paints Skyworks Solutions as overvalued, but the P/E story is more mixed. The stock trades on 44.1x earnings, below the US Semiconductor average of 52.4x and peer average of 58.1x, yet well above a fair ratio of 26.1x that the market could move toward. Is that a safety margin or a warning sign if sentiment cools?
To see how this pricing gap plays out in practice, including what a reversion toward the fair ratio could mean for your risk and return expectations, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Skyworks Solutions so far. If you want to move quickly and build your own stance on that balance of concern and optimism, start by weighing the 2 key rewards and 1 important warning sign.
Looking for more Skyworks Solutions investing ideas?
If Skyworks Solutions has you rethinking your watchlist, do not stop at one ticker. Broader idea hunting can sharpen your sense of price, quality, and risk.
Use the Simply Wall St Screener to quickly compare fresh ideas that fit your style so you are not relying on one stock to do all the work.
- Target potential mispricing by scanning a 31 high quality undervalued stocks that combines stronger fundamentals with more appealing entry points.
- Anchor your income plan around a 7 dividend fortresses built on higher yields that still prioritise resilience.
- Sleep easier by focusing on a 31 resilient stocks with low risk scores that keeps balance sheets and risk scores front and centre.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com