
How New Mass Spectrometry Workflows Will Impact Bruker Stock (BRKR)
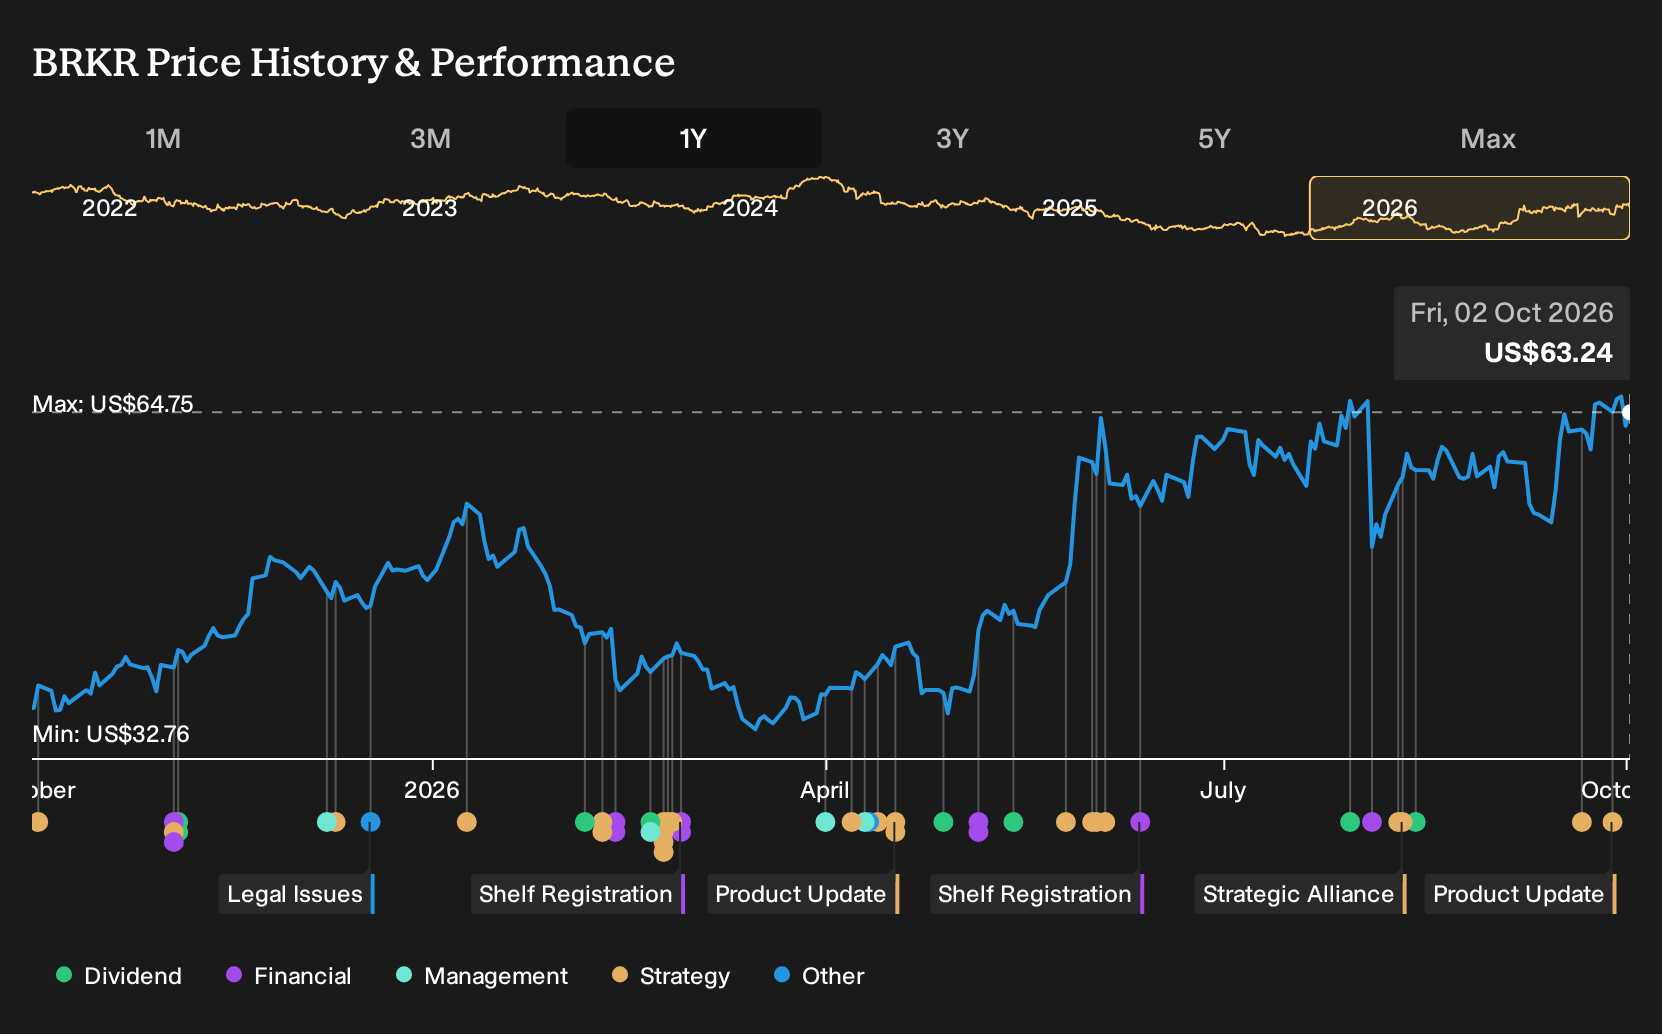
- In late September 2026, Bruker announced new timsUltra AIP and timsOmni workflows that expand mass spectrometry use across proteomics, glycoproteomics, structural biology and oligonucleotide analysis, alongside a US$6 million plus multi system NMR order from UC Berkeley.
- The multi enzyme dia PASEF methods and ProteoScape links between discovery and targeted assays point to deeper integration of Bruker hardware, software and workflows in high value research and biopharma applications.
- This article examines how Bruker's investment narrative relates to the new timsUltra AIP workflows and expanded proteomics capabilities.
Scan beyond Bruker and see how other research tools specialists could benefit from similar momentum by reviewing our curated list of 19 high quality undiscovered gems in advanced life sciences and lab equipment.
Bruker Investment Narrative Recap
To own Bruker, you need to believe the life science and deep tech tools portfolio can turn current unprofitability into sustained earnings while cost cuts and restructuring land as planned. The key near term swing factor is whether organic demand in research, biopharma and semiconductor metrology holds up well enough for management to hit its margin expansion ambitions.
The main risk has not changed. Revenue previously came in at the low end of internal goals and below market forecasts, with an earnings profile still in loss making territory and debt not well covered by operating cash flow. The new proteomics workflows and NMR order are positive product and customer signals but do not yet resolve those pressure points.
The new timsUltra AIP and timsOmni workflows look most relevant for the current Bruker story because they directly expand use cases in proteomics, glycoproteomics and oligonucleotide analysis. That sits alongside the analyst view that high resolution tools tied to post genomic biology and AI related investments are a medium term driver for instrument demand and recurring software and services.
Execution risk remains. Bruker still has loss making automation and spatial biology activities, goodwill already written down, and a reliance on cost actions and mix shift to raise margins. The rich proteomics data shown in Parkinson’s samples and the UC Berkeley NMR order illustrate technical depth and customer adoption. Investors still need to watch whether that breadth converts into steadier organic growth and better cash coverage of debt.
What The Current Bruker Forecasts Assume
Bruker’s current analyst narrative leans heavily on a fairly specific earnings path. Forecasts point to revenue expanding at 5.0% a year over the next three years, with profit margins expected to move from a loss making position of 3.1% today to 13.4% by around 2029. Consensus calls for earnings to reach US$542.3 million by that year, compared with a loss of US$106.9 million at present, although the more cautious estimates sit closer to US$443.7 million.
Those earnings assumptions feed directly into how the stock is being valued today. Analysts are anchoring their consensus view on Bruker earning US$542.3 million on about US$4.1b of revenue in 2029, with the shares trading on a P/E of 22.5x at that point. That compares with a current P/E that is distorted by loss making results and is lower than the 41.0x P/E cited for the wider US life sciences peer group.
Bruker's narrative projects US$4.1b revenue and US$542.3 million earnings by 2029. This assumes 5.0% yearly revenue growth and an earnings increase of about US$649 million from a loss of US$106.9 million today.
Uncover why Bruker's fair value indicates that Bruker is roughly in line with its current price.
Exploring Other Perspectives
One alternate view on Bruker treats deep tech and China exposure as the real upside swing factor. Bullish analysts were already pencilling in about 6.1% annual revenue growth and around US$575.9 million of earnings by 2029, compared with the US$542.3 million consensus. The new proteomics and NMR news could shift those narratives further, in either direction, so it makes sense for you to compare these competing storylines yourself.
Explore 2 other Bruker fair value estimates, including an estimate that indicates as much as 12% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Bruker research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Bruker. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bruker's overall financial health at a glance.
Looking For More Ideas Beyond Bruker?
If Bruker has sharpened your interest in research tools and high quality fundamentals, it can be useful to scan a wider opportunity set and see how other stocks stack up on income, value and balance sheet strength.
- If you want potential income plus resilience, start with companies that aim to combine robust cash flows with sizeable payouts using our screener of 7 dividend fortresses.
- If value is your priority, compare Bruker with peers that pair stronger fundamentals and lower valuation multiples by reviewing the 31 high quality undervalued stocks.
- If balance sheet strength matters most to you, focus on businesses with cleaner leverage profiles and healthier cash positions through this list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com