
Is Casella Waste Systems (CWST) A Bargain On Its Hakes Landfill Expansion Approval?
Casella Waste Systems (CWST) has secured New York State approval to expand its Hakes construction and demolition landfill, adding disposal capacity, additional soil borrow acreage, and space for upgraded environmental infrastructure.
Casella Waste Systems has seen a mixed run, with a 1-day share price return of 6.02% after the Hakes permit approval. The 30-day and year-to-date share price returns are down 11.50% and 16.10% respectively, and the 3-year total shareholder return of 7.83% contrasts with the weaker 1-year total shareholder return of 9.82%, suggesting recent momentum has faded even as longer term holders have still seen gains.
Scan how Casella Waste Systems now compares with other waste and infrastructure plays by reviewing our handpicked 40 power grid technology and infrastructure stocks tied to long-term capacity and utility demand.
Casella Waste Systems now trades at a clear discount to both analyst targets and one estimate of fair value after the permit pop. Is this caution earned, or has the market swung too far?
Most Popular Narrative: 25.4% Undervalued
Casella Waste Systems closed at $82.77, while the most widely followed narrative puts fair value at $111, so the current gap centers on whether the company can turn heavy investment and expansion into durable profitability.
The main requirement for the strategy to work is that investments in automation, technology, and efficiency, including cost reduction programs and Mid-Atlantic synergies, translate into sustained EBITDA margin expansion despite higher operating costs and integration work.
The current valuation and high P/E multiples imply that the share price already reflects strong ongoing growth and improving returns, so any renewed margin pressure or weaker EPS delivery could limit upside and increase the risk of a derating.
What is behind 3 investors see Casella Waste Systems as 25% undervalued.
Result: Fair Value of $111 (UNDERVALUED)
Still, Casella Waste Systems faces real pressure if acquisition integration drags on or if operating costs remain hard to pass through, which could keep margins subdued.
Find out about the key risks to this Casella Waste Systems narrative.
Another View on Casella Waste Systems Valuation
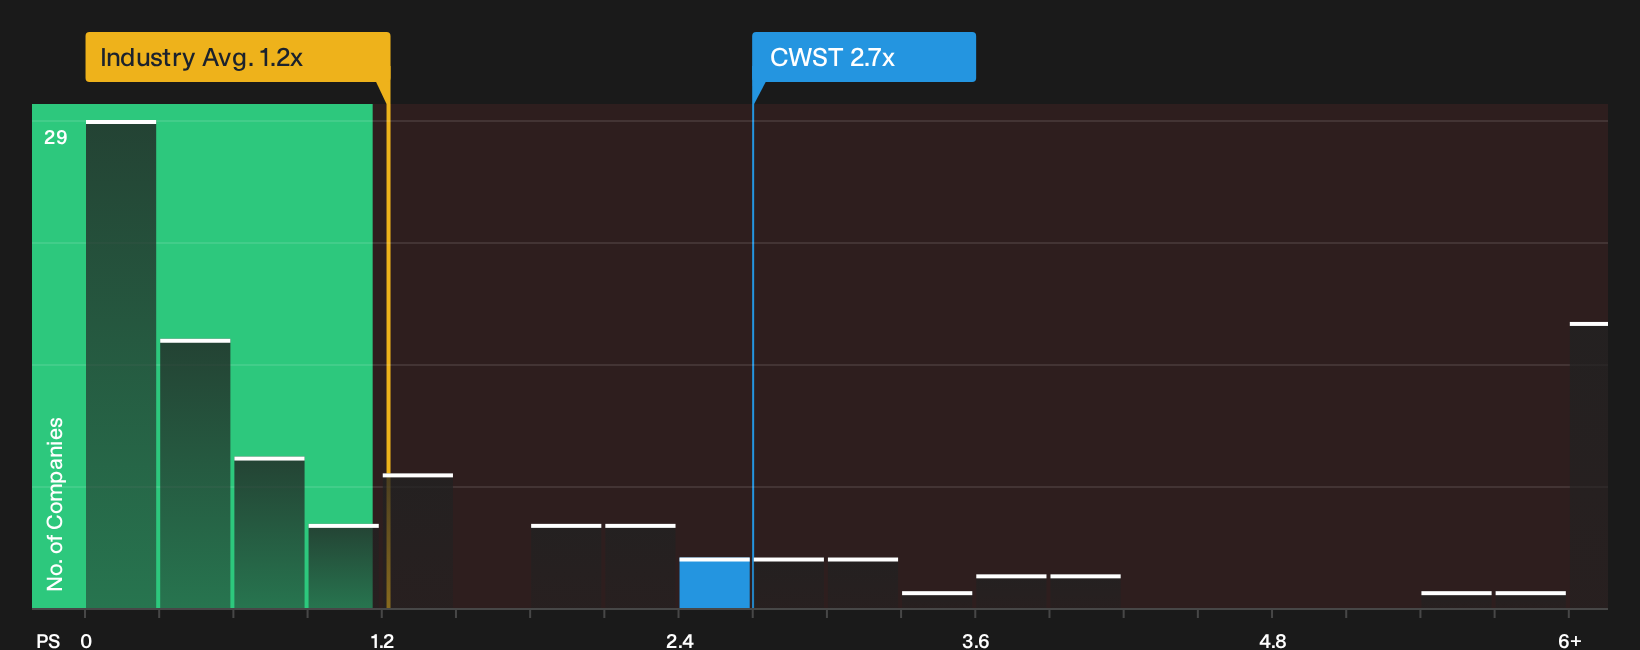
Analysts and the SWS DCF model both see Casella Waste Systems trading below an estimate of worth, yet a simple sales multiple sends a very different signal. The current P/S ratio of 2.7x sits well above both the 1.6x fair ratio and the 1.2x industry average. This lifts valuation risk rather than easing it. Which signal do you weigh more heavily when price and fundamentals disagree so clearly?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Casella Waste Systems can either paralyze or prompt action. Move quickly, review the data from both angles, and weigh the 3 key rewards and 4 important warning signs.
Looking for more Casella Waste Systems style ideas?
If Casella Waste Systems has your attention, do not stop here. Fresh opportunities rarely wait, and the best setups often appear when sentiment is conflicted.
- Target quality at a discount by scanning companies with strong fundamentals using our 31 high quality undervalued stocks.
- Protect your downside first and hunt for durability through the 31 resilient stocks with low risk scores.
- Spot future leaders early by checking the 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com