
How Investors Are Reacting To Jacobs Solutions (J) NVIDIA Data Center Win
- Recent announcements show Jacobs Solutions securing multi year work with NVIDIA on a Data Center Digital Twin in the U.S., alongside extended and renewed roles on major infrastructure and energy transition projects in Germany and the U.K.
- These wins point to Jacobs Solutions deepening exposure to AI driven data center demand and long duration critical asset programs under software and services models.
- We will now look at how Jacobs Solutions investment narrative could be affected by the NVIDIA data center digital twin deployment.
Scan how Jacobs Solutions’ NVIDIA win fits into the wider build out of AI infrastructure by reviewing our hand picked list of 90 AI infrastructure stocks powering the next wave of data center demand.
Jacobs Solutions Investment Narrative Recap
To own Jacobs Solutions, you need to believe the company can keep turning a US$29b backlog into steadier earnings while shifting more work toward higher value digital and AI heavy projects. The NVIDIA digital twin win supports that story, but it does not remove the near term pressure from low current profit margins, high debt and an elevated P/E multiple.
The biggest short term swing factor remains execution on large AI data center and critical infrastructure awards without further profit margin compression. The main risk is that public sector infrastructure budgets or AI project awards slow, which could expose Jacobs Solutions to more revenue mix volatility and challenge the narrative of steadily improving earnings quality.
The new NVIDIA data center digital twin deployment is the clearest link to the existing AI data center catalyst. It shows Jacobs Solutions monetising its Omniverse based tools through a three year software as a service contract. This leans into the goal of building more recurring and scalable revenue around complex facilities rather than only relying on one time project work.
That said, the key questions for you as an investor are still contract depth and durability. The NVIDIA deal underlines capability in simulation, predictive maintenance and energy forecasting, but it sits alongside exposure to government led infrastructure programs and a high level of debt. Execution on this type of AI work needs to translate into better margins to offset those risks.
What The NVIDIA Deal Means For Jacobs Solutions’ Forecasts
Jacobs Solutions sits in front of some ambitious expectations. Analysts are working off a 7.1% annual revenue growth rate, current earnings of US$359.3 million, and a consensus view that profits reach US$1.2b by 2029. That shift implies an earnings increase of about US$840 million by the forecast year, with revenues projected at US$17.5b in 2029.
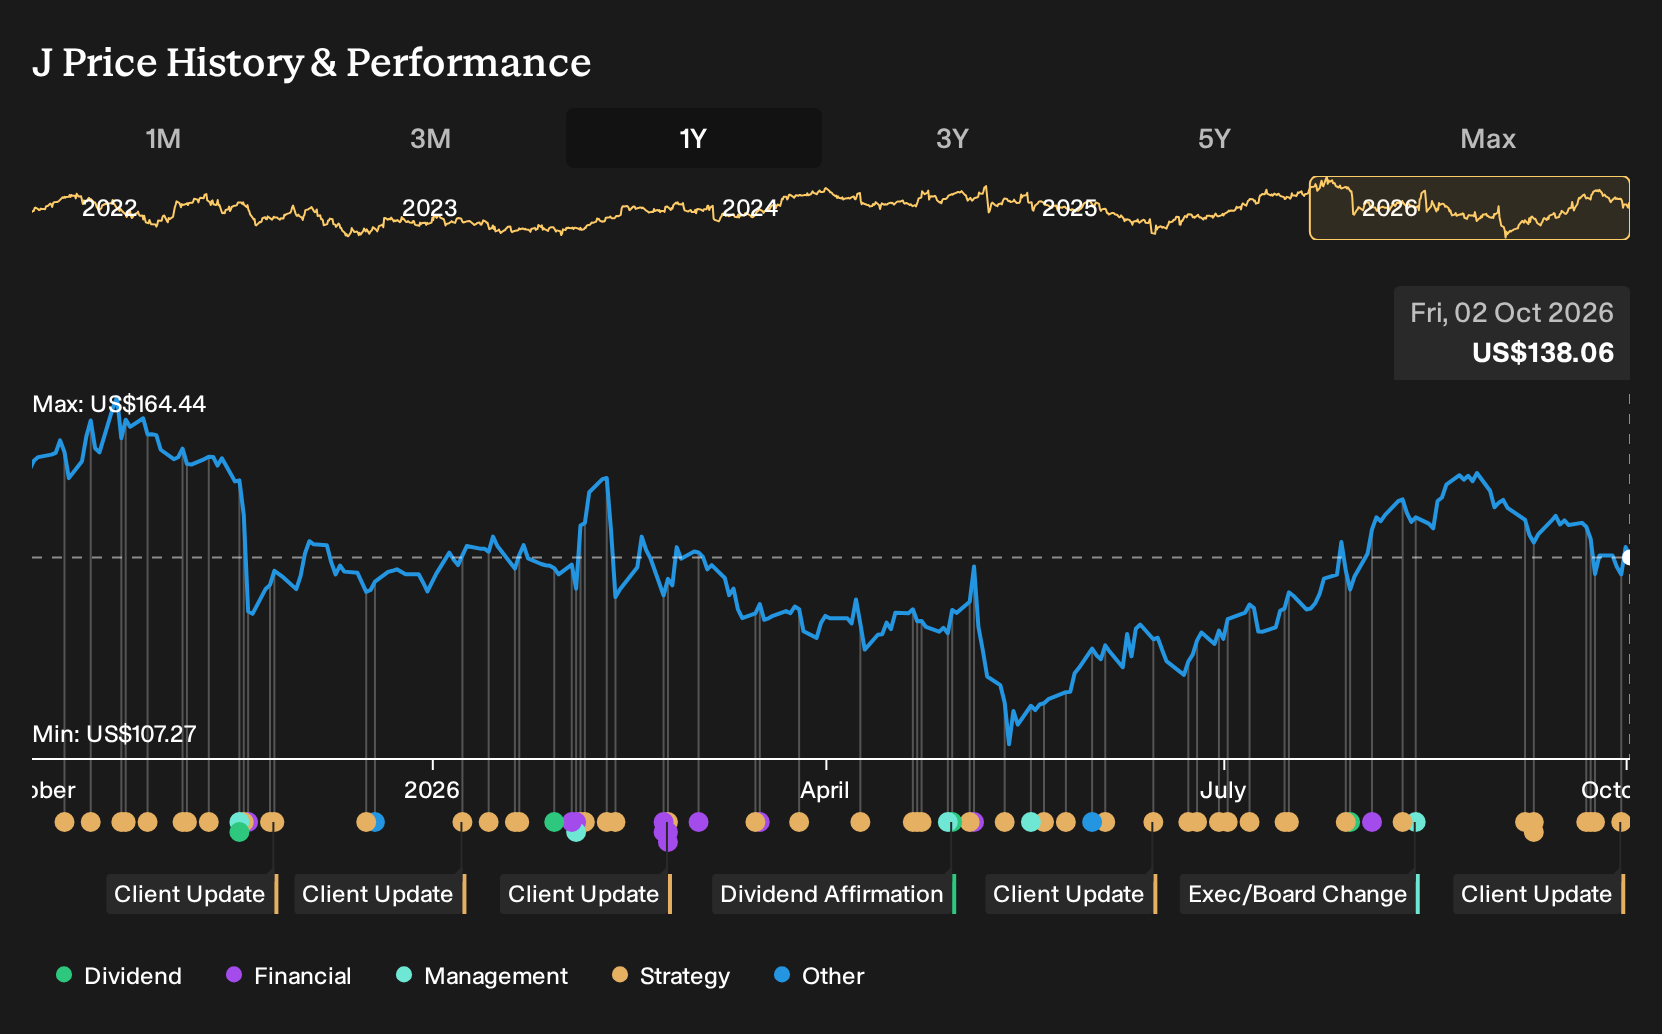
Uncover why Jacobs Solutions' fair value indicates an 18% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community range from US$110 to about US$278, so some retail investors see Jacobs Solutions as heavily undervalued while others sit at the top end. Set that against concentration in public infrastructure and AI data centers, and you get a wide spread of opinions. Explore those alternative views before deciding how this story fits your portfolio.
Explore 3 other Jacobs Solutions fair value estimates, including one that suggests as much as 101% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Jacobs Solutions research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Jacobs Solutions. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Jacobs Solutions' overall financial health at a glance.
Looking For More Investment Ideas Beyond Jacobs Solutions?
Once you have formed a view on Jacobs Solutions, it can help to widen the lens and compare it with other companies that match your risk appetite, return goals and time horizon. The Simply Wall St Screener gives you a fast way to filter the market down to a short list that actually fits what you are looking for.
- If you want potential mispricing with stronger fundamentals as a starting point, scan our 31 high quality undervalued stocks and see which businesses currently trade below their assessed value with solid balance sheets and cash flows.
- If income is a key part of your plan, focus your attention on companies in the 7 dividend fortresses that combine higher yields with an emphasis on sustainability.
- If downside protection matters most, narrow your research to the 31 resilient stocks with low risk scores and concentrate on businesses screened for resilience and lower risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com