
Minerals Technologies (MTX) Could Be 42% Undervalued On New $400 Million Notes
Minerals Technologies (MTX) has priced a private offering of $400 million in 7.500% senior notes due 2032, alongside plans to expand and extend its revolving credit facility commitments.
The fresh debt issuance comes after a mixed run for Minerals Technologies, with the share price slipping 7.43% over the past 30 days and 10.65% over 90 days, even as the year-to-date share price return is 8.63% and the 3-year total shareholder return is 31.73%, suggesting longer-term holders have fared better than recent buyers.
Scan how Minerals Technologies compares with a hand picked group of materials players using our list of solid balance sheet and fundamentals (25 results) as a starting point for further ideas.
Minerals Technologies shares have pulled back even as management locks in fresh long term funding. Is that a window to start gradually building a position now, or a reason to wait for an even cheaper entry before committing more capital?
Most Popular Narrative: 30% Undervalued
The most followed narrative pegs Minerals Technologies at a fair value of $94.25 per share, compared with the last close at $66.43, framing the new $400 million notes within a story of discounted cash flows rather than just balance sheet reshuffling.
Ongoing investments in capacity expansions for high-growth, sustainable products (e.g., sustainable aviation fuel purification, animal health solutions, fabric care, and pet litter in Asia) are positioned to benefit from global population growth, urbanization, and heightened sustainability demand, directly supporting revenue growth and above-average margin expansion.
Rapid progress in new packaging and specialty satellite facilities (including NewYield and sustainable mineral technologies in Asia and India) capitalizes on the long-term shift toward increased e-commerce and eco-friendly packaging, providing a strong pipeline for incremental revenue and improved EBITDA over the next 12–18 months.
See why 5 investors see Minerals Technologies as 30% undervalued.
Result: Fair Value of $94.25 (UNDERVALUED)
Still, the bullish Minerals Technologies story can crack if talc litigation costs escalate or if weak paper demand continues to drag on the Specialty Additives unit.
Find out about the key risks to this Minerals Technologies narrative.
Another View: Minerals Technologies Through A Sales Multiple Lens
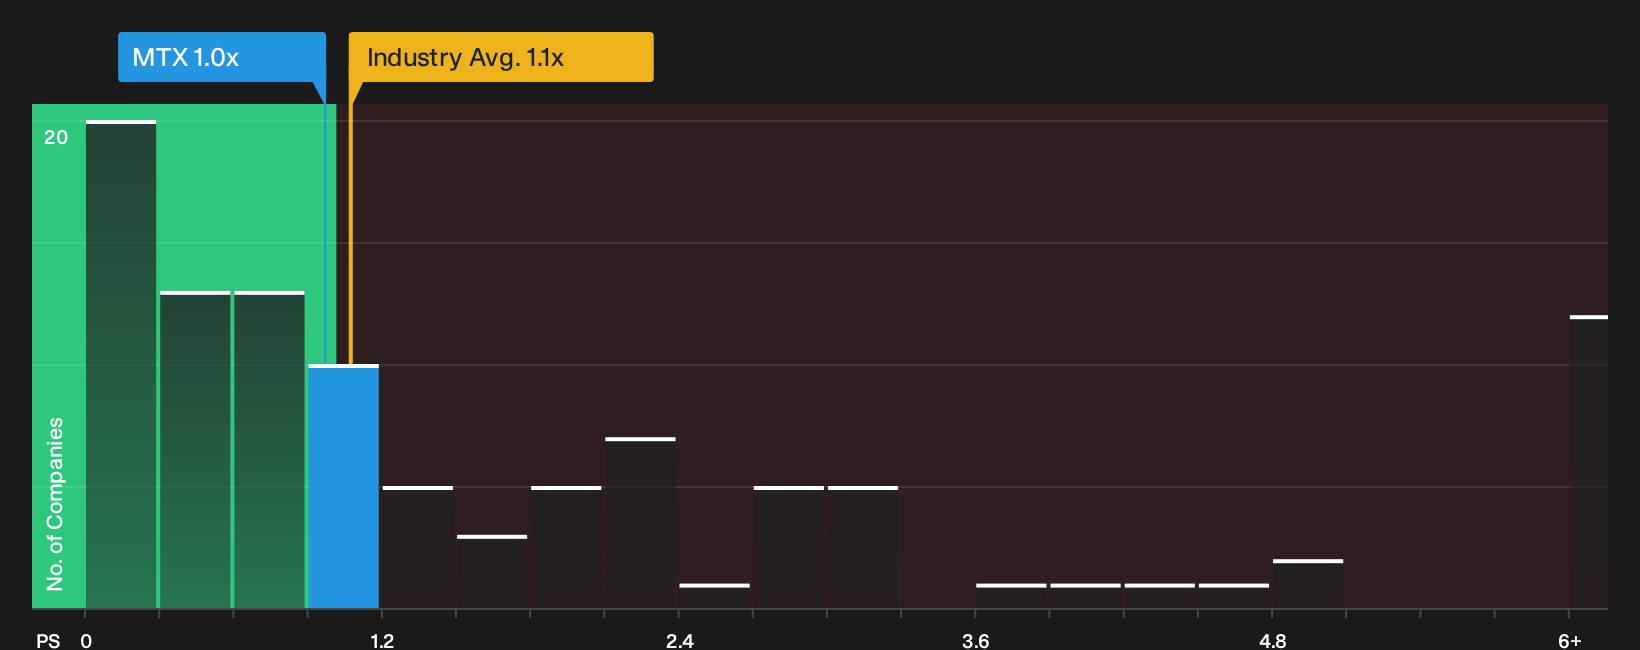
The SWS DCF model points to a large gap between Minerals Technologies and its estimated future cash flow value of $196.34 per share, yet the simpler P/S check looks less generous. The stock trades at about 1x sales versus a fair ratio of 0.8x and a US Chemicals industry average of 1.1x. That mix of deep DCF upside and only modest P/S support raises a practical question for you as an investor: Is this a classic mispricing or a signal to stress test every assumption inside the cash flow model before leaning on it?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this Minerals Technologies story sounds optimistic, yet the picture is not one sided, so move fast and test the numbers yourself by reviewing the 3 key rewards.
Looking for more Minerals Technologies investment ideas?
If Minerals Technologies has caught your attention, do not stop here. Broaden your opportunity set by running a few focused screens that surface companies with very different strengths.
- Target upside by scanning companies that currently screen as 19 high quality undiscovered gems before other investors start paying attention to them.
- Strengthen capital preservation by reviewing 31 resilient stocks with low risk scores that may help balance out more volatile positions in your portfolio.
- Pursue quality at a discount by working through 31 high quality undervalued stocks that combine solid fundamentals with prices that do not fully reflect them.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com