
Why Rallis India Lost 35% Even As Profitability Improved
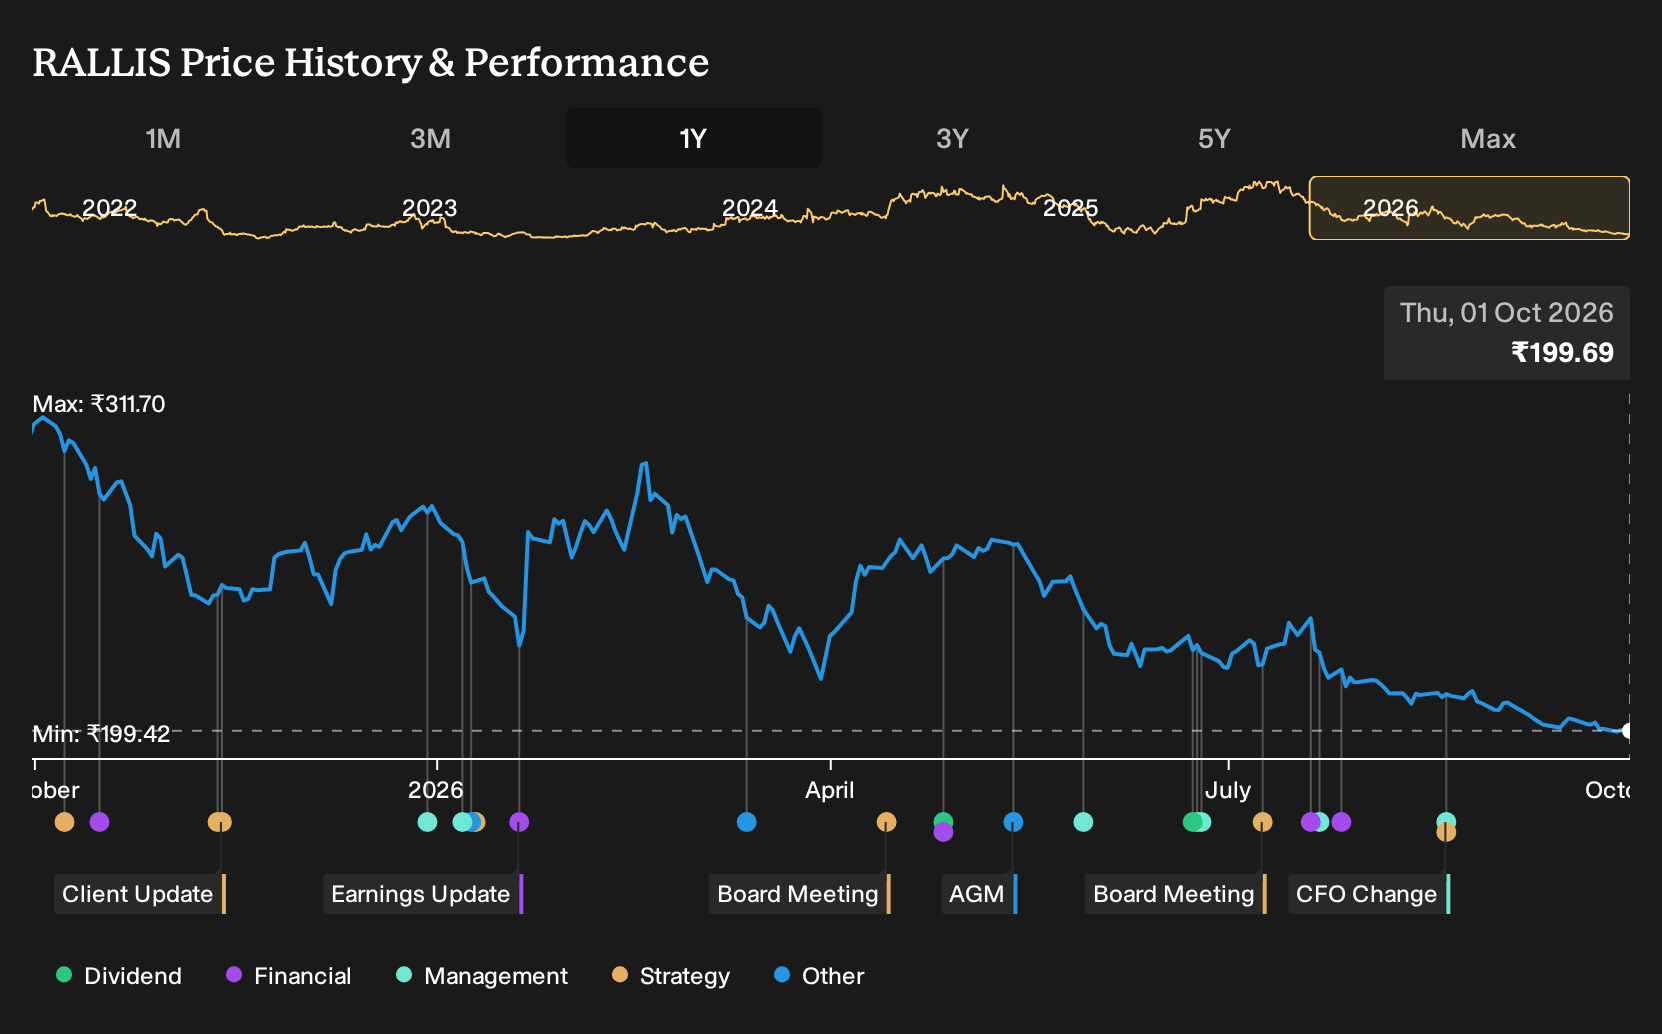
Fresh from its Q1 FY27 update on 20 July 2026, Rallis India reported revenue of ₹10,220m and net income of ₹1,250m, with net margin at 12.2%. For Rallis India shareholders, the loss over the past year was 35.1%, including dividends. If you had decided on 1 October 2025 to put money into this stock, how much of that outcome would you say was really visible in advance?
Rallis India has already moved. See which of 192 high quality undervalued stocks still trade below our estimates.
The Two Stories Investors Had To Weigh On Rallis India
The shares cost ₹309 at the start, and you were choosing between two very different stories about where Rallis India could head next.
On the optimistic side, the bullish view put Fair Value at ₹360, essentially the price implied if its brighter assumptions played out. This view hinged on sustained cost control and a shift toward higher margin specialty products that could support stronger earnings power.
The more cautious camp saw Fair Value closer to ₹293, with attention on high industry inventories and pricing pressure that might keep revenue growth and profit margins under strain.
What The Results Changed For Rallis India
The clearest update was Rallis India’s Q1 FY27 numbers. Revenue was ₹9,570m in Q1 FY26 and ₹10,220m in Q1 FY27, while net income moved from ₹950m to ₹1,250m and net margin from 9.9% to 12.2%. That combination supported the optimistic case on earnings power, although one quarter does not settle the longer term margin argument.
The key lesson is simple. When a thesis leans on better profitability, focus on net margin and absolute profit in each result, and check whether the promised mix shift and cost control are showing up in those figures.
What Rallis India's Share Price Drop Really Asks You
Today Rallis India trades at ₹200, well below the ₹309 level from a year ago and below where the selected Narrative’s Fair Value currently sits. That Narrative leans on cost control, digital tools and a tilt toward specialty products to argue for stronger and more durable profitability.
For that higher figure to be reached, a buyer today would need to assume Rallis India can sustain structurally better operating margins through product mix and ongoing efficiency gains.
"Analyst consensus acknowledges margin expansion may be unsustainable, but in reality, Rallis India's ongoing cost optimization, fixed cost control, digitalization, and improving product mix underscore a structural uplift in operating margins and earnings power, which is likely still underappreciated relative to its current valuation."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Rallis India And A Different Resource Play
Rallis India links directly to crops and soil in the value chain. You could also consider a resource story sitting further upstream in materials.
This other business looks for critical metals used in ammunition, electronics and wider industrial applications. It selects exploration ground beside already proven deposits with established geology.
The approach rests on geological continuity between neighbouring rock formations and mineral systems. If nearby ground hosts commercially viable ore, adjacent terrain might contain useful metals.
For you, the unresolved point is how often that proximity turns into meaningful discoveries. That gap between promising maps and proven deposits defines the real opportunity.
That argument has a Narrative and a number behind it. → See the company one Narrative values 80% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com