
Kodiak Gas Services (KGS) Is Back In The Spotlight, What Is Driving Attention?
Kodiak Gas Services (KGS) just signed a six year deal to supply 76 megawatts of behind the meter baseload power to a West Texas data center, backed by investment grade counterparties.
Investors have already priced in some of this momentum, with Kodiak Gas Services delivering a 44.3% year to date share price return and a 63.8% total shareholder return over the past year. However, the 30 day share price return declined 13.2% and the 90 day share price return fell 18.0%, suggesting recent enthusiasm has cooled after a very strong three year total shareholder return of about 3.6x.
Scan other power and data center plays on Simply Wall St by zeroing in on our curated list of 40 power grid technology and infrastructure stocks, alongside Kodiak Gas Services.
Kodiak Gas Services now trades at a steep discount to both analyst targets and intrinsic estimates after that pullback. Is the market being sensibly cautious, or mispricing the new data center power deal altogether?
Most Popular Narrative: 35% Undervalued
Kodiak Gas Services last closed at $54.33, while the most followed narrative pegs fair value at $84.07 using a 7.77% discount rate. That gap sits at the center of the bullish case around long duration contracts and the emerging power business.
High fleet utilization (over 97%), increased contracting of new large horsepower units at premium rates, and the long-term, fee-based nature of Kodiak's contracts underpin resilient, recurring revenue and EBITDA stability, providing earnings visibility even across choppy commodity price environments.
See why 4 investors see Kodiak Gas Services as 35% undervalued.
Result: Fair Value of $84.07 (UNDERVALUED)
Still, Kodiak Gas Services leans heavily on Permian Basin activity and a very capital intensive model, so any slowdown in volumes or higher spend could quickly stress the bullish case.
Find out about the key risks to this Kodiak Gas Services narrative.
Another View: Kodiak Gas Services Through Earnings Multiples
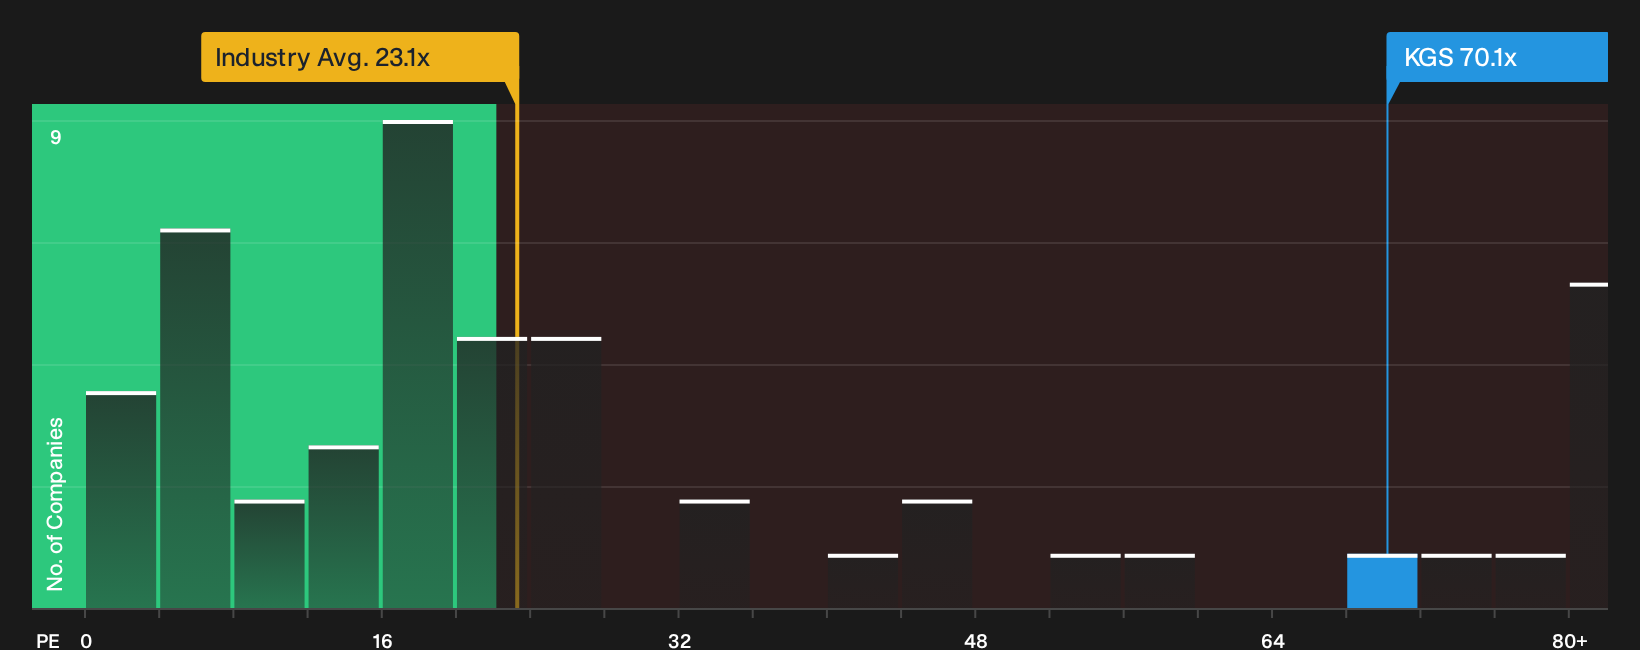
The discounted cash flow work paints Kodiak Gas Services as deeply undervalued, yet the market is still paying a rich P/E of 70.1x. That is well above the US Energy Services industry on 23.1x, the peer group on 45x, and even a fair ratio of 27.1x that the market could move toward. Does that premium signal confidence in the power buildout, or raise the risk of a sharp reset if expectations slip?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of enthusiasm and concern around Kodiak Gas Services feels familiar, consider acting while sentiment is still resetting and stress test the 3 key rewards and 5 important warning signs.
Looking for more investment ideas beyond Kodiak Gas Services?
You have seen how one contract can reshape the story for Kodiak Gas Services. Now widen the lens and use the Simply Wall St screener to uncover fresh opportunities that fit your own risk and return goals.
- Target resilient payouts by zeroing in on companies that prioritise income strength using the 7 dividend fortresses.
- Chase mispriced quality by scanning the 19 high quality undiscovered gems and spotting businesses the wider market may not be watching yet.
- Dial down portfolio stress by filtering for financially robust candidates with the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com