
Emerson Electric (EMR) Has A Fresh Update, So Why Is It Drawing Attention?
Emerson Electric (EMR) has put a new pin on the map. The group plans a 3,500-square-meter Middle East and Africa Service Center in Qatar’s Umm Alhoul Free Zone, focused on automation support.
For investors watching Emerson Electric, the timing of this Qatar announcement lands during a strong run in the shares. A 30-day share price return of 5.75% and a 90-day share price return of 14.16% are helping build momentum on top of an 18.99% year-to-date share price gain and a 1-year total shareholder return of 21.81%.
Scan how Emerson Electric’s Qatar move fits into the wider automation story by comparing it with a curated group of industrial and automation-focused stocks in our 89 robotics and automation stocks.
Emerson Electric now trades close to analyst targets, yet its own intrinsic value models point to a very different number. With that spread widening after the Qatar announcement, the question for investors is where fair value really lands for this stock.
Most Popular Narrative: 7% Undervalued
On the most followed view of Emerson Electric, the narrative fair value of $173.68 sits above the last close of $161.61, which puts the Qatar announcement into a wider story about software, projects and execution risk.
The accelerating adoption of digital automation and artificial intelligence solutions in global industrial markets is fueling strong demand for Emerson Electric's advanced software platforms and AI-enabled products, such as Ovation 4.0 and Nigel AI adviser. This is resulting in robust order growth and positions the company for sustained revenue expansion that can support earnings.
See why 57 investors see Emerson Electric as 7% undervalued.
Result: Fair Value of $173.68 (UNDERVALUED)
Still, conflict-related disruption in the Middle East and ongoing softness in China chemicals markets could knock Emerson Electric off this 7% undervalued narrative.
Find out about the key risks to this Emerson Electric narrative.
Another View: Emerson Electric And The Cash Flow Gap
The market is treating Emerson Electric as roughly 7% undervalued on the narrative fair value of $173.68, yet the SWS DCF model paints a very different picture. On a cash flow basis, EMR at $161.61 trades well above an estimated future cash flow value of $80.48, which screens as overvalued.
That kind of gap between what earnings-based narratives suggest and what discounted cash generation implies raises a simple question for investors: Which story feels more realistic when thinking about what you are actually paying for each future dollar of cash flow?
Look into how the SWS DCF model arrives at its fair value.
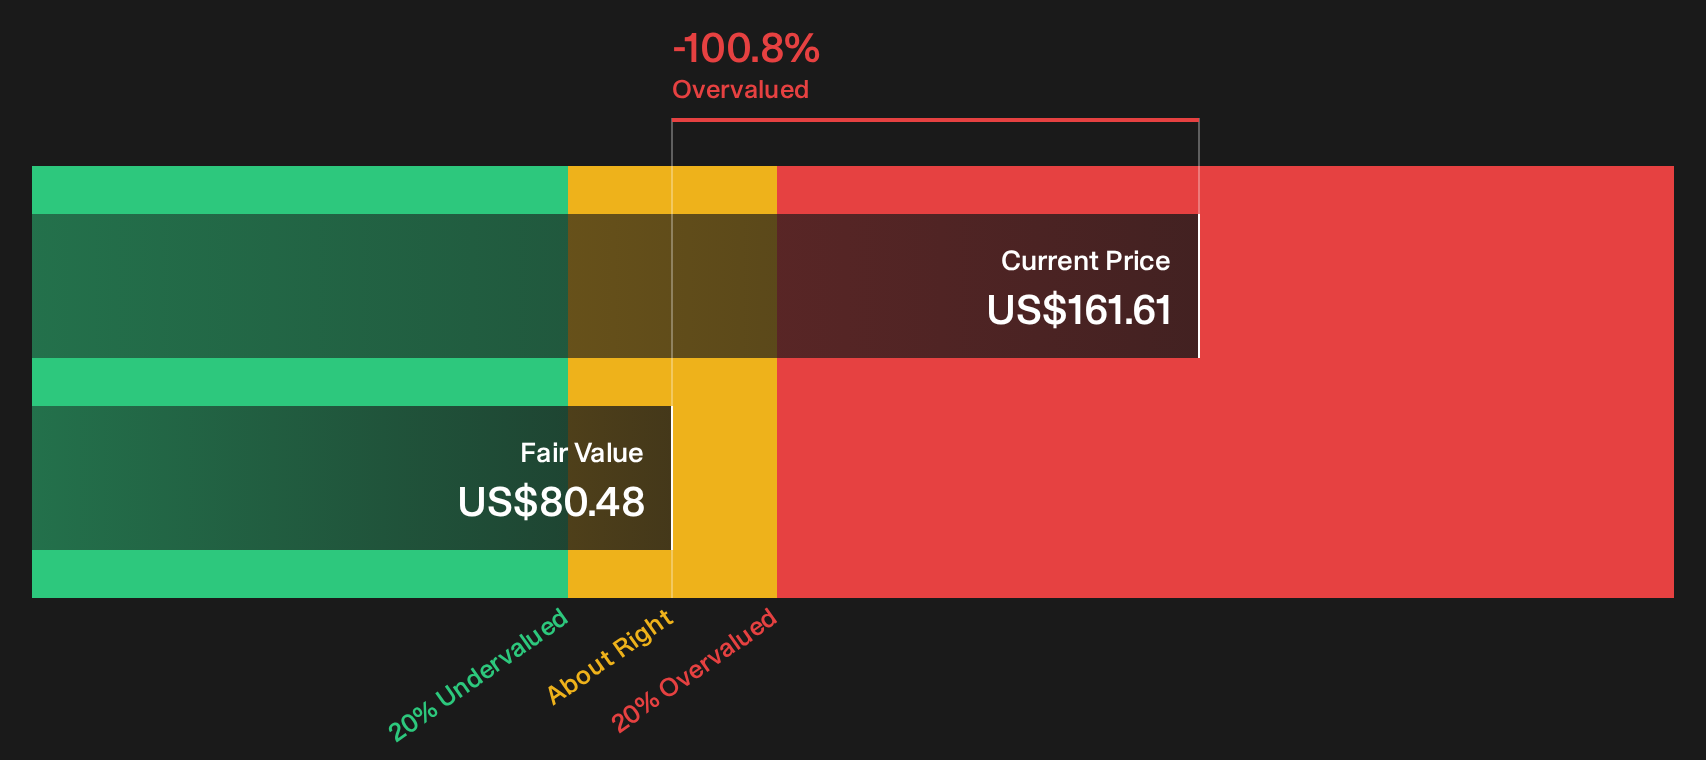
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Emerson Electric for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Emerson Electric so far. Act while the details are fresh in mind and pressure test both the upside and downside by reviewing the 3 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Emerson Electric?
Ready to pressure test your thesis on Emerson Electric by lining it up against other opportunities on the market across quality, value, income and risk?
- Spot potential value opportunities early and compare them with Emerson Electric using our 31 high quality undervalued stocks.
- Build a steadier income stream by weighing Emerson Electric’s yield against companies in the 7 dividend fortresses.
- Guard the downside of your portfolio by setting Emerson Electric alongside a 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com