
What You Can Learn From Vipshop’s 37% Slide And Higher Profits
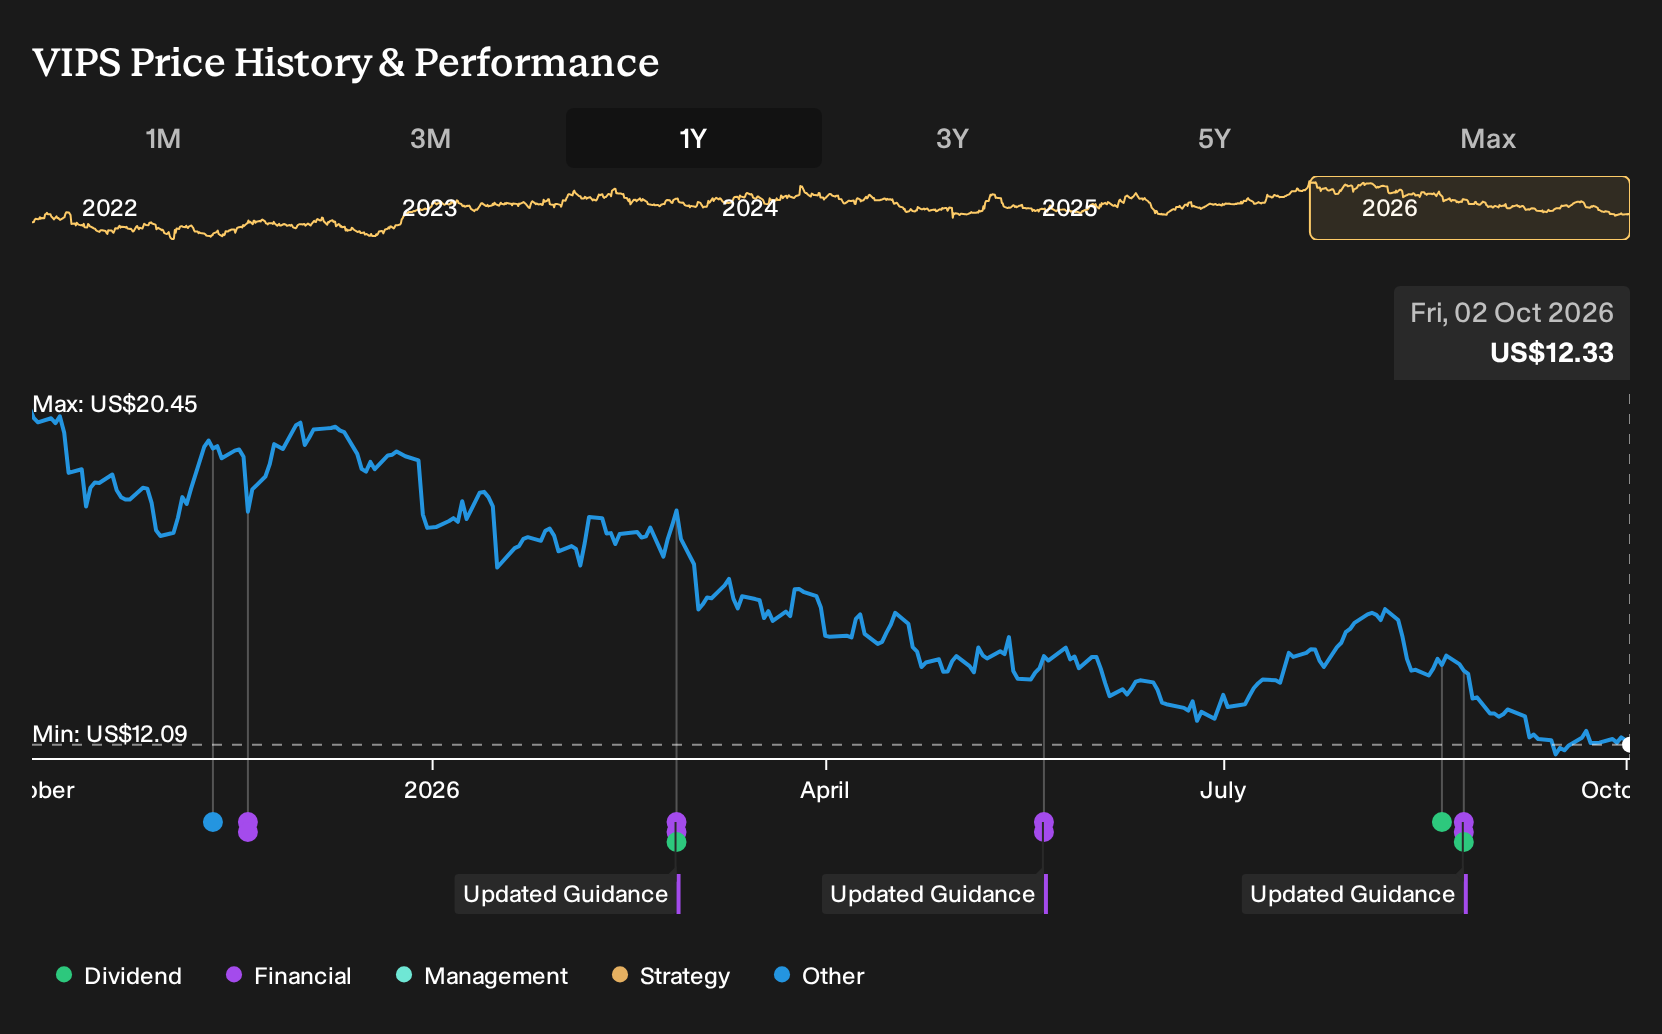
Vipshop’s latest Q2 2026 update showed lower revenue but a much higher net margin, which grabbed attention after months of mixed sentiment and insider sales headlines. Investors who held Vipshop over the past year are down 36.8%, including dividends. If you had bought on 2 October 2025, seeing bullish and cautious analyst narratives side by side, how should you now judge whether those margin gains reflect something durable or just a temporary lift?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind Vipshop. Zero in on 31 high quality undervalued stocks for companies trading below our estimates.
The Two Vipshop Stories Investors Had To Weigh
The shares cost US$20.41 at the start of the period, and Vipshop sat between two well argued stories about where the business might head next.
The bullish narrative put Fair Value at US$22.57 and leaned on the rising Chinese middle class and mobile commerce, assuming revenue growth of 3.4% a year and profit margin moving to 7.6% with a future P/E of 10.9x.
The more cautious view set Fair Value at US$18.17 and focused on risks around apparel exposure, using revenue growth of 2.2%, profit margin at 7.2%, and a future P/E of 9.6x.
What The Results Changed For Vipshop
Vipshop’s Q2 2026 report showed revenue of CNY 24,707.1m versus CNY 25,806.4m a year earlier, while net income climbed to CNY 4,306.2m and net margin moved from 5.8% to 17.4%. That profitability jump leaned toward the bullish case that focused on earnings quality, although the softer top line and apparel demand in recent updates kept the cautious story alive. Overall, the evidence cut both ways.
The key assumption tested here was margin resilience. When judging another retailer, track how net margin moves against flat or declining sales to see whether efficiency claims hold up in real reporting.
What Vipshop’s Lower Price Asks You To Believe
Vipshop now trades at US$12.33, and the selected Narrative sees Fair Value above that level based on its own assumptions rather than settled fact.
The argument leans on personalization, SVIP loyalty and buybacks to support earnings quality. For that higher figure to be reached, sustained customer stickiness and healthy cash generation would need to hold.
"Analyst consensus recognizes the growth of SVIP membership, but this could be understated, as intensifying personalization and exclusive benefits may unlock a virtuous cycle, rapidly increasing customer lifetime value and stickiness, driving not just higher revenue per user but also potential outperformance in net margins."
One Narrative disagrees with today's price. → See where this Narrative says Vipshop should trade
Looking Beyond Vipshop’s Platform
Vipshop shows how much can rest on margins and loyalty. Just beside it, another operator leans on something broader and more sprawling.
This business runs a technology ecosystem that reaches well beyond shopping. Merchants and consumers connect through payments, logistics, media and local services.
At the center sits a cloud and AI platform powering many activities. It delivers computing capacity and models that help customers build tailored applications.
Pieces such as fintech, logistics and AI startups create additional layers of optionality. The remaining puzzle is how this interconnected web of assets ultimately gets valued.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 129% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com