
Stolt-Nielsen (OB:SNI) As Stronger Third Quarter Results Reopen The Valuation Debate
Why the latest earnings matter for Stolt-Nielsen
Stolt-Nielsen (OB:SNI) has just posted third quarter results that show higher sales and earnings per share compared with the same period last year. This gives investors fresh numbers to reassess the stock.
The stronger third quarter helps explain why Stolt-Nielsen’s share price has climbed to NOK365.5, with a 30-day share price return of 8.14% and a 90-day share price return of 26.25%, while the 5-year total shareholder return of 287.29% points to momentum built over a longer stretch.
Scan Stolt-Nielsen’s latest momentum against a hand-picked 192 high quality undervalued stocks that combine stronger fundamentals with price tags that still look reasonable on the numbers.
Stolt-Nielsen now trades only slightly below average analyst targets, even after a strong run. Is that a sign the market is cautious for good reason, or still underestimating the business?
Most Popular Narrative: 6% Overvalued
Stolt-Nielsen’s most followed valuation story puts fair value at NOK343.90, which sits below the latest NOK365.50 close and frames the recent rally as slightly ahead of that model.
Stolt-Nielsen is diversifying its portfolio with acquisitions like Hassel 4 and LNG carrier Avenir. Together these are expected to contribute approximately $50 million annually to EBITDA, which is likely to impact earnings growth positively.
See why 11 investors see Stolt-Nielsen as 6% overvalued.
Result: Fair Value of NOK343.90 (OVERVALUED)
Still, higher tariffs on maritime trade or a sharper drop in tanker shipment volumes could quickly challenge the upbeat Stolt-Nielsen fair value story.
Find out about the key risks to this Stolt-Nielsen narrative.
Another View on Stolt-Nielsen’s Valuation
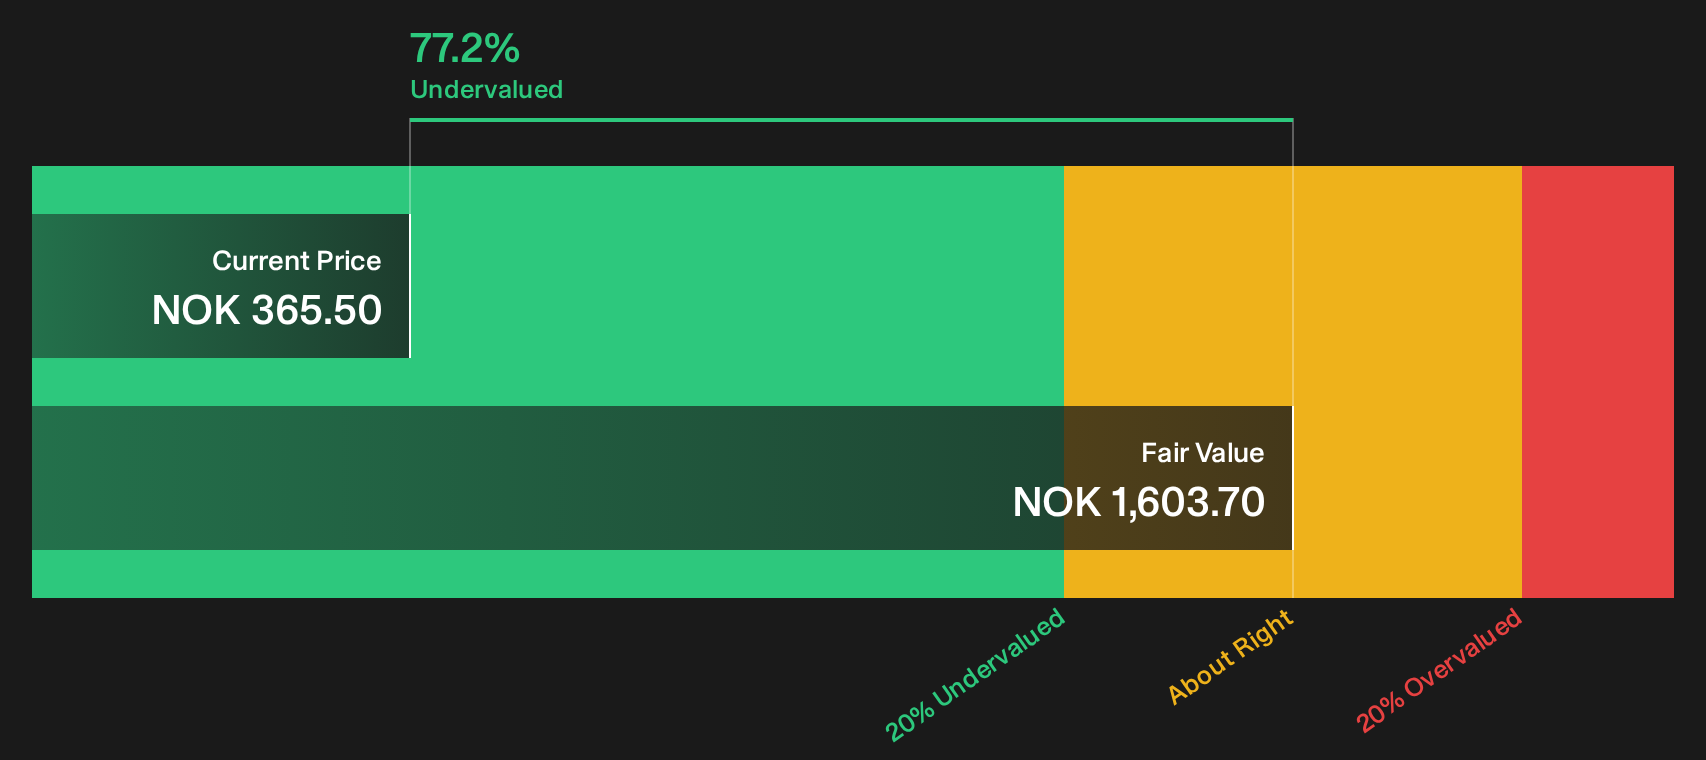
The first narrative says Stolt-Nielsen looks about 6% overvalued around NOK365.5 based on analyst targets around NOK343.90. A different lens tells a very different story. Our DCF model suggests a fair value near NOK1,603.70, which frames the current quote as deeply discounted rather than stretched.
If both fair values sit on the same set of cash flows, the key question is which assumptions you find more realistic for Stolt-Nielsen: the cautious analyst path or the richer SWS DCF model outcome.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals on Stolt-Nielsen’s valuation can cut both ways, so move quickly from headline stories to the underlying data and pressure test the trade-offs yourself with 2 key rewards and 4 important warning signs
Looking for more investment ideas beyond Stolt-Nielsen?
If Stolt-Nielsen has caught your attention, do not stop there. Cast the net wider with a few focused stock ideas that match different investing goals.
- Target potential future upside with companies that combine strong fundamentals and reasonable valuations by scanning this carefully filtered set of 192 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses built around cash flows and yields through our hand picked group of 168 dividend fortresses.
- Protect your capital first and let compounding do the work by starting with a 227 resilient stocks with low risk scores that keeps risk scores front and center.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com