
Topicus.com (TSXV:TOI) Names A New CEO, Is The Stock Cheap Or Pricey?
Leadership change puts Topicus.com under a fresh spotlight
Topicus.com (TSXV:TOI) caught investor attention after a 2.52% share price move on October 1, 2026, as Ramon Zanders took over from Robin van Poelje as CEO.
The market is now weighing how this handover could influence capital allocation priorities, acquisition pacing, organic expansion, and margin discipline for the euro-reporting software specialist.
Topicus.com’s recent 1-day share price return of 1.49% and 7-day gain of 2.25% come against a tougher backdrop, with the 30-day share price return down 10.57% and year-to-date share price return down 28.12%, pointing to fading momentum after earlier weakness. Over longer periods, total shareholder returns have been mixed, with a 1-year total return down 39.05% but a 3-year total shareholder return close to flat, as investors reassess both growth potential and execution risks around the new leadership.
Compare Topicus.com’s leadership reset with other software players under pressure by running your filters against our hand picked 9 high quality undiscovered gems
Topicus.com now trades at a steep discount to both analyst targets and fair value estimates, yet the share price slide and CEO change still keep many on the sidelines. Is that caution misplaced or well earned as the numbers stack up?
Most Popular Narrative: 38% Undervalued
Topicus.com closed at CA$89.88, while the most widely followed narrative anchors fair value at CA$144.65. This frames a sizeable gap that hinges on aggressive earnings and margin assumptions playing out under the new CEO.
The mix of recurring service based software contracts and professional services that underpins Topicus.com is framed as a quality enterprise software model. This structure can help keep revenue more predictable and support stable margins and cash generation over time.
See why 5 investors see Topicus.com as 38% undervalued.
Result: Fair Value of CA$144.65 (UNDERVALUED)
Still, if the ReadyTech proposal falls through or if there is any stumble on future acquisitions, it could quickly challenge the bullish Topicus.com valuation story that investors are leaning on.
Find out about the key risks to this Topicus.com narrative.
Another View: Topicus.com Looks Expensive On Earnings
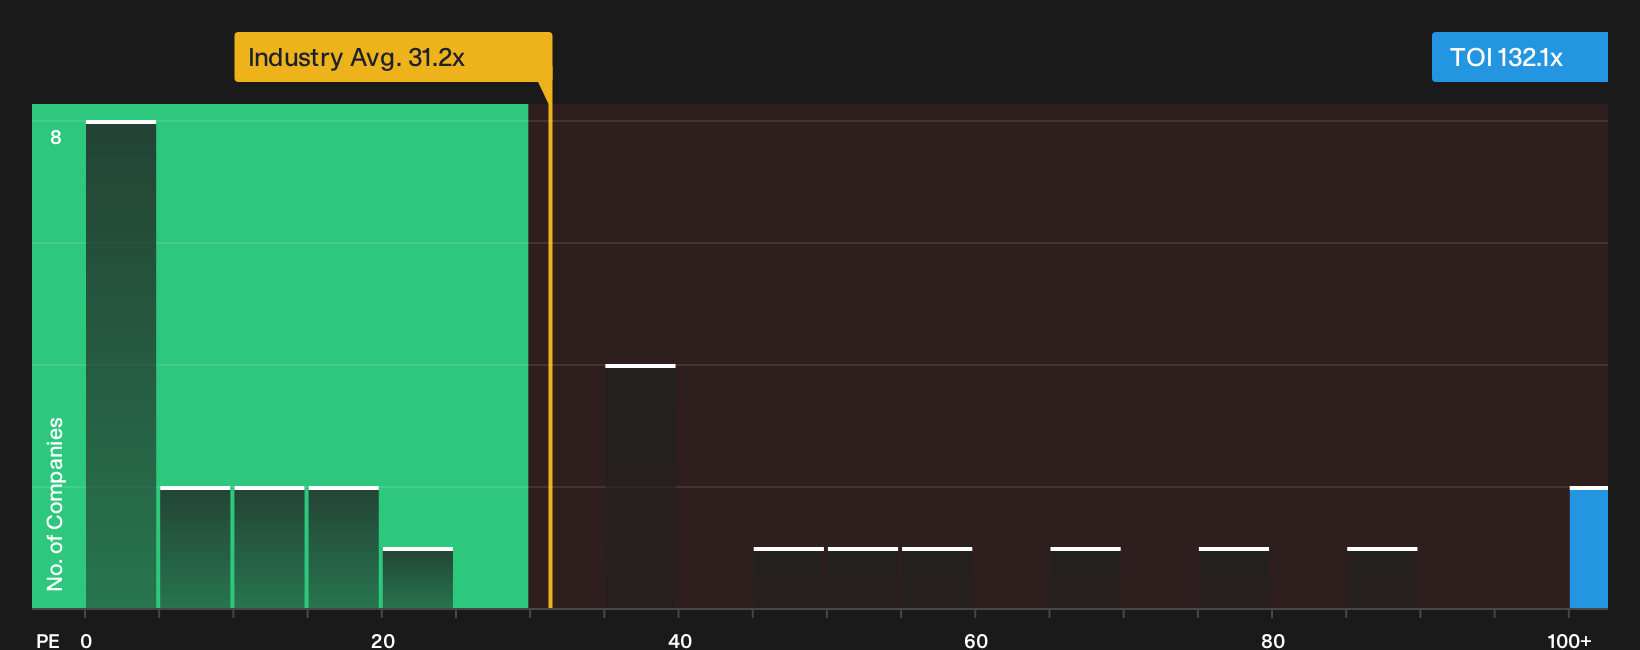
Topicus.com looks cheap against a CA$144.65 fair value narrative, yet its current P/E of 132.1x is far above the North American software group at 31.2x, peers at 39.3x, and even its own fair ratio of 85.5x. That gap points to real valuation risk if sentiment cools.
For a closer look at how this profit based yardstick compares with other ways of thinking about price, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Topicus.com story so far. For a clearer perspective, consider acting promptly, reviewing the data, and then weighing the 3 key rewards and 2 important warning signs.
Looking for more Topicus.com style investment ideas?
Do not stop your research at Topicus.com. Broaden your watchlist with fresh ideas from the Simply Wall Street Screener that match your own risk and return preferences.
- Target potential mispricings by scanning a curated 6 high quality undervalued stocks that pairs strong fundamentals with what may be lagging share prices.
- Prioritise resilience by running through a list of solid balance sheet and fundamentals (7 results) that can help you focus on companies with sturdier financial footing.
- Limit nasty surprises by filtering for a 8 resilient stocks with low risk scores and keep your attention on businesses with more measured risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com