
Avantor (AVTR) Shares Climbed, So What Is Driving Attention Today?
Why Avantor’s CFO change matters for shareholders
Avantor (AVTR) has reshaped its leadership bench by appointing Todd Garner as Chief Financial Officer and Executive Vice President, effective September 21, 2026, placing a seasoned finance operator in charge of the global finance function.
Garner now oversees financial planning and analysis, accounting, treasury, tax, investor relations and internal audit. For anyone following Avantor stock, this consolidates a broad set of capital allocation and reporting responsibilities under one experienced executive.
The CFO appointment comes as Avantor’s share price trades at US$15.34, with a 1 day share price return of 2.06% and a 90 day share price return of 47.93%. This contrasts with a 5 year total shareholder return that has fallen 62.20%, suggesting that short term momentum has picked up while long term holders have faced a much tougher journey.
Compare how other healthcare and biopharma suppliers are priced relative to Avantor by running a focused screen of list of solid balance sheet and fundamentals (25 results).
Avantor looks like a solid operator with mission critical products and fresh finance leadership, yet the share price has already run hard. Is this still a sensible entry point, or has the recent rebound gone too far?
Most Popular Narrative: 5% Overvalued
Avantor’s most followed narrative pegs fair value at $14.56 using an 8.87% discount rate, slightly below the $15.34 last close, which implies expectations are already built around a reasonably successful turnaround.
The numbers and current valuation together imply a stock price that already reflects a fair outcome where Avantor delivers on its multi-year turnaround and free cash flow targets without needing a sharp re-rating from here.
See why 10 investors see Avantor as 5% overvalued.
Result: Fair Value of $14.56 (OVERVALUED)
Still, if competitive pressure in lab distribution persists or key end markets remain sluggish, the Avantor Revival plan could deliver slower progress than this narrative assumes.
Find out about the key risks to this Avantor narrative.
Another View: Avantor’s valuation through the sales lens
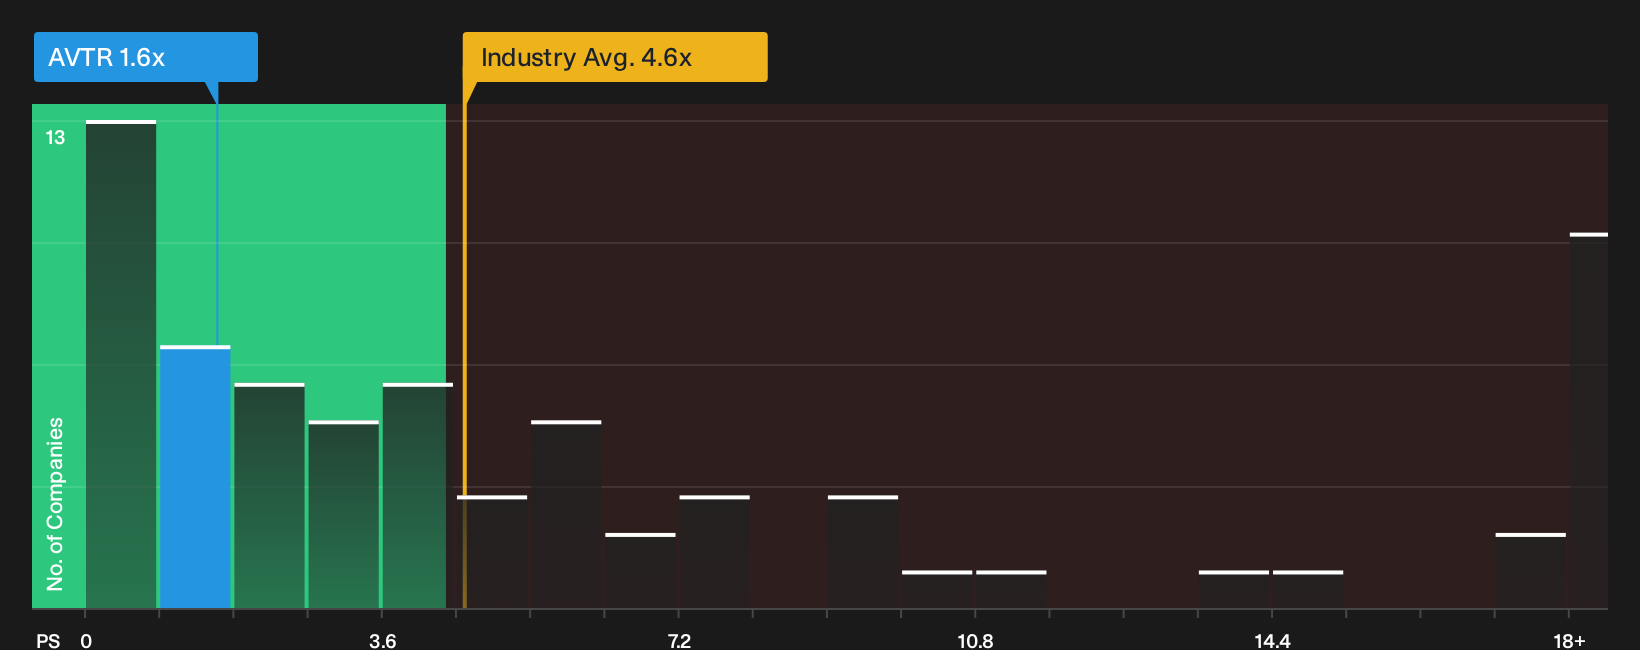
On one hand, the narrative fair value of $14.56 suggests Avantor is about 5% overvalued. On the other, the current P/S ratio of 1.6x looks inexpensive beside the Life Sciences industry at 4.6x and a fair ratio of 3.5x. That kind of gap can signal mispricing, or a reason the market stays cautious. Which side do you think has it right?
To see how the numbers line up in more detail, review the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Avantor’s value story so far. If you want to move quickly and build your own conviction, weigh both sides with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Avantor?
Do not get stuck on one ticker. Broaden your watchlist with fresh ideas that fit your style, whether you care more about value, resilience or income.
- Target durable compounding potential by hunting for quality businesses trading at a discount through the 31 high quality undervalued stocks.
- Prioritise resilience under pressure by focusing on companies with stronger balance sheets and fundamentals using the 31 resilient stocks with low risk scores.
- Strengthen your income stream by filtering for higher yielding opportunities with the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com