
Be a Contrarian and Load Up on Nike Stock on the Dip as the Payoffs Get Attractive
Nike stock (NKE) slumped on Friday after the company’s fiscal Q1 2027 earnings, released after the market closed the day before, disappointed investors. For investors, unfortunately, such post-earnings crashes have become the norm rather than the exception and only add to the stock’s overall losses.
Nike’s stock has been falling ever since it peaked in November 2021 and has closed in the red every year since. Unless things miraculously change over the next three months — something whose odds have been falling by the day — it is set to close in the red for the fifth consecutive year, a first in its history as a publicly-traded company.
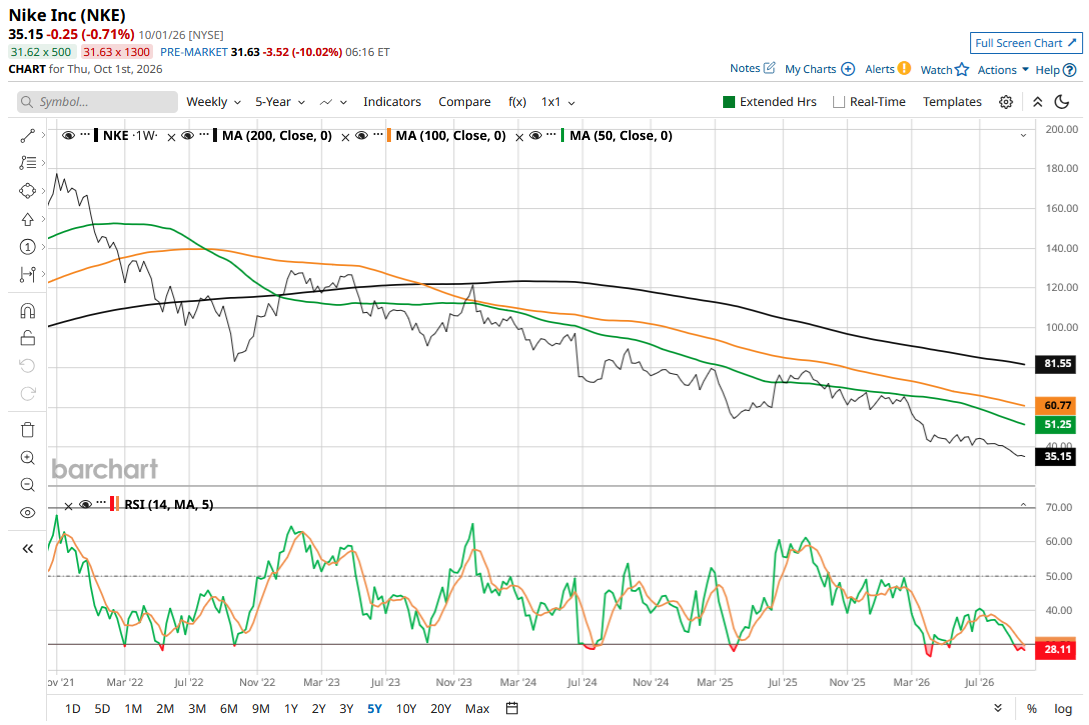
Nike Stock Keeps Slumping Despite the Turnaround Measures
Nike is undergoing a turnaround, a term I often say is perhaps the most abused in the corporate world. There are plenty of instances, Nike included, where the stock keeps falling from one low to another during the turnaround. While I was optimistic about Nike stock in the initial stages of the turnaround, I subsequently gave up and sold my holdings. In my most recent article, I noted that while I believed Nike stock was close to the bottom, I wouldn’t buy the stock heading into the Q1 earnings.
I was partially right: not buying Nike ahead of the earnings was the right move, but the stock has looked like a bottomless pit, slumping to new lows, or, to put it bluntly, multi-year lows. Meanwhile, I often refer to legendary investor Howard Marks’ quote — "it's not what you buy, it's what you pay.” It basically implies that the price at which you buy the asset is the key metric that determines the returns you make. In this article, we’ll explore whether Nike has become a compelling buy now despite all the woes that I discussed in a previous article.
Nike’s Q1 Earnings
Let’s first look at a snapshot of Nike’s Q1 earnings. Revenue fell 4% to $11.21 billion and was slightly short of Street estimates. The management blamed the sales decline in Greater China and the Europe, Middle East, and Africa (EMEA) region for the disappointing top-line performance. Greater China has been a particularly weak market, with sales falling 26% year-over-year in the quarter. Looking at the product portfolio, Jordan and the Sportswear segment remain a problem for Nike.
The company’s gross margins, however, expanded 60 basis points to 42.8%. Its earnings per share (EPS) came in at $0.48, down a penny from the corresponding quarter last year, but ahead of the $0.43 that analysts were modelling.
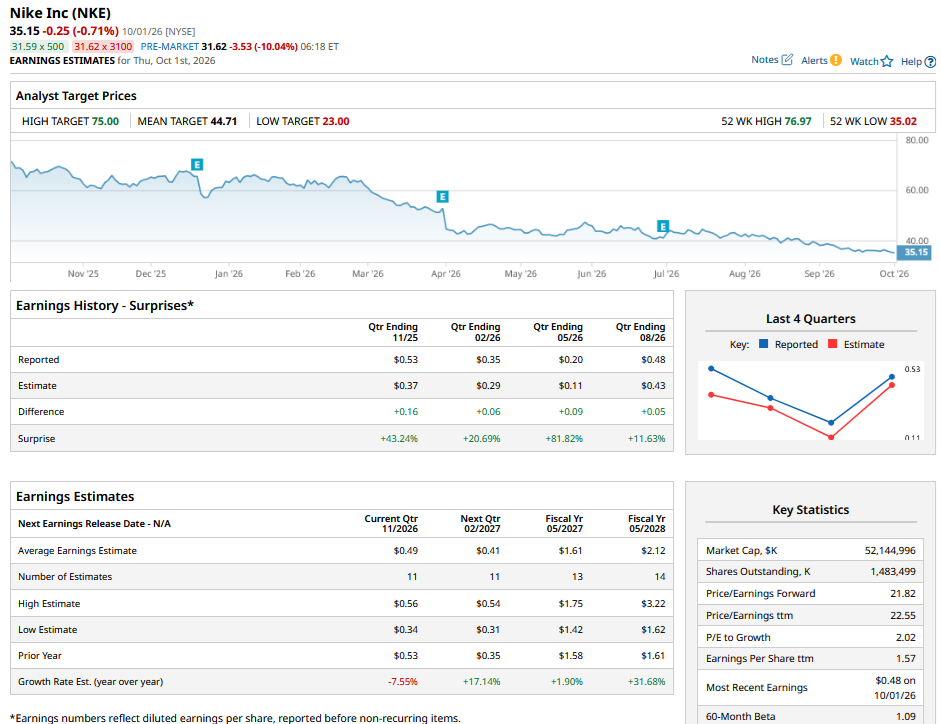
If the mixed earnings and the continued revenue decline weren’t enough, the company’s guidance added fuel to the fire. Nike expects sales to fall in high single digits in the quarter while guiding for adjusted EPS between $1.15 and $1.35. The guidance was below Street estimates and signals that the turnaround is turning out to be a lot harder than initially thought.
Nike previously outlined a “Win Now” turnaround plan and announced a new program dubbed “Pace” under which it expects to achieve around $2.5 billion in savings by fiscal year 2031. As part of the restructuring, it would reorganize into three geographies, with North America and Latin America becoming one segment under Americas. Similarly, Asia Pacific and Greater China would become one segment. The third segment would be EMEA, which stays as it was before the reorganization.
As is the case with these turnaround plans, they would lead to layoffs, with Nike announcing its third round this year without specifying the number. It also expects a per-share restructuring expense of $0.15 this year due to the restructuring.
Nike’s Woes Run Deep
Nike’s woes run quite deep, and it is battling both falling sales and profitability. Delivering on the bottomline is relatively easier with aggressive cost cuts. However, getting more consumers to buy your product is usually the toughest aspect. Peloton Interactive (PTON) is a case in point, as while the company has achieved GAAP profitability through relentless cost cuts, its sales continue to plummet — and so does its stock price.
Investors pay a premium for growth, and for a company struggling to grow its top line, markets look for deep discount valuations. Based on Nike’s fiscal 2027 EPS guidance, the stock still trades at a forward price-to-earnings (P/E) multiple of around 25x. The multiple won't appear attractive, but Nike is not a play on current earnings that are depressed, but on its return to normalized profitability.
However, the wait for that turnaround on profitability and the earnings bump has been getting painfully longer. I believe that as Nike slumps towards $30, it could become worth the risk for patient investors. The cherry on top would be the 5% dividend yield following today’s slump, even though the payout would be a drain on the company’s finances, with the dividend payout ratio set to top 100% for the second consecutive year. While headlines continue to remain negative, and Nike is set to face the wrath of the analyst community in the form of target price cuts and downgrades, I am buying the dip in Nike stock as a contrarian bet in my portfolio.
On the date of publication, Mohit Oberoi had a position in: PTON , NKE . All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.