
Kerry Group (ISE:KRZ) Opens Pennsylvania Coffee Facility, Is The Stock Still Cheap?
Why Kerry Group’s New U.S. Coffee Facility Matters for Investors
The ribbon is cut. Kerry Group (ISE:KRZ) has opened a coffee extraction facility in Bethlehem, Pennsylvania, its first manufacturing site in the state, focused on premium, tailored coffee ingredients.
This new plant targets growing U.S. demand for higher quality coffee experiences across ready to drink beverages, alcohol, desserts, and even savory products, using hot and cold brew extraction lines built to scale as orders increase.
Recent trading tells its own story. Kerry Group’s share price return is up 12.98% year to date and 4.49% over 90 days, while the 1 year total shareholder return of 15.64% contrasts with a 5 year total shareholder return that declined 20.68%, suggesting momentum has improved in the near term even as longer term holders remain underwater.
Scan for other food and beverage groups aiming to ride similar demand trends by reviewing our curated list of 192 high quality undervalued stocks.
The coffee push and recent 1 year rebound give Kerry Group fresh momentum. The real test now is whether the current valuation still offers an attractive skew toward buyers or leans more toward downside risk.
Most Popular Narrative: 13% Undervalued
Kerry Group last closed at €86.15, while the most followed narrative sets fair value at €99.00, framing current pricing as a discount that relies on specific growth and margin assumptions being met.
Kerry is poised to benefit from rising global demand for healthier, natural, and functional food solutions, as evidenced by strong volume growth in segments such as sugar/salt reduction, botanicals, and proactive health ingredients; these innovation-driven categories position Kerry for above-market revenue growth as the long-term shift toward health and wellness accelerates.
See why 11 investors see Kerry Group as 13% undervalued.
The fair value narrative uses a 6.39% discount rate, assumes revenue growth of about 5.1% a year and expects profit margins to move from 9.6% to 12.6%, with earnings reaching €970.9m by 2029. For those forecasts to justify the €99.00 figure, the shares would need to trade on a P/E of 17.8x that year, compared with a higher multiple today and above current earnings of €638.0m.
Result: Fair Value of €99.00 (UNDERVALUED)
Still, if end markets stay flattish and recent efficiency gains prove one off, the bullish Kerry Group narrative could look much more fragile.
Find out about the key risks to this Kerry Group narrative.
Another View On Kerry Group’s Valuation
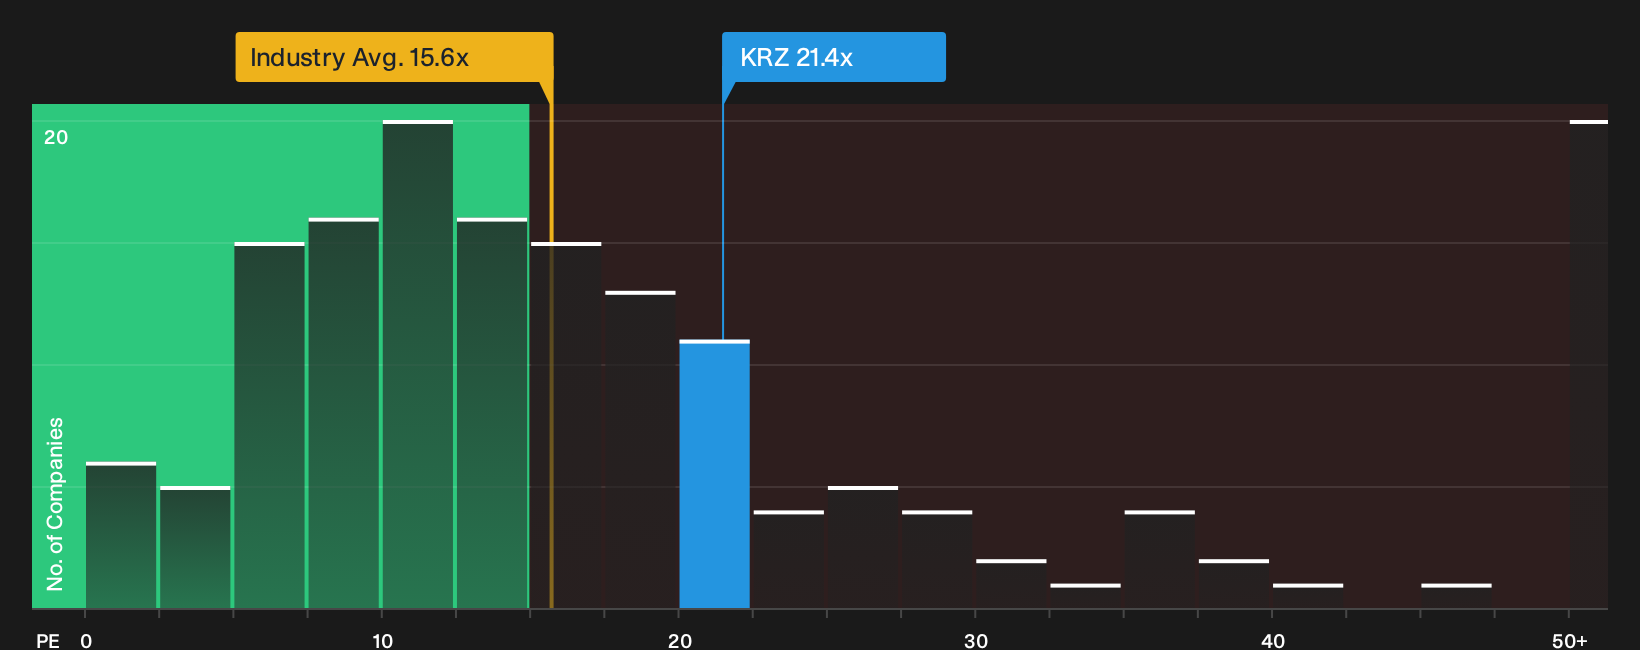
There is a catch. Even though Kerry Group screens as good value against an internal fair value estimate, the current P/E of 21.4x sits above the European Food industry on 15.6x and the peer average on 20.7x, and it is also richer than the fair ratio of 18.7x that the market could move toward over time.
If earnings progress stalls or sentiment cools, that premium multiple could compress and pull the share price toward that lower fair ratio level. The question for investors is whether the perceived quality and growth profile really justify paying up for Kerry Group today, or if the risk of a de-rating is being underappreciated.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Momentum and valuation can look compelling on paper, but your money only moves when you do. Pressure test the bullish angles, weigh the weak spots, then dig into the 3 key rewards.
Looking for more Kerry Group style investment ideas?
If Kerry Group has sharpened your appetite for new opportunities, do not stop here. Use the Simply Wall St screener to surface fresh, data driven ideas in minutes.
- Target reliable cash flows by scanning for companies with resilient payouts and income potential through our 168 dividend fortresses.
- Spot mispriced quality by zeroing in on businesses that combine strong fundamentals with appealing valuations using the 615 high quality undiscovered gems.
- Reduce portfolio stress by focusing on financially sturdy businesses and build a shortlist with the list of solid balance sheet and fundamentals (206 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com